
What Comes Next For Tsakos Energy Navigation After A 94% Gain
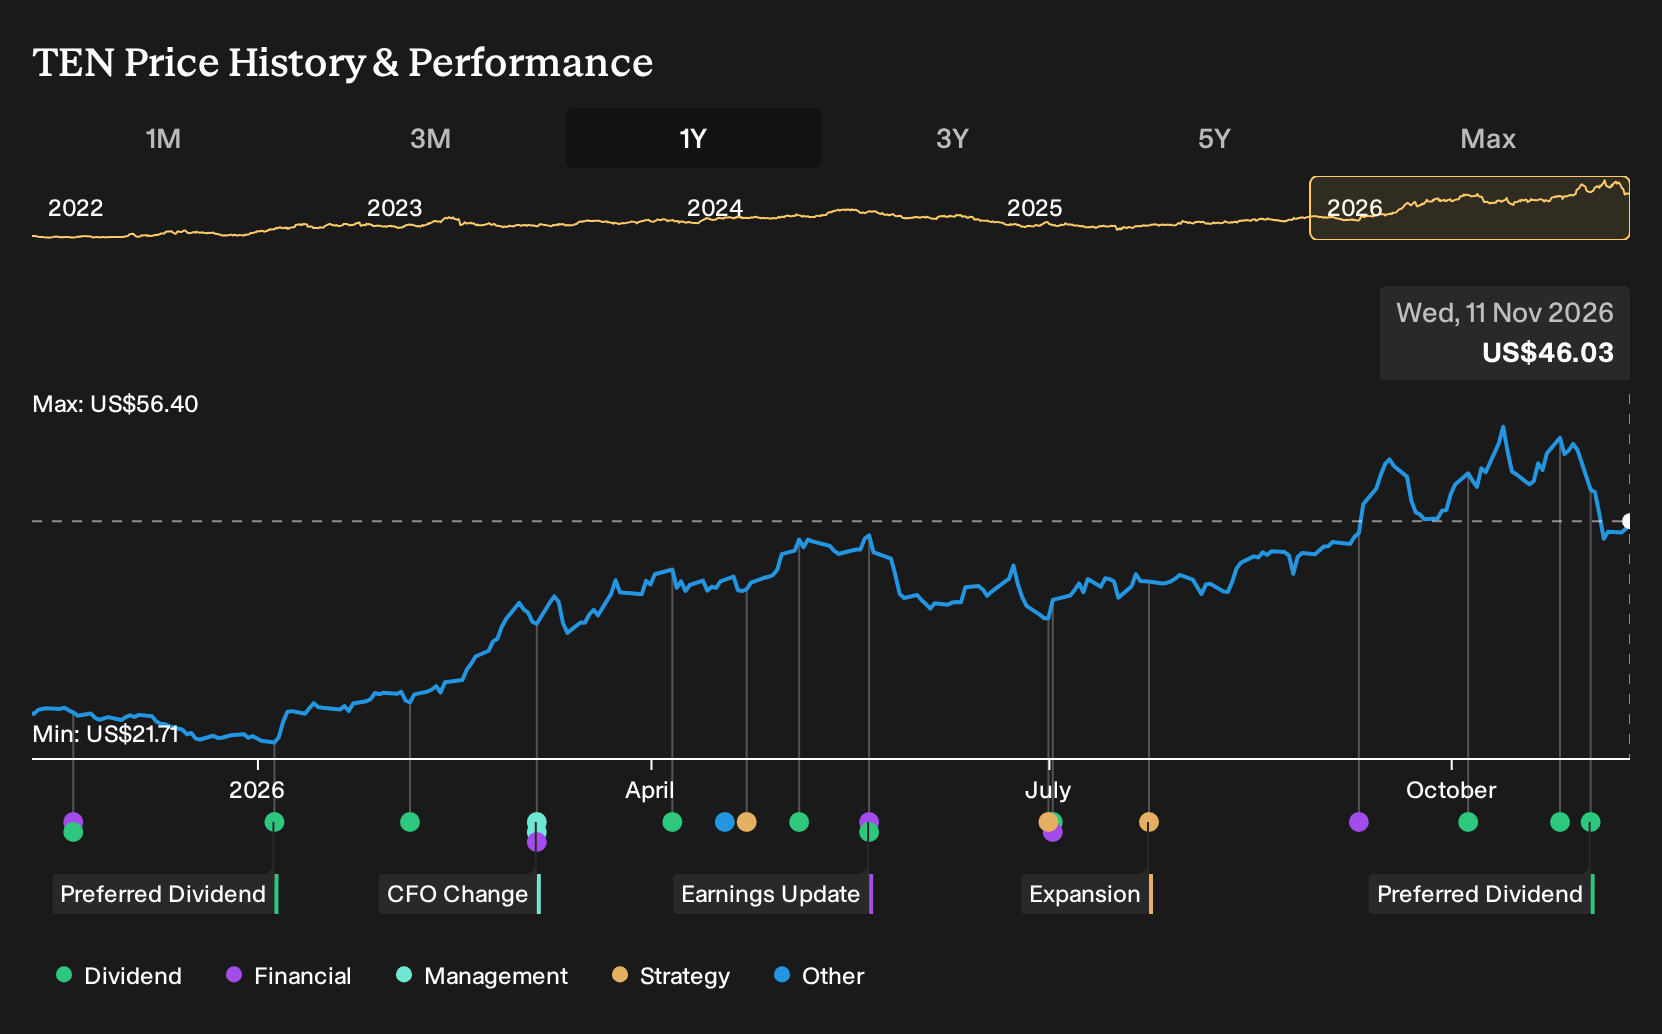
If you only glanced at Tsakos Energy Navigation’s headlines about record profits and richer dividends, the share price outcome still might surprise you. Investors who held Tsakos Energy Navigation over the past year are up 94.3%, including dividends. If you had been weighing those 2025 analyst debates about decarbonization risk, leverage and charter visibility, how much of this outcome felt supported by what was already on the record, and how much came from genuinely unpredictable forces?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Tsakos Energy Navigation. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Tsakos Energy Navigation
The shares cost US$24.85 at the start of the period, and you had to decide which story about Tsakos Energy Navigation felt more convincing.
The bullish narrative saw Fair Value at US$30.33, assuming modern, eco-friendly and dual fuel vessels would secure higher charter rates and support earnings resilience despite sector risks.
The cautious view put Fair Value at US$22, focusing on the possibility that tightening decarbonization rules and falling seaborne oil demand would require costly upgrades and squeeze long term profitability.
What The Results Changed For The Tsakos Energy Navigation Debate
The sharp move in Tsakos Energy Navigation’s results did most of the talking. Revenue increased from US$193.3m in Q2 2025 to US$298.4m in Q2 2026, while net income climbed from US$19.8m to US$131.9m and net margin shifted from 10.2% to 44.2%. That scale of profitability supported the more optimistic view of higher earning power.
The key lesson is simple. When a thesis leans on margin resilience, do not just watch the top line. Track net margin percentage through each report and judge whether pricing power and costs really moved in line with the underlying narrative.
What Tsakos Energy Navigation's Price Already Bakes In
Tsakos Energy Navigation now trades at US$46.03. The analyst consensus Narrative on Simply Wall St sees Fair Value above that level, anchored in a larger, younger fleet and a charter mix that aims to keep earnings more predictable while tanker markets remain tight.
The same Narrative leans heavily on Tsakos Energy Navigation recycling older ships into a big newbuilding plan and keeping long term and profit sharing contracts profitable. A buyer today has to judge whether that disciplined fleet renewal and charter strategy can keep working as assumed.
"Tsakos Energy Navigation is committing around $3.1–3.2b to a 20–26 vessel newbuilding pipeline while also adding modern secondhand ships. This increases future capital employed and can lift revenue and earnings expectations well beyond what current contracted cash flows support."
The price and this Narrative do not agree. → Uncover what this Narrative says Tsakos Energy Navigation is actually worth
Tsakos and the Energy Link
Tsakos lives on moving cargo. Your returns can depend on keeping that freight flowing.
Those barrels and molecules do not appear at ports by magic. Another business runs large pipeline and storage networks feeding power plants, data centers and export docks.
Its assets push gas and liquids where long term contracts direct them. That structure can keep volumes moving even when spot markets look unsettled.
As Tsakos investors weigh shipping exposure, this quiet toll collector on energy routes raises a new angle. How much value hides in simply owning the pipes and tanks?
One Narrative has already put a figure on it. → Uncover the company trading 21% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com