
How Third Quarter Earnings Will Impact Brink's (BCO) Stock
- Brink's reported third quarter 2026 results with sales of US$1,374.6 million and net income of US$14.5 million, alongside nine month revenue of US$4,142 million and net income of US$91 million.
- The earnings release showed sales higher than the prior year figures along with meaningfully lower net income and earnings per share. Management also issued fourth quarter 2026 revenue guidance of US$1,365 million to US$1,415 million, which helps frame near term demand expectations.
- We will now look at how Brink's investment narrative lines up with this quarter's lower earnings and new revenue guidance.
Compare Brink's latest quarter with other cash-flow focused opportunities by scanning our hand picked 30 resilient stocks with low risk scores that aim to pair steadier balance sheets with more resilient earnings profiles.
Brink's Investment Narrative Recap
To stay invested in Brink's, you need to be comfortable with a story that leans on ATM Managed Services and Digital Retail Solutions while the world gradually uses less physical cash. The analyst consensus Narrative on Simply Wall St frames NCR Atleos integration and margin improvement as key drivers, and this quarter's weaker earnings keep execution quality squarely in focus.
In the short term, the main focus is whether Brink's can convert its higher revenue base into steadier profit and cash generation as Atleos closes and leverage rises. The biggest risk is that softer earnings, together with interest costs that are not well covered by current profits, restrict how quickly the balance sheet can improve.
The new fourth quarter 2026 revenue outlook of US$1,365 million to US$1,415 million is the most relevant fresh data point. That range helps you gauge whether Brink's can sustain top line momentum in AMS and DRS while digesting the Atleos deal and working toward the larger scale described in the analyst consensus Narrative on Simply Wall St.
If reported revenue tracks near the middle or upper end of that band without further erosion in earnings per share, it would support the idea that underlying operations remain intact despite this year's profit pressure. If profit margins compress again against that guidance, it would highlight the risk that higher debt, weaker interest coverage, and slower free cash flow could weigh on the story for longer than investors expect.
Brink's narrative projects US$6.2b revenue and US$664.6 million earnings by 2029. This rests on analysts assuming 4.1% yearly revenue growth and an earnings increase of roughly US$483 million from US$181.2 million today.
Uncover why Brink's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
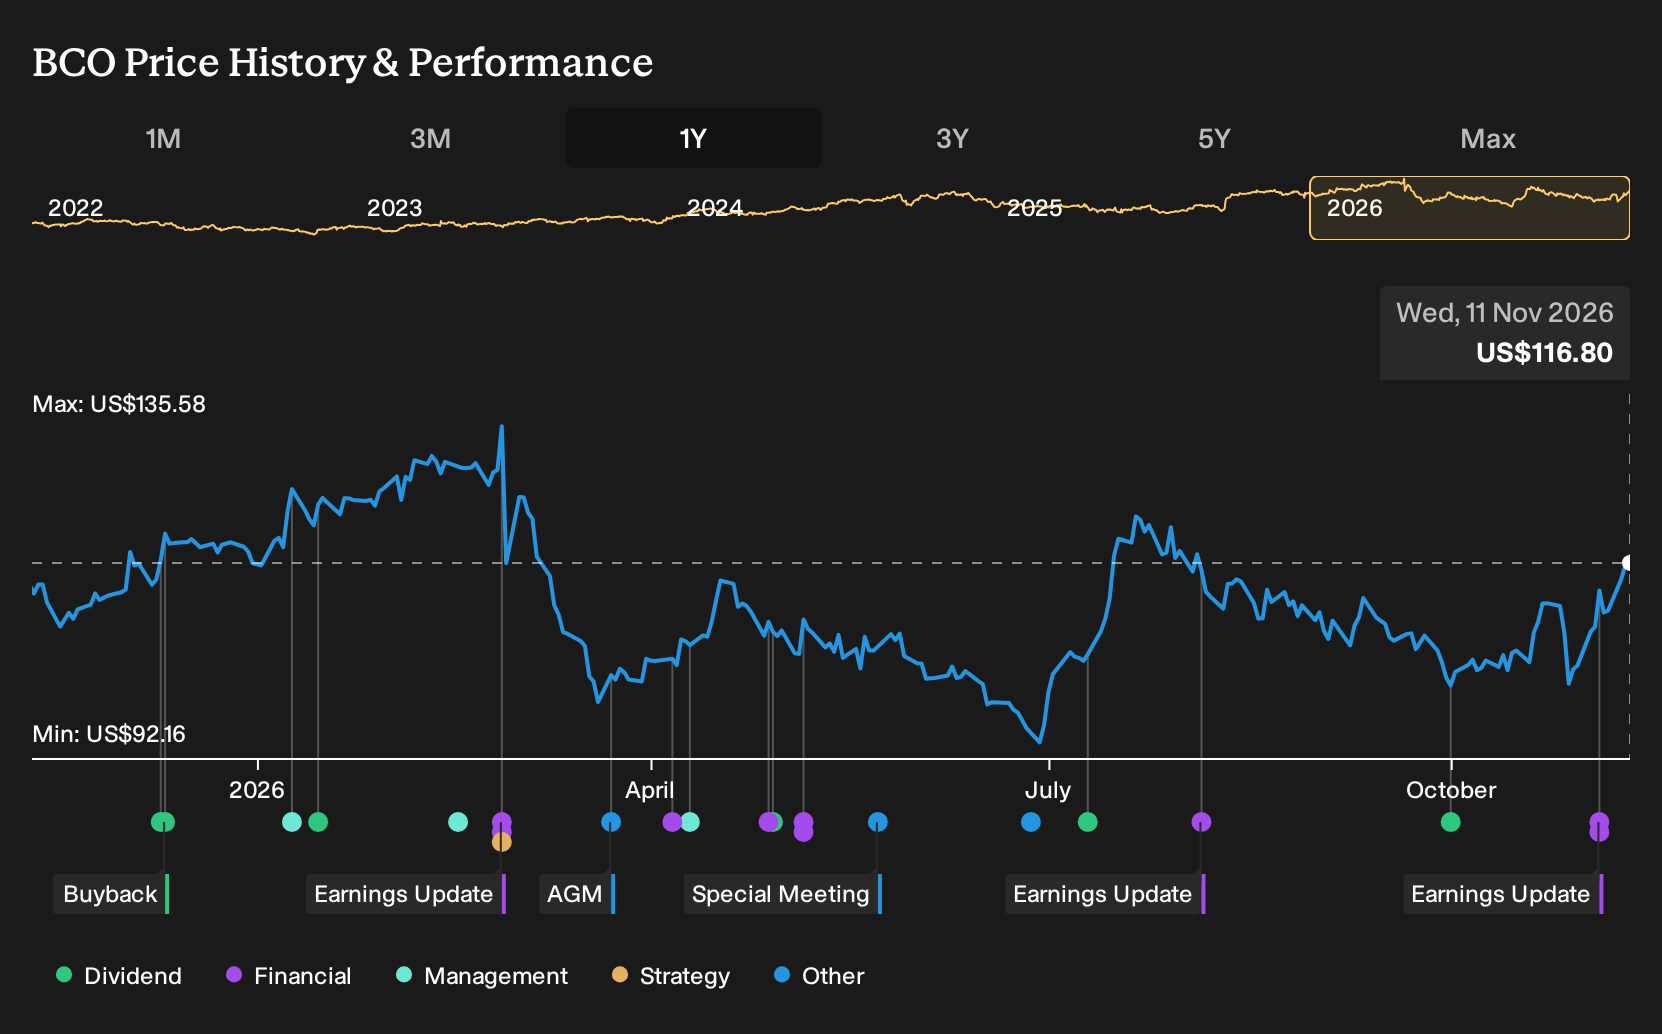
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$89 to US$146 per share, which already shows how far apart private investors can be on Brink's before the latest earnings news. When you set those pre-news opinions against rising leverage and the Atleos integration, you are encouraged to compare several contrasting viewpoints yourself.
Explore another Brink's fair value estimate, including one that suggests potential upside of as much as 25% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A useful starting point for your Brink's research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Brink's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Brink's overall financial profile at a glance.
Looking for more Brink's investment ideas and beyond?
Once you have a view on Brink's, it helps to line it up against other opportunities that fit the kind of portfolio you want to build. The Simply Wall St Screener can quickly surface stocks that match different risk levels, balance sheet profiles, and income goals so you are not relying on a single story.
- If you want steadier cash generation with less drama, start with a shortlist of companies that screen as having resilient profiles and lower risk by reviewing the 30 resilient stocks with low risk scores.
- If valuation discipline is your main filter, compare Brink's with a curated group of attractively priced businesses that combine quality fundamentals with more modest expectations through the 32 high quality undervalued stocks.
- If income matters most to you, line up Brink's against a focused collection of stocks offering robust yields that aim to balance payout with staying power using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com