
Upbound Group (UPBD) Stock Still Seems Undervalued On Its 64% Monthly Run
Upbound Group has surged onto investor screens after a sharp run in recent weeks, which naturally raises a question about whether the current share price still lines up with what its earnings can support. With the stock now reflecting a very different recent track record than a few years ago, the key issue is how much of that shift is already embedded in the valuation.
- The share price has climbed about 64.1% over the past month, which puts real pressure on the earnings story to justify such a rapid reset in expectations.
- Fresh earnings news that included stronger cash generation and a new US$50m buyback plan can shape how investors think about the durability and timing of Upbound Group's future profit streams.
- There is a second opinion on Upbound Group worth weighing. See what analysts think Upbound Group's shares could be worth.
The issue now is whether Upbound Group's current market value is well supported by its earnings profile after this recent jump.
If you want to pressure test this kind of earnings driven rerating beyond Upbound Group, compare it with 32 high quality undervalued stocks.
Is Upbound Group a Bargain on Earnings?
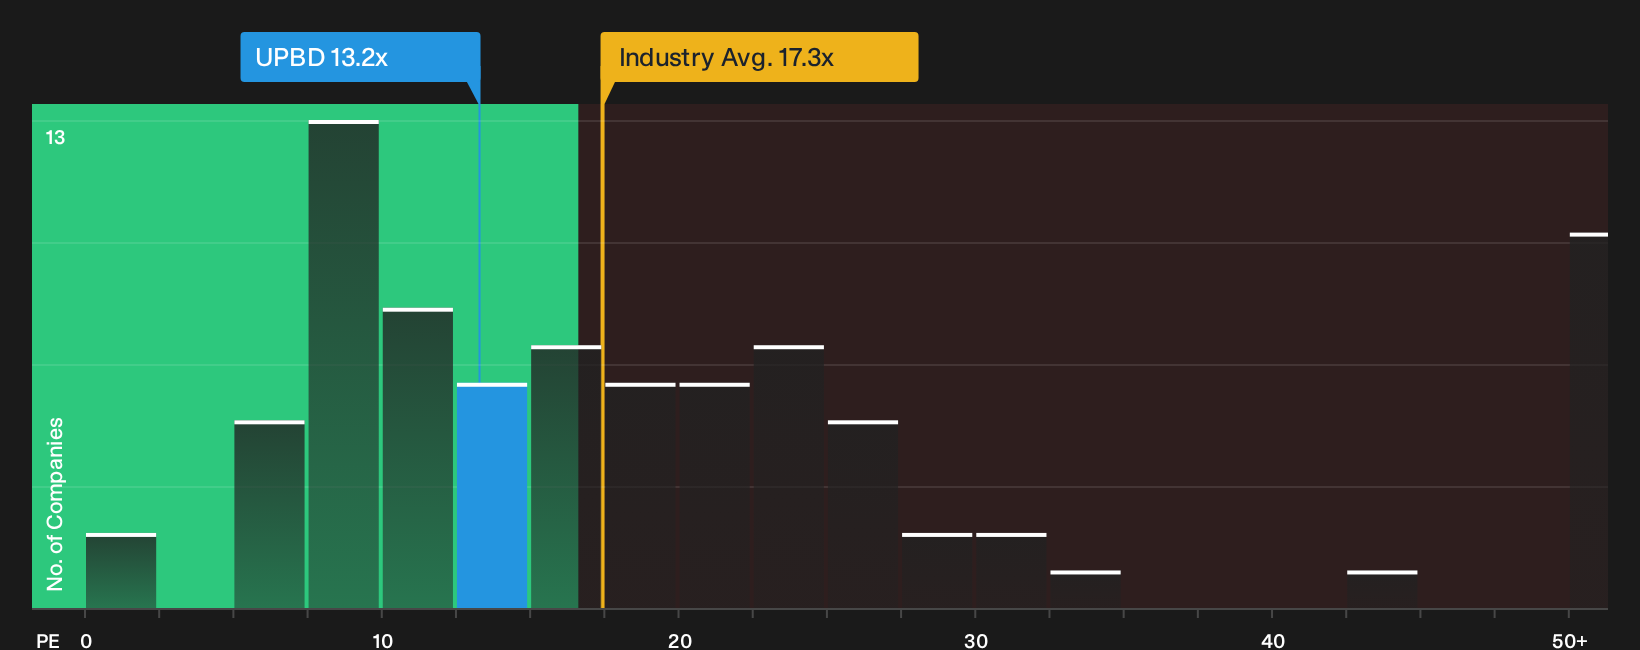
The P/E ratio is a useful lens for Upbound Group because earnings are a core focus for investors after the latest results and buyback announcement. On this measure, the stock trades at about 13.2x earnings, which is below the Specialty Retail industry average of roughly 17.3x and also under the broader peer group on about 22.0x. That kind of gap means the market is attaching a lower earnings multiple to Upbound Group than to many comparable retailers.
The fair P/E level implied by the valuation work is higher than where the shares change hands today. This points to the stock being undervalued on this metric given its mix of growth profile, profitability, size and risk. Because the Q3 2026 earnings beat and stronger cash generation have already reset expectations upward, a P/E that still trails both sector norms and this tailored fair range suggests investors are not fully crediting the recent progress. Explore the numbers behind Upbound Group's P/E valuation.
The Upbound Group Narrative: What Would Justify Today's Price?
Narratives for Upbound Group pick up where the valuation gap leaves off by spelling out which combinations of future growth, profitability and earnings resilience would need to play out for the stock to be worth materially more or materially less than it trades for today. They sit on Simply Wall St's Community page as structured viewpoints that frame fair value as a thesis you can track over time rather than a single snapshot.
Bulls and bears looking at Upbound Group are reacting to the same cash and credit data but drawing very different conclusions about what it all justifies.
Bull case: 11% undervalued
The analyst consensus Narrative on Simply Wall St frames the upside around execution in Brigit, Acima and Rent-A-Center.
"The main thing that has to go right is that Brigit continues to scale paying users and new products while Acima and Rent-A-Center sustain disciplined credit performance and cash generation in a pressured non-prime consumer market…"
Discover why this Narrative puts Upbound Group at 11% undervalued.
Bear case: 26% overvalued
The bearish analyst Narrative on Simply Wall St focuses on volume strain, fixed costs and how they feed through to earnings power.
"Bearish analysts expect Upbound Group to face ongoing pressure on Acima GMV and Rent-A-Center revenue because tighter underwriting, cyber issues and weak durable goods demand limit volume growth and keep consolidated EPS under strain…"
Explore why this Narrative puts Upbound Group at 26% overvalued.
Why Upbound Group's price is only half the real decision
Valuation work can frame what you pay for Upbound Group, but the people setting priorities, taking risk and deciding their own rewards can pull the business in very different directions over time. See who runs Upbound Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com