
What Hecla Mining (HL)'s Preferred Stock Redemption Means For Shareholders
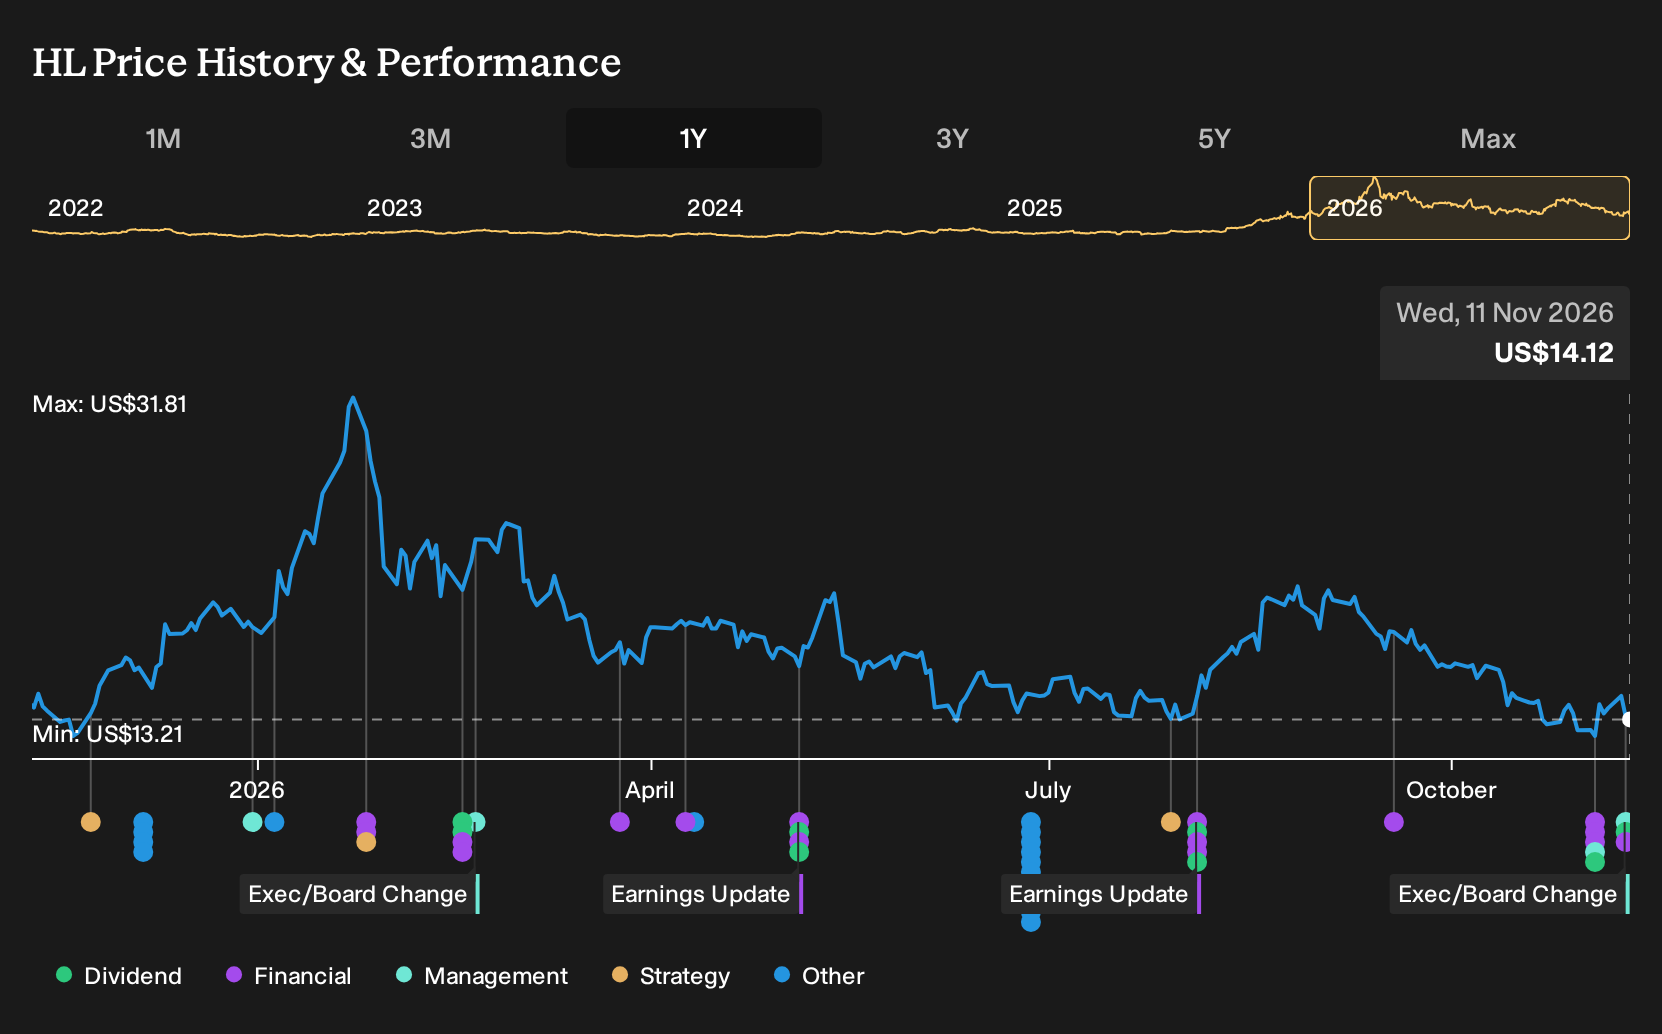
- Hecla Mining announced it will redeem all outstanding Series B Cumulative Convertible Preferred Stock in December 2026 and has also filed for an at the market common share offering to raise additional equity capital.
- This mix of preferred stock redemption and incremental common issuance reshapes Hecla Mining's capital structure and concentrates investor exposure in the common equity.
- This article examines how Hecla Mining's investment narrative is affected by the preferred redemption and the new at the market equity program.
Scan how Hecla Mining’s capital moves compare with peers by reviewing hand picked 10 top silver producer stocks that are shaping the next phase of precious metals exposure.
Hecla Mining Investment Narrative Recap
To own Hecla Mining, you need to be comfortable with a silver focused producer that is leaning on operational efficiency and mine development, while accepting that analysts in the analyst consensus Narrative on Simply Wall St expect revenue to contract and margins to narrow over the next few years. The near term story rests on execution at assets like Keno Hill and Greens Creek, and the latest preferred redemption and at the market filing do not materially change those operating priorities.
The bigger swing factor right now is how consistently Hecla Mining converts recent earnings strength into cash that can fund higher capital needs at Keno Hill and manage mine life and grade challenges at assets such as Casa Berardi. Key risks stay tied to rising regulatory costs, potential permitting delays and the possibility that future share issuance, including the at the market program, adds dilution if internal cash flow falls short.
The preferred stock redemption announcement intersects most directly with the existing risk in the analyst consensus Narrative on Simply Wall St around potential dilution from future equity issuance and balance sheet reshaping. Calling the Series B preferred and opening an at the market program together concentrates investors in the common equity and may increase sensitivity to any incremental share issuance over time.
For catalysts, the more interesting fresh data point is the third quarter 2026 earnings release, with US$394.82 million of sales and US$149.6 million of net income, paired with production guidance that lifts the low end of expected 2026 silver output. Those figures, alongside ongoing cost work and technology investment at mines like Greens Creek and Lucky Friday, frame how much room Hecla Mining has to absorb higher capital spending while still funding growth projects internally.
Hecla Mining's current analyst narrative points to revenue of US$1.6b and earnings of US$449.7 million by 2029, based on a forecast 3.3% yearly revenue decline and an earnings decrease of about US$102.8 million from US$552.5 million today.
Uncover why Hecla Mining's fair value indicates a 56% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Hecla Mining leans heavily on valuation risk. The most pessimistic analysts already treated the business as fully valued, using revenue of about US$1.4b and earnings near US$540.9 million by 2029. Those estimates came before this preferred redemption and at the market plan, so their narrative could shift as new information beds in.
Explore 4 other Hecla Mining fair value estimates, including one that suggests it could be worth just $16.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hecla Mining research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hecla Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hecla Mining's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hecla Mining?
If Hecla Mining is on your radar, it can help to compare it against other opportunities that line up with your risk tolerance, income needs, and quality preferences. The Simply Wall St Screener offers curated sets of stocks that share similar traits, so you can test your thesis and spot alternatives quickly.
- If you want potential mispricing and quality together, start with a focused group of 32 high quality undervalued stocks that pair stronger fundamentals with cheaper valuations.
- For investors who care most about balance sheet strength and durability, filter your watchlist through a list of solid balance sheet and fundamentals (23 results) to see which companies have more robust financial footing.
- If you prefer less headline risk and steadier profiles, scan a 30 resilient stocks with low risk scores that screens for resilience and more measured volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com