
Boyd Group Services (TSX:BYD) Stock Still Looks Cheap Following Its 56% Slide
Boyd Group Services has seen its share price fall sharply over the past few years. That slide raises a simple question for investors who follow the stock: does today's valuation still line up with the sales the business is generating?
- The share price has fallen 55.7% over the past three years, which puts the focus firmly on whether the current market value still reflects the strength of the company's revenue base.
- Recent sales growth and margin improvements suggest the repair network can potentially support different expectations for future revenue scale and cash generation than in the past.
- The analysts covering Boyd Group Services have run their own numbers. See what analysts think Boyd Group Services's shares could be worth.
The issue now is whether Boyd Group Services' current share price is justified by its sales when set against the Fair Ratio benchmark investors often watch.
If you are weighing Boyd Group Services against other options that focus on business quality and pricing, it can help to compare it with companies in the 5 high quality undervalued stocks.
Does Boyd Group Services Look Undervalued on Sales?
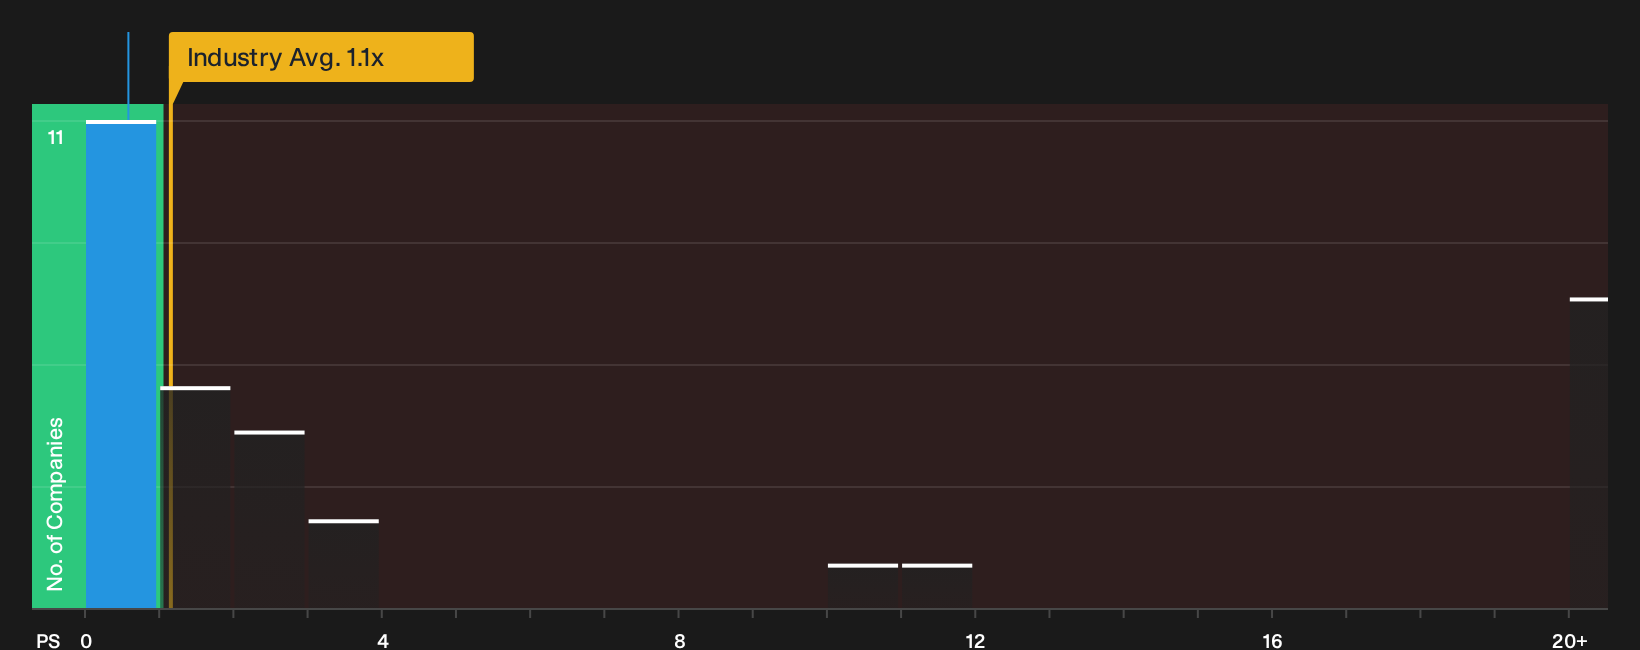
A price to sales lens fits Boyd Group Services because the business model leans heavily on revenue throughput across a large repair network, and earnings can swing around as costs and investments move. On that yardstick, the stock trades on a P/S ratio of about 0.6x, which is well below the Commercial Services sector average of roughly 1.0x and also under the peer group on about 1.7x.
Because the Fair Ratio folds in Boyd Group Services' growth profile, margin structure, size and risk, this framework points to the current P/S sitting below what might be expected for the company. The recent Q3 2026 update, with higher reported sales supported by Project 360 and acquisitions, has not closed that gap, so the share price still reflects a lower revenue multiple than this model suggests. That sets up a situation where the stock screens as undervalued on P/S against its tailored benchmark, although you still need to weigh the quality and durability of those sales before drawing a firm conclusion. Explore the numbers behind Boyd Group Services's P/S valuation.
The Boyd Group Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Boyd Group Services pick up where this valuation question leaves off by spelling out what kind of future growth, margin profile and earnings path would need to play out for the current share price to look meaningfully high or low. Each scenario ties its implied number to a clear view on how Boyd Group Services' revenue mix, profitability and risk might evolve, giving you a reference point you can revisit as fresh results and updates emerge on the Community page.
One of the top narratives on Boyd Group Services: 50% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor is that Boyd turns its cost programs and high gross margin calibration work into sustained margin expansion that more than offsets integration costs…"
Discover why this Narrative puts Boyd Group Services at 50% undervalued.
One more Boyd Group Services signal to check before you move on
There is a whole other lens on Boyd Group Services in how professional analysts map out revenue and earnings a few years from now, giving you another reference point to compare with today's pricing. Explore where analysts expect Boyd Group Services to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com