
Sumitomo Warehouse (TSE:9303) Half Year Earnings Growth Puts Its Valuation Back In Focus
Sumitomo Warehouse (TSE:9303) has released half-year results reporting higher sales, revenue, net income, and earnings per share compared with the same period a year earlier, giving investors fresh numbers to assess.
The latest half-year announcement lands after a mixed run for the stock, with the share price down 5.92% over the past month and 2.81% over the last quarter, yet still up 11.03% year to date. Over a longer horizon, momentum has been positive, with total shareholder return of 22.92% over one year and very strong compounding over three and five years, which suggests investors have been rewarding Sumitomo Warehouse over time despite shorter term share price softness.
Scan how Sumitomo Warehouse compares with other logistics and transport players that are also posting solid operational results by reviewing the hand picked list of solid balance sheet and fundamentals (24 results)
Sumitomo Warehouse now has stronger half year earnings on the table, yet the share price has slipped over the past month. So are investors getting a solid logistics business at a fair price today?
Preferred P/E of 14.8x for Sumitomo Warehouse: Is it justified?
On Simply Wall St's numbers, Sumitomo Warehouse trades on a P/E of 14.8x while also sitting about 39.8% below the SWS DCF estimate of its future cash flow value of ¥6,604.44 per share. This puts the current ¥3,975 price in an interesting spot for anyone weighing growth expectations against valuation.
The P/E ratio links the ¥3,975 share price to the earnings per share that the logistics group generates, and it shows how much investors are currently willing to pay for each unit of profit. For a mature warehousing and transport operator, this yardstick is a common way to compare how the market is pricing its profitability against other infrastructure related businesses.
Sumitomo Warehouse is described as expensive on this metric, with its 14.8x P/E above the peer average of 12.1x and also higher than the estimated fair P/E of 12.4x that the SWS model suggests the market could move towards over time based on historical relationships between valuation and fundamentals. That stronger pricing relative to both the Asian Infrastructure industry average P/E of 13.5x and the fair ratio implies investors are paying a premium compared with sector norms.
Explore the SWS fair ratio for Sumitomo Warehouse.
Result: Price-to-Earnings of 14.8x (OVERVALUED)
Still, the annual net income decline, alongside a relatively high P/E, leaves Sumitomo Warehouse exposed if earnings momentum stalls or discount rate assumptions shift.
Find out about the key risks to this Sumitomo Warehouse narrative.
Another view on Sumitomo Warehouse's value
While the P/E of 14.8x makes Sumitomo Warehouse look expensive against peers, the SWS DCF model presents a different perspective. On that framework, the estimated future cash flow value sits at ¥6,604.44 per share, which is above the current ¥3,975 level.
The gap between price and this cash flow based estimate highlights a very different risk reward balance compared with the earnings multiple view. This raises the question of which lens to prioritize for a long term holding in a mature logistics group.
Look into how the SWS DCF model arrives at its fair value.
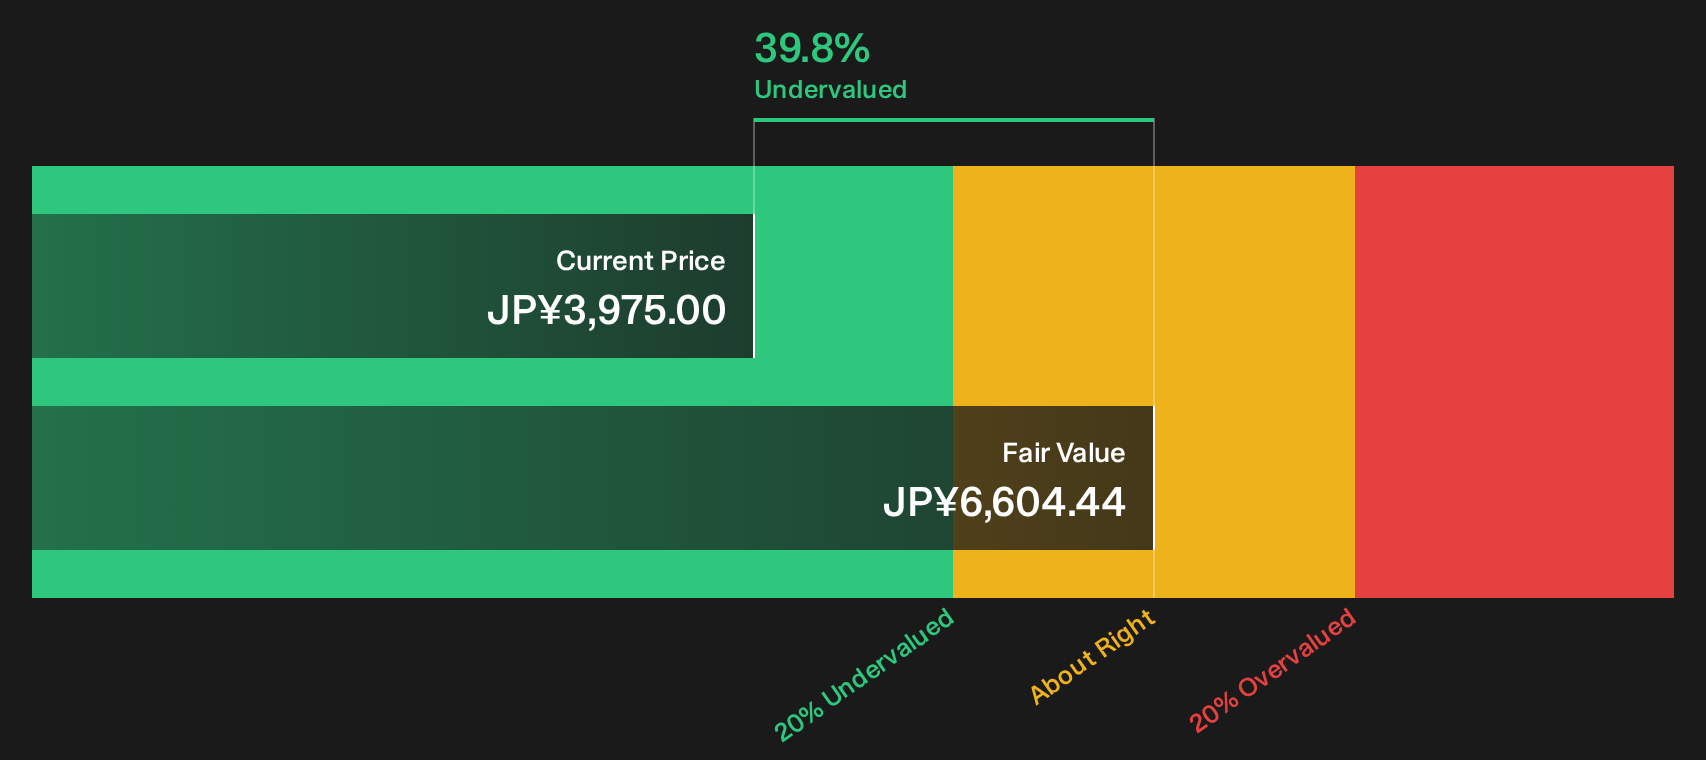
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sumitomo Warehouse for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 20 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sumitomo Warehouse so far. If the combination of potential downsides and positives matters to you, it may be worth reviewing the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Sumitomo Warehouse?
If Sumitomo Warehouse has sharpened your focus on quality, do not stop here. Broader idea hunting with structured tools can help you stress test your thinking.
- Target resilient payers that might help support your income goals by scanning companies in the 26 dividend fortresses.
- Hunt for quality at a reduced price tag by filtering for companies in the 20 high quality undervalued stocks.
- Reduce unpleasant surprises by focusing your research on the 19 resilient stocks with low risk scores that clear strict risk filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com