
Does Gold.com (NYSE:GOLD) Leave Enough Room For Earnings Doubts?
Gold.com has pulled back in recent weeks after a strong multi year run, which puts fresh attention on whether the current share price still lines up with the earnings power behind the stock. With a new shareholder investigation in the background, the question is how much the market should pay today for the profits this business is generating.
- Over the past 3 years, Gold.com has returned about 57.0%, so a lot of investor confidence is already embedded in the price and now hinges on the durability of its earnings.
- The recently announced investigation into possible fiduciary breaches by certain officers and directors may influence how investors think about governance, potential costs and ultimately the portion of earnings that can be relied on to support long term valuation.
- The analysts covering Gold.com have run their own numbers. See what analysts think Gold.com's shares could be worth.
The issue now is whether Gold.com's current market value is adequately backed by its earnings when you look past the recent share price swings and legal headlines.
If you are weighing Gold.com's recent pullback against its earnings, it can help to compare that situation with companies filtered using the same lens through 32 high quality undervalued stocks.
Where Does Gold.com Sit on Earnings?
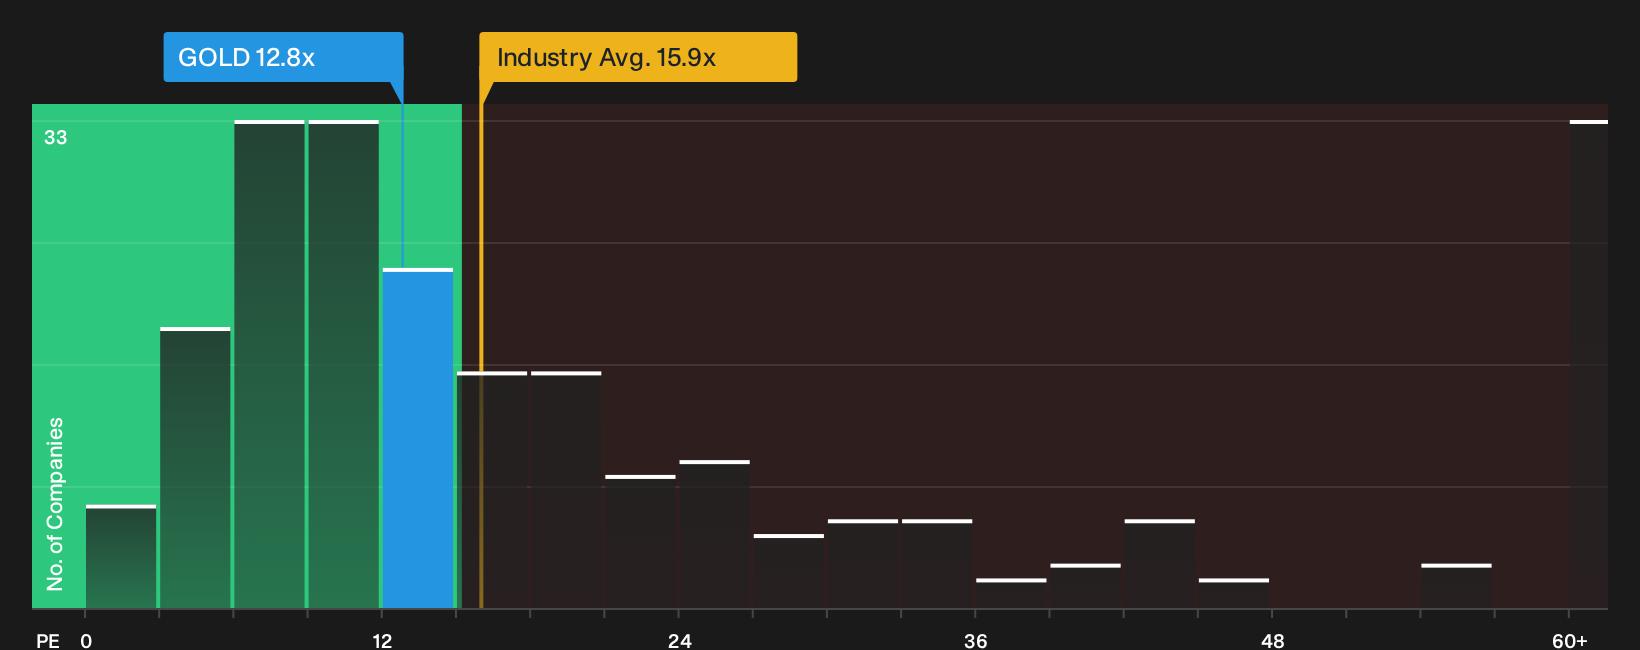
The P/E ratio fits Gold.com because earnings are the key driver of how investors usually look at this type of business. Right now the stock trades at about 12.8x earnings, compared with roughly 15.9x for the wider Retail Distributors group and a peer set around 16.5x. On the modelled fair multiple that blends growth, profitability, size and risk, Gold.com is close to what that framework would suggest rather than flashing an obvious bargain or bubble.
Because the current investigation into possible fiduciary breaches introduces questions about governance and potential costs, the gap between the market P/E and that tailored fair level can also be read as the price investors are putting on those concerns today. For anyone assessing whether the pullback has gone too far, the key test is whether Gold.com's earnings quality and governance profile justify moving closer to or further away from that implied fair multiple. Explore the numbers behind Gold.com's P/E valuation.
The Gold.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take Gold.com's current valuation puzzle and map it to clear scenarios for future growth, margins and earnings so you can see what would need to change for the stock to be worth meaningfully more or less than it is today. Each scenario links its headline number to a specific view on how growth, profitability and risks might shift, giving you a reference point you can revisit as fresh information comes through on the Community page.
One of the top narratives on Gold.com: 16% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The main thing that has to go right is that Gold.com successfully turns its larger vertically integrated platform and Tether partnership into higher quality recurring earnings..."
Discover why this Narrative puts Gold.com at 16% undervalued.
Gold.com’s valuation still leaves one important gap
Price multiples and earnings only tell part of the story for Gold.com, because the research checks also highlight specific risk flags that deserve attention before any firm conclusion on the stock. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com