
Should Earnings Beat Require Action From Kadant Stock Investors?
- Kadant reported third quarter 2026 sales of US$313.16 million and net income of US$35.07 million, with both basic and diluted EPS from continuing operations above the prior year, and issued fresh fourth quarter and full year guidance alongside these figures.
- The company slightly increased its 2026 revenue and GAAP EPS guidance ranges. This reinforces the earlier narrative around backlog conversion, aftermarket contribution and acquisition integration as key drivers of earnings quality.
- We will now look at how Kadant's raised full year guidance reshapes the investment narrative built around backlog and aftermarket strength.
Kadant Investment Narrative Recap
To own Kadant, you need to be comfortable with a story built on an aging installed base that supports recurring aftermarket demand, plus a sizeable equipment backlog that still has to be converted into revenue. The third quarter numbers, with US$313.16 million in sales and US$35.07 million in net income, keep that operational story intact rather than reshaping it.
The near term swing factor is still how efficiently Kadant turns backlog and recent acquisitions into earnings without further margin pressure from mix and amortization. The biggest risk remains integration drag and weaker European capital spending, and the latest results and guidance tweaks do not materially change that risk profile.
The raised full year 2026 guidance looks most relevant here. Management now sees revenue of US$1.195 billion to US$1.210 billion and GAAP EPS of US$9.88 to US$10.03, a modest lift on the prior revenue range while keeping the top of the EPS range unchanged.
That small upgrade sits alongside solid year to date performance, with nine month sales of US$907.54 million and net income of US$93.05 million. For investors watching catalysts, it frames expectations for fourth quarter execution and leaves the spotlight on backlog conversion, aftermarket resilience, and how quickly acquisition related dilution from deals like Kadant Profil can ease.
Kadant's narrative projects US$1.4b revenue and US$177.6 million earnings by 2029. That outlook assumes 6.6% yearly revenue growth and an earnings increase of about US$67.9 million from US$109.7 million today.
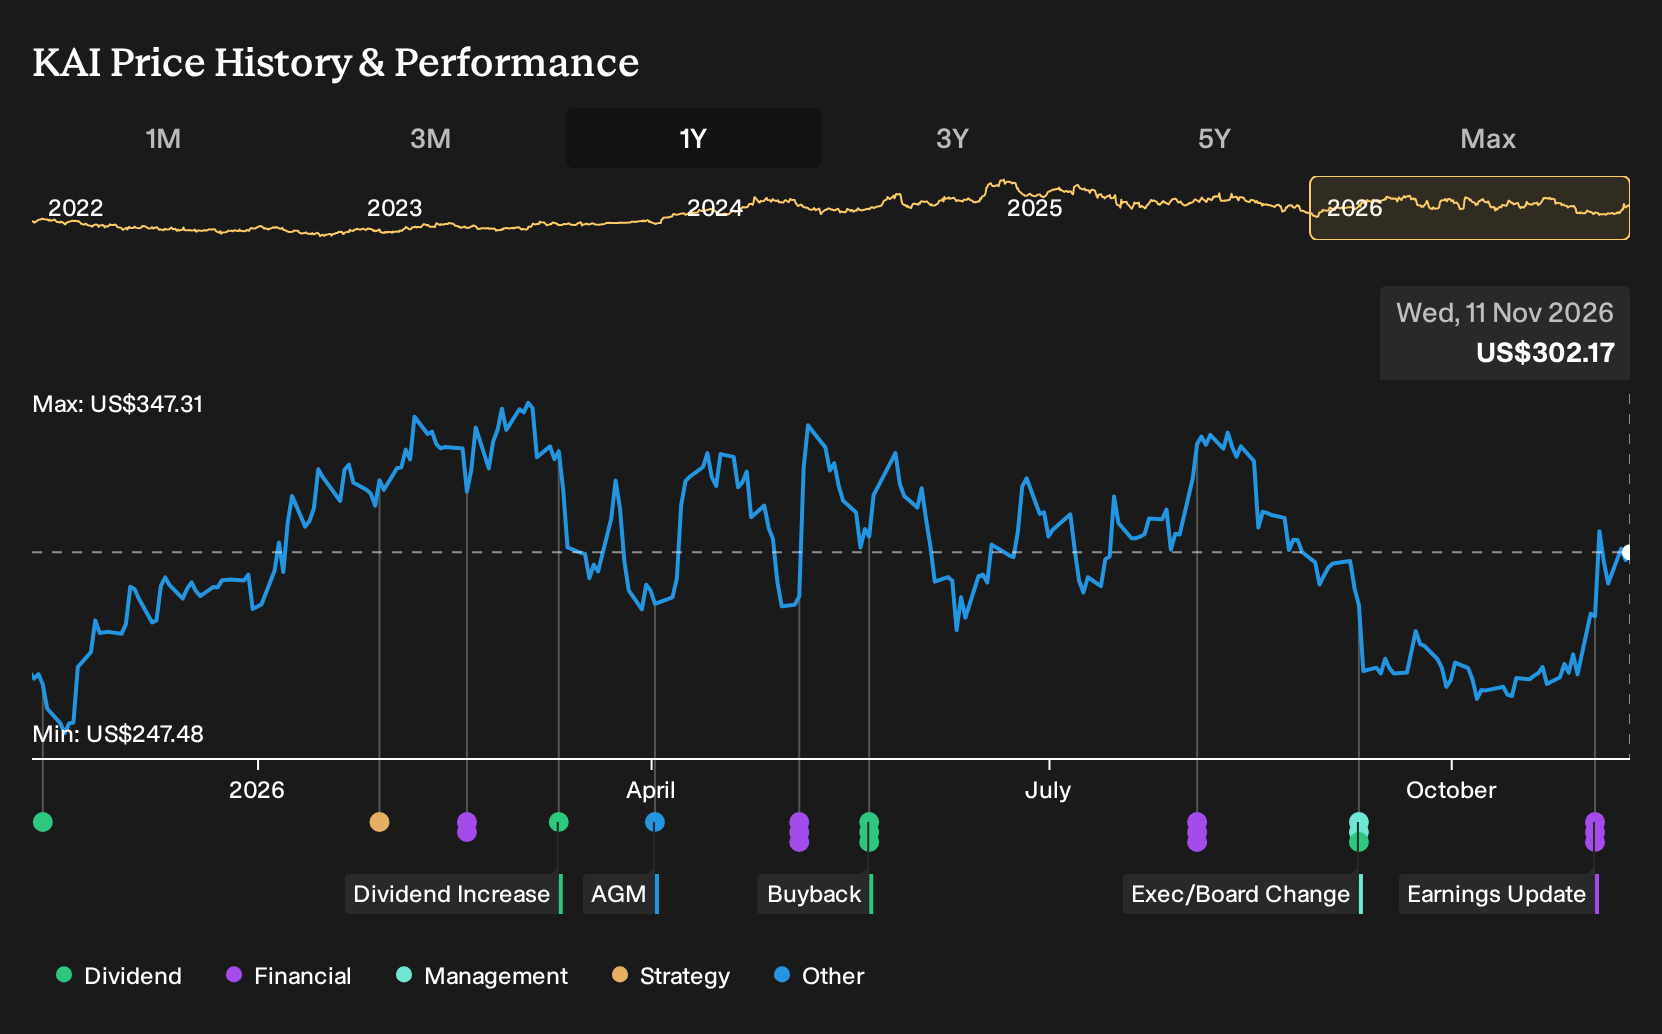
Uncover why Kadant's fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Kadant focuses on mix risk rather than backlog strength. The most cautious analysts worry that heavier capital equipment exposure could pressure profitability, even with rising aftermarket sales. Before this earnings report and guidance lift, the lowest forecasts still had revenue reaching about US$1.4b and earnings of roughly US$181.0 million by 2029. That is actually more optimistic on long term profit than the consensus today implies, yet paired with a lower assumed P/E multiple. In other words, there is a bundle of concern about the quality of earnings, not the absolute size. As you weigh this new quarter, treat these pre news estimates as moving targets and use them to stress test your own view.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Kadant research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Kadant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kadant's overall financial health at a glance.
Looking for more investment ideas beyond Kadant?
If the Kadant story has sharpened your sense of what quality looks like, use that same filter across a wider universe of stocks. The Simply Wall St Screener helps you quickly sort for companies that line up with the balance of risk, income, and value that suits your own plan.
- For investors who want income to feel reliable, focus on businesses with robust cash flows and payout track records using the 6 dividend fortresses.
- If capital preservation sits high on your priority list, narrow your search to companies with stronger balance sheets and sturdier fundamentals by running the list of solid balance sheet and fundamentals (23 results).
- When you are hunting for underappreciated opportunities with quality metrics on their side, start with the 32 high quality undervalued stocks and see which stocks match your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com