
Will Raised Earnings Guidance Change OPENLANE (OPLN) Stock Narrative
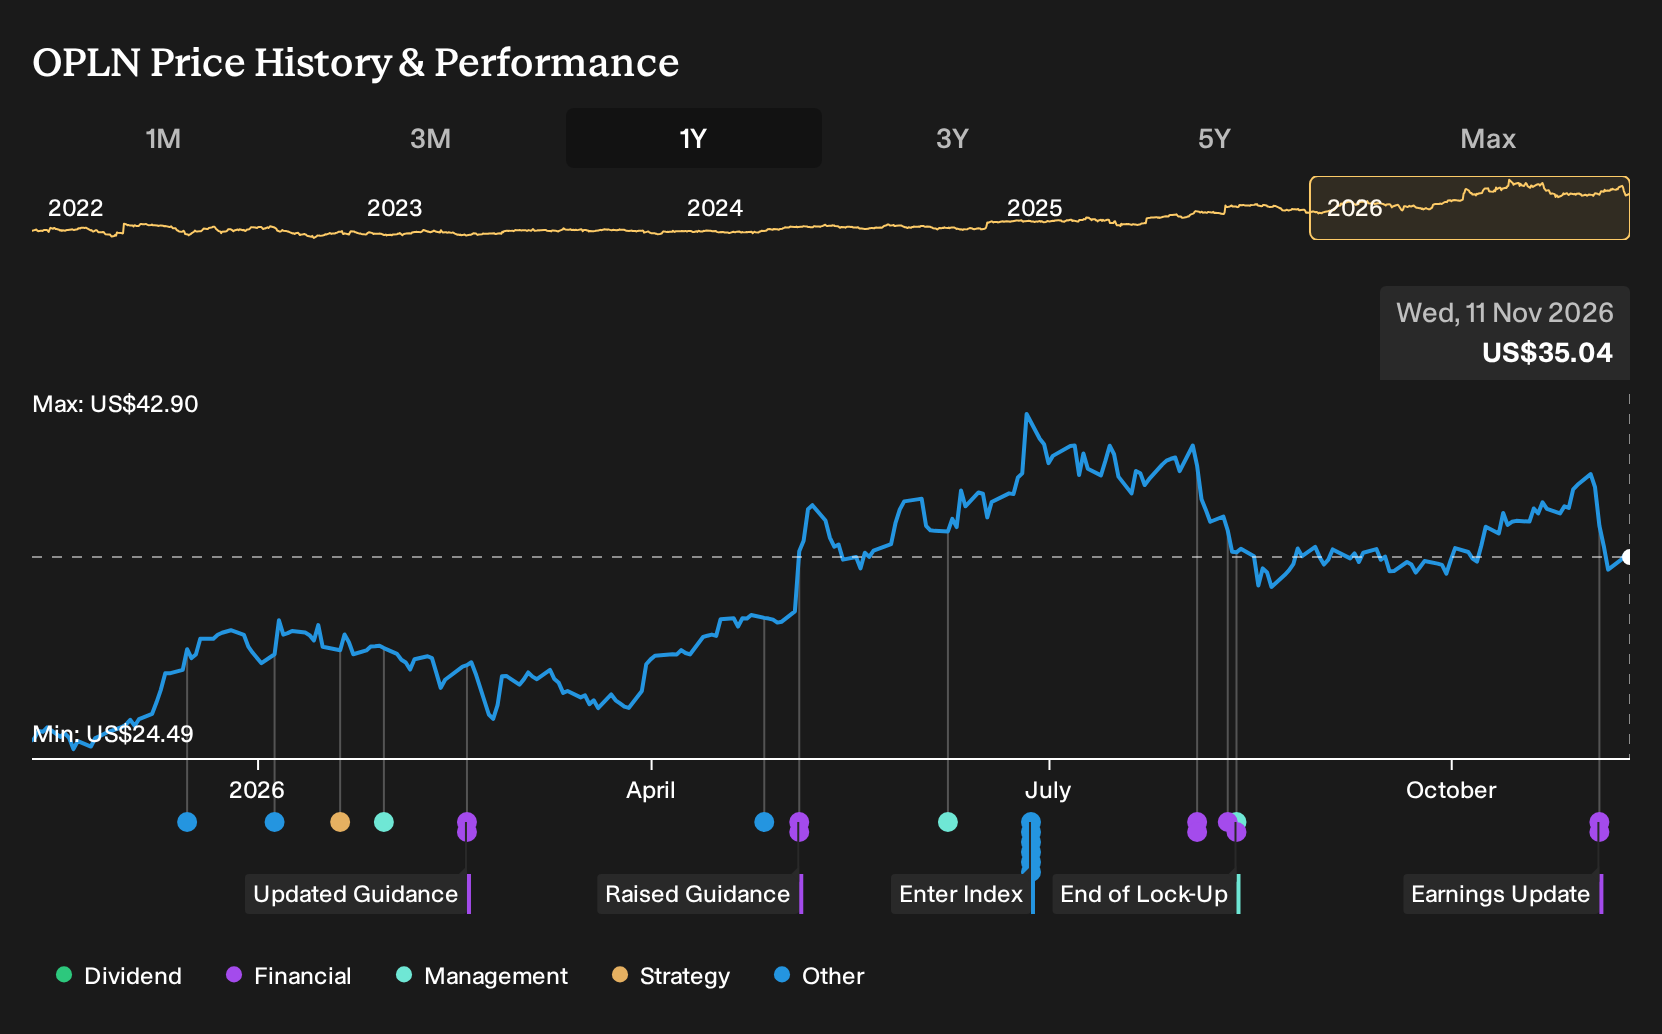
- OPENLANE reported third quarter 2026 sales of US$114.7 million and revenue of US$561.2 million, with diluted EPS from continuing operations at US$0.36. The company also raised full year net income guidance to a range of US$169 million to US$177 million, with projected EPS of US$1.27 to US$1.34.
- The combination of higher year to date revenue and EPS from continuing operations, together with slightly tighter full year guidance, indicates that OPENLANE's digital marketplace model is currently converting transaction volume and operating efficiency into more predictable earnings.
- The next step is to examine how OPENLANE's higher full year earnings guidance may reshape the investment narrative around its digital marketplace.
OPENLANE Investment Narrative Recap
To hold OPENLANE, you need to believe its digital marketplace can keep turning higher transaction volume into consistent earnings, even as competition and transport costs stay tough. The third quarter snapshot, with higher revenue and EPS from continuing operations, supports that thesis by showing the model working through current conditions.
The most important near term catalyst is continued migration from physical to online auctions and deeper use of AFC financing by enrolled dealers. The biggest risk is still execution while carrying meaningful debt, since interest payments are not well covered by earnings and added go to market spend could cap margin progress.
The raised full year 2026 net income and EPS guidance is the announcement that matters most for this story. Management now expects US$169 million to US$177 million of net income and diluted EPS of US$1.27 to US$1.34, a modest step up from prior guidance that tightens the range around current performance.
That revision ties directly into the analyst consensus narrative on Simply Wall St, which highlights operating leverage in the digital model as a key catalyst. Higher guidance puts more attention on whether OPENLANE can absorb extra second half 2026 operating and transport expenses without stalling margin improvement or stressing already thin interest coverage.
OPENLANE's narrative projects US$2.7b revenue and US$796.6 million earnings by 2029. This is based on an assumption of 8.7% yearly revenue growth and a move from a loss of US$63.9 million today to earnings of US$796.6 million in 2029, which is an earnings increase of about US$860 million.
Discover why OPENLANE's fair value suggests a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$46 to US$112 per share, which suggests some retail investors see OPENLANE as heavily undervalued while others set a much richer bar. Those opinions sit beside fresh catalysts such as raised 2026 guidance and elevated options volatility, so you can weigh sharply different narratives.
Explore another OPENLANE fair value estimate, including one that suggests as much as 219% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OPENLANE research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OPENLANE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OPENLANE's overall financial health at a glance.
Looking for more investment ideas beyond OPENLANE?
Once you have a view on OPENLANE, it can help to set it beside a broader watchlist so you can compare quality, valuation, and risk in one place. The Simply Wall St Screener is built for that kind of side by side work.
- If you want income stability at the portfolio level, you can scan for companies with stronger yield profiles using 6 dividend fortresses.
- For investors who care most about balance sheet strength and fundamentals, you can filter for resilient businesses through the list of solid balance sheet and fundamentals (23 results).
- If you are looking for potential future leaders that are not widely followed yet, you can broaden your opportunity set with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com