
Argan Stock Gains Attention After Earnings Beat And New Dividend
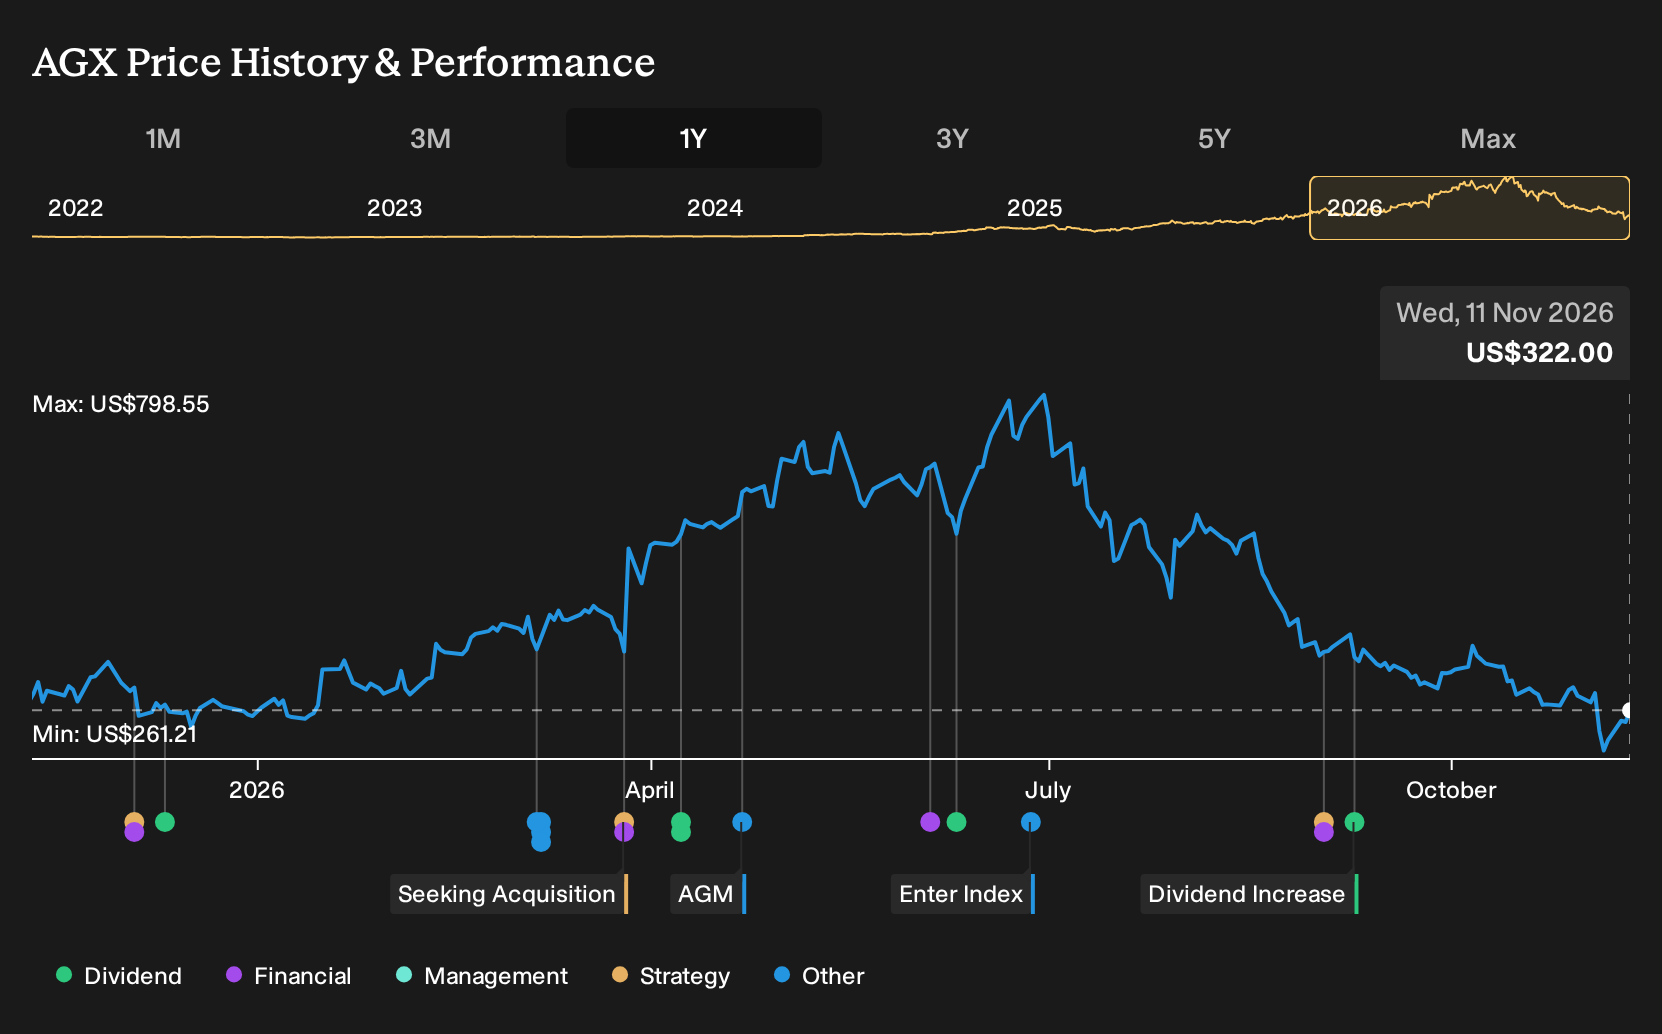
- Argan reported fiscal second quarter 2027 results that featured higher revenue, stronger net income, improved project execution and the announcement of a new US$0.50 quarterly cash dividend per share, supported by a balance sheet with no debt.
- The new dividend introduces a regular cash commitment that now depends on Argan converting its robust project demand into consistent earnings and cash generation, despite uncertain project timing and variable margins.
- We will now look at how Argan's stronger quarterly earnings and fresh dividend policy could reshape the wider investment narrative investors track.
Scan beyond Argan’s fresh dividend and project pipeline by comparing it with a hand picked list of solid balance sheet and fundamentals (23 results).
Argan Investment Narrative Recap
To own Argan, you need to be comfortable with a project driven contractor whose fortunes are closely tied to winning and executing large power projects. The recent quarter showed stronger earnings and better execution, which supports that thesis in the near term. According to MarkoVT, an investor in the Simply Wall St Community, the real swing factor remains how quickly new work replaces completed jobs.
That makes backlog replenishment the key short term catalyst and timing the biggest operational risk. The new quarter does not remove that concern. It simply buys more time for management to turn visible demand into awarded contracts that sustain revenue, margins and cash flow.
The most relevant new development is Argan’s US$0.50 quarterly cash dividend per share. This moves the business from an occasional distributor of cash to a recurring payer whose commitments now rely more heavily on consistent earnings and cash conversion. For investors, that dividend is only as resilient as future project awards and execution quality.
MarkoVT highlights that project concentration and uncertain award timing already sit high on the risk list. Layering a recurring payout onto that profile raises the stakes on capital allocation and contract discipline. The upside is clearer capital return, while the constraint is that missteps in project selection or delays could pressure the flexibility that a debt free balance sheet currently provides.
In MarkoVT’s narrative, Argan’s fair value of US$266.82 reflects a blend of 19.2% annual revenue growth and a 13.9% future profit margin, paired with a forward P/E range of 20.05x to 24.68x, and a 15% discount rate to balance growth assumptions against project risk.
Uncover why Argan's fair value indicates a 17% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One bullish twist on Argan focuses less on backlog risk and more on how fast new work could scale earnings. The most optimistic analysts were penciling in revenue of about US$2.5b and earnings of US$301.8m by 2029 before this dividend news. That is a very different story, so it is worth comparing several viewpoints yourself.
Explore 4 other Argan fair value estimates, including one that suggests potential upside of up to 77% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Argan research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Argan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Argan's overall financial health at a glance.
Looking for more investment ideas beyond Argan?
Argan may fit your thesis, but your portfolio benefits when you compare it with other companies that share strong financial traits or offer different return profiles.
- If you want potential mispriced opportunities with quality fundamentals, scan a curated set of 32 high quality undervalued stocks that combine solid balance sheets with attractive valuations.
- For investors who care most about income resilience, focus on companies with robust payouts by reviewing a targeted group of 6 dividend fortresses that aim to balance yield with financial strength.
- To keep risk in check while still hunting for upside, filter for sturdier balance sheets and steadier metrics using a 30 resilient stocks with low risk scores that screens for resilience first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com