
Dear Amazon Stock Fans, Mark Your Calendars for November 19
It has been a rough ride for artificial intelligence (AI) stocks lately, and e-commerce giant Amazon (AMZN) has hardly been spared. The company’s aggressive spending on AI infrastructure has weighed on investor sentiment, with Wall Street increasingly eager to see when these massive investments will translate into meaningful returns. However, the clouds hanging over the stock may finally be beginning to clear, as renewed analyst confidence and a string of product announcements breathe fresh life into Amazon’s growth story.
On Tuesday, Amazon made a bold move into robotics, launching a new security business featuring two autonomous products: a flying indoor camera for homes and a mobile security robot for businesses. The move takes Amazon beyond its traditional home-security offerings and signals bigger ambitions in the robotics market. Investors welcomed the announcement, sending shares up approximately 1.5% on Tuesday. But robotics wasn't the only headline grabbing attention.
Amazon also unveiled plans for its 2026 holiday shopping blitz, announcing that Black Friday Week and Cyber Monday deals will run from Nov. 19 through Nov. 30. The 12-day event will feature millions of offers across electronics, home goods, apparel, beauty, and toys, alongside grocery promotions, personalized shopping tools, and live sports programming. In fact, this year's campaign promises even more shopping excitement, with daily themed deals spanning technology, fashion, and premium gifts.
For the first time, Amazon will drop deals twice on both Black Friday and Cyber Monday, at midnight and 8 a.m. Pacific time, with select discounts reaching up to 60%. With new robotics ambitions and the crucial holiday shopping season on the horizon, Amazon is giving investors plenty to watch. Can these catalysts help turn the tide for AMZN stock? Let's take a closer look.
About Amazon Stock
From changing the way people shop to powering businesses and the broader digital economy, Amazon has built an empire that stretches well beyond e-commerce. Headquartered in Seattle, the technology giant operates across online retail, third-party seller services, digital advertising, subscriptions, cloud computing, and artificial intelligence. Its extensive portfolio includes the flagship Amazon marketplace, Prime memberships, Prime Video, Kindle, Alexa, and an expanding range of AI-powered services.
Amazon's vast business empire is divided into three primary segments: North America, International, and Amazon Web Services (AWS). While its North American and International divisions drive retail, advertising, and subscription revenue across global markets, AWS provides businesses, governments, and developers with cloud computing, data storage, database management, and AI solutions.
Backed by an extensive global footprint, a sprawling fulfillment and logistics network, and an expanding cloud infrastructure business, Amazon has transformed itself from an online retailer into a diversified technology powerhouse. Yet, even a company of Amazon's scale hasn't been immune to Wall Street's changing sentiment.
Despite its dominant position across multiple industries and a market capitalization of approximately $2.93 trillion, AMZN shares have faced pressure as investors weigh the company's aggressive AI spending against the potential returns. Concerns over how quickly these massive investments will translate into meaningful profits have kept sentiment in check. However, a series of recent developments appears to be giving the stock fresh momentum.
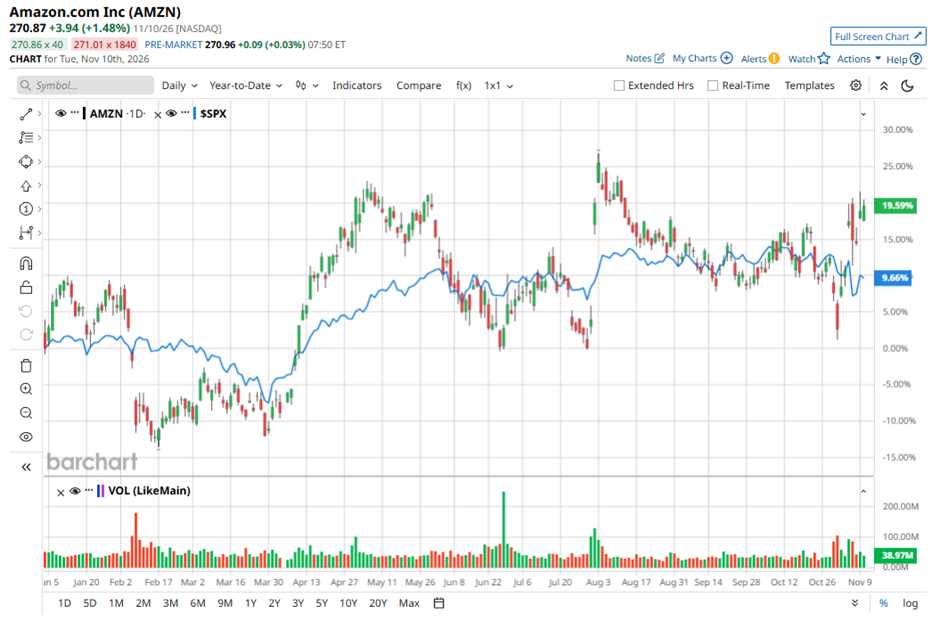
Amazon has gained 9.1% over the past year, slightly trailing the S&P 500 Index ($SPX), which has advanced 10.1% over the same period. The picture looks considerably brighter in 2026, with AMZN now up 17.4%, comfortably ahead of the broader market's 9.9% gain. More recently, the stock has picked up steam, surging 8.1% over the past five trading sessions, while the S&P 500 has slipped marginally. The latest rally suggests that investors may be warming up to Amazon's growth prospects once again.
A Closer Look At Amazon’s Q3 Earnings Report
Amazon's fiscal 2026 third-quarter earnings, released on Oct. 29, offered investors a mixed picture, with its massive AI ambitions increasingly becoming a double-edged sword. Despite continued strength in its cloud business, the company fell short of Wall Street's expectations on both revenue and earnings, sending shares down 1.4% in the following trading session. Slower retail growth, mounting infrastructure costs, and a weaker-than-expected bottom line added to concerns over how quickly Amazon's aggressive investments will begin delivering returns.
On the revenue front, Amazon generated $201.9 billion in net sales, up 12% from $180.2 billion in the same quarter last year. Adjusting for the unfavorable $0.9 billion impact of foreign exchange movements, revenue growth would have been 13%. However, the result still came in slightly below analysts' consensus estimate of $202.3 billion. The biggest bright spot was Amazon Web Services (AWS), which continued to demonstrate why it remains central to the company's growth story.
AWS revenue jumped 39% year-over-year to $46 billion, marking its strongest growth rate in nearly five years. The acceleration highlights booming enterprise demand for AI infrastructure and cloud services, further supported by an expanding backlog worth hundreds of billions of dollars. However, Amazon's retail operations, which account for the largest share of its revenue, delivered a more modest performance.
North America segment sales grew 6% year-over-year to $112.9 billion, while International revenue increased 5% to $43.1 billion. Earnings offered little relief either. Amazon reported earnings per share (EPS) of $1.89, down from $1.95 in the year-ago quarter and below Wall Street's estimate of $1.96. Perhaps the biggest concern was the mounting cost of keeping Amazon's AI ambitions on track.
Its aggressive infrastructure spending is beginning to weigh heavily on cash generation. Trailing-12-month free cash flow swung to an outflow of $42.4 billion, compared with an inflow of $14.8 billion for the 12 months ended Sept. 30, 2025. The sharp deterioration was largely driven by a $94.8 billion year-over-year increase in purchases of property and equipment, net of proceeds from sales and incentives, reflecting the company's substantial investments in AI infrastructure.
The scale of Amazon's spending spree is particularly striking. Capital expenditures reached $77.3 billion during the quarter, more than twice the $35.1 billion recorded in the same period last year. And there is little indication that management plans to ease off the accelerator. Amazon maintained its forecast for approximately $220 billion in cash capital expenditures for full-year 2026, underscoring the scale of its commitment to expanding AI and cloud infrastructure.
Still, Amazon offered investors a more encouraging outlook for the all-important holiday quarter. Management expects fourth-quarter net sales to land between $240 billion and $247 billion, representing year-over-year growth of 12% to 16%. The forecast includes an approximately 60-basis-point headwind from unfavorable foreign exchange movements. On the profitability front, operating income is projected to range from $28.5 billion to $33.5 billion, compared with $25 billion in the fourth quarter of 2025.
What Do Analysts Think About Amazon Stock?
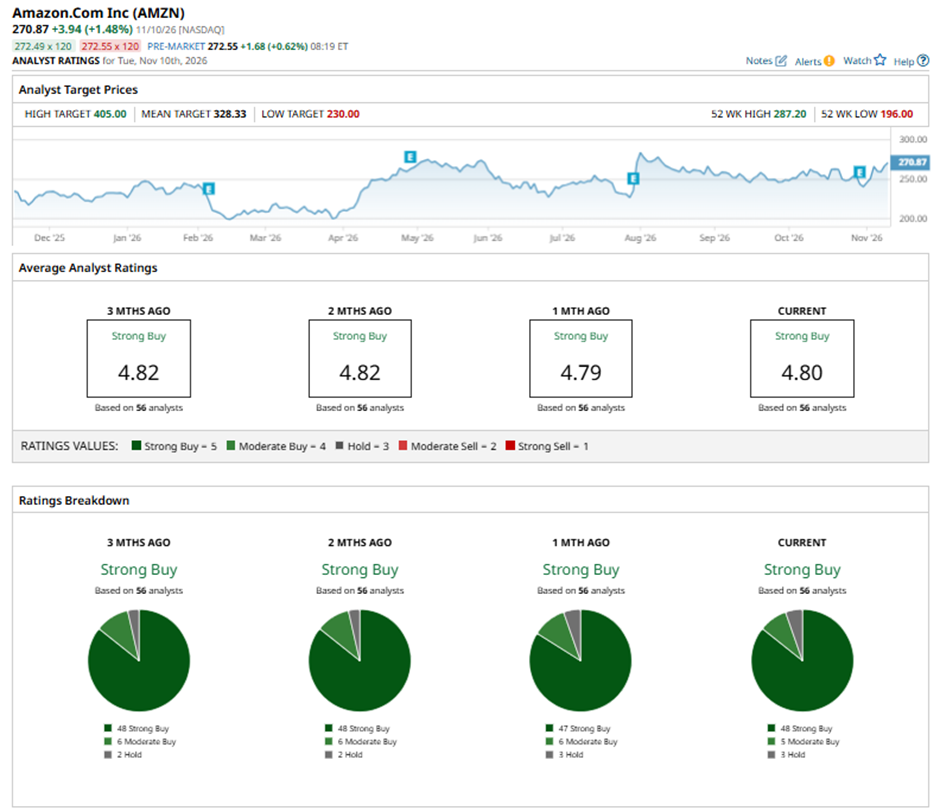
Wall Street's bullish stance on Amazon remains firmly intact, with the stock commanding a consensus “Strong Buy” rating. Among the 56 analysts covering the company, 48 recommend a “Strong Buy,” five assign a “Moderate Buy” rating, and three advise “Hold.” The average price target of $328.33 suggests potential upside of about 21.2%, while the Street-high target of $405 signals a possible 50% gain from current levels.
On the date of publication, Anushka Mukherji did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.