
How Investors Are Reacting To Omega Healthcare Investors Stock After Mixed Quarterly Results
- Omega Healthcare Investors reported third quarter 2026 results with revenue of US$340.55 million and net income of US$83.09 million, alongside nine month revenue of US$991.76 million and net income of US$596.96 million. These figures reflect different earnings trends over the shorter and longer periods.
- The contrast between softer quarterly earnings per share and higher year to date profit highlights how Omega Healthcare Investors' portfolio actions and operator mix can affect reported performance over different time frames.
- We will now look at how Omega Healthcare Investors' earnings softness in the latest quarter may reshape the broader investment narrative.
Compare the earnings profile of Omega Healthcare Investors with its peers by scanning our hand picked list of 6 dividend fortresses for income ideas that share a similar focus on steady cash generation.
Omega Healthcare Investors Investment Narrative Recap
To own Omega Healthcare Investors, you need to be comfortable with a long term skilled nursing and senior housing story, backed by contracted rent and a concentrated operator base. The analyst consensus Narrative on Simply Wall St still hinges on capital recycling and operator health. The latest quarter, with softer earnings per share despite higher revenue, does not fundamentally change that long running thesis by itself.
The short term swing factor remains how smoothly Omega Healthcare Investors can re lease or reposition assets while keeping rent coverage stable. The biggest near term risk is still tenant or operator stress that affects collections, especially with reliance on a smaller group of operators and ongoing use of straight line rent accounting.
The most relevant recent update is the third quarter 2026 report itself, which showed revenue of US$340.55 million and net income of US$83.09 million, alongside basic EPS from continuing operations of US$0.27. Those figures sit against nine month net income of US$596.96 million and basic EPS of US$1.94. Taken together, they provide two very different snapshots of earnings power.
For catalysts, that mix matters. In the short term, investors watching Omega Healthcare Investors are likely to focus on whether management can keep translating higher reported revenue into sustainable cash generation, given the ongoing capital recycling and one off items flagged in prior analyses. Any sign that rent collections and redeployments track expectations would ease concern around the earnings volatility visible in this quarter.
Omega Healthcare Investors' narrative projects US$1.2b revenue and US$688.2 million earnings by 2029. This assumes revenue declining by 1.5% per year and an earnings decrease of US$153.8 million from US$842.0 million today.
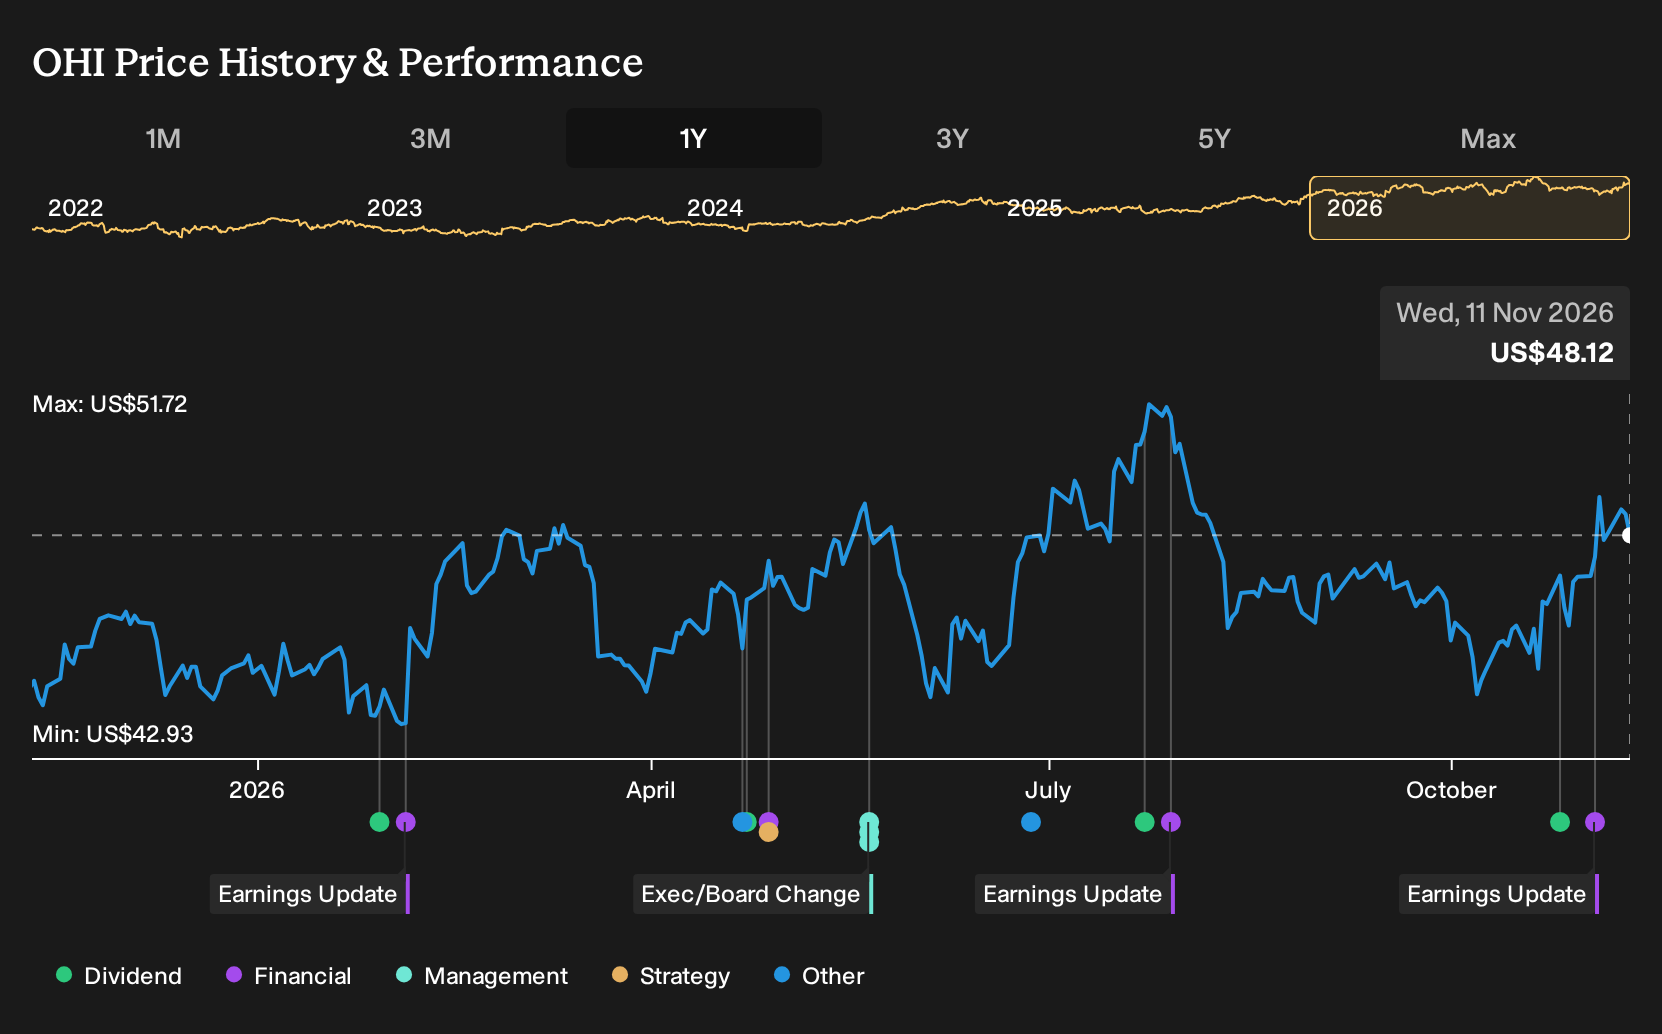
Uncover why Omega Healthcare Investors' fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$51.89 to US$96.26, which is a wide bracket for a single stock like Omega Healthcare Investors. That spread sits alongside risks around tenant concentration and capital recycling, so you are seeing sharply different views that are worth comparing directly.
Explore another Omega Healthcare Investors fair value estimate, including one that suggests as much as 100% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your Omega Healthcare Investors research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Omega Healthcare Investors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omega Healthcare Investors' overall financial health at a glance.
Looking for more Omega Healthcare Investors style ideas?
If Omega Healthcare Investors appeals because of its income profile and real asset backing, it can be useful to line it up against other potential holdings that share some of those traits but with different risk and balance sheet setups.
- For investors who want current income without ignoring balance sheet strength, scan a curated 6 dividend fortresses that aim to combine yield with staying power.
- If downside resilience matters most, focus on stability and financial robustness using a 30 resilient stocks with low risk scores that filters for companies with lower risk scores and steadier fundamentals.
- To broaden the watchlist beyond widely followed tickers, look through a 19 high quality undiscovered gems that pair solid business metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com