
Archrock (AROC) Stock May Still Look Like A Bargain Following The HiVolt Deal
Archrock has delivered a very large 5 year share price gain, which naturally raises a blunt question for anyone looking at the stock today. Is the current price still supported by what the business earns, or has the recent enthusiasm run ahead of its earnings power?
- Archrock shares are up about 316.6% over 5 years, putting real pressure on the question of whether the current valuation can still be explained by its earnings profile.
- The planned purchase of HiVolt Energy Holdings for up to US$450 million may support expectations for broader earnings streams and different capital needs as Archrock expands beyond compression into microgrid power solutions.
- The analysts covering Archrock have run their own numbers. See what analysts think Archrock's shares could be worth.
The issue now is whether Archrock's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want a wider watchlist of energy infrastructure plays to research alongside Archrock, a focused screen of 42 power grid technology and infrastructure stocks may be useful.
Is Archrock Still Cheap on Earnings?
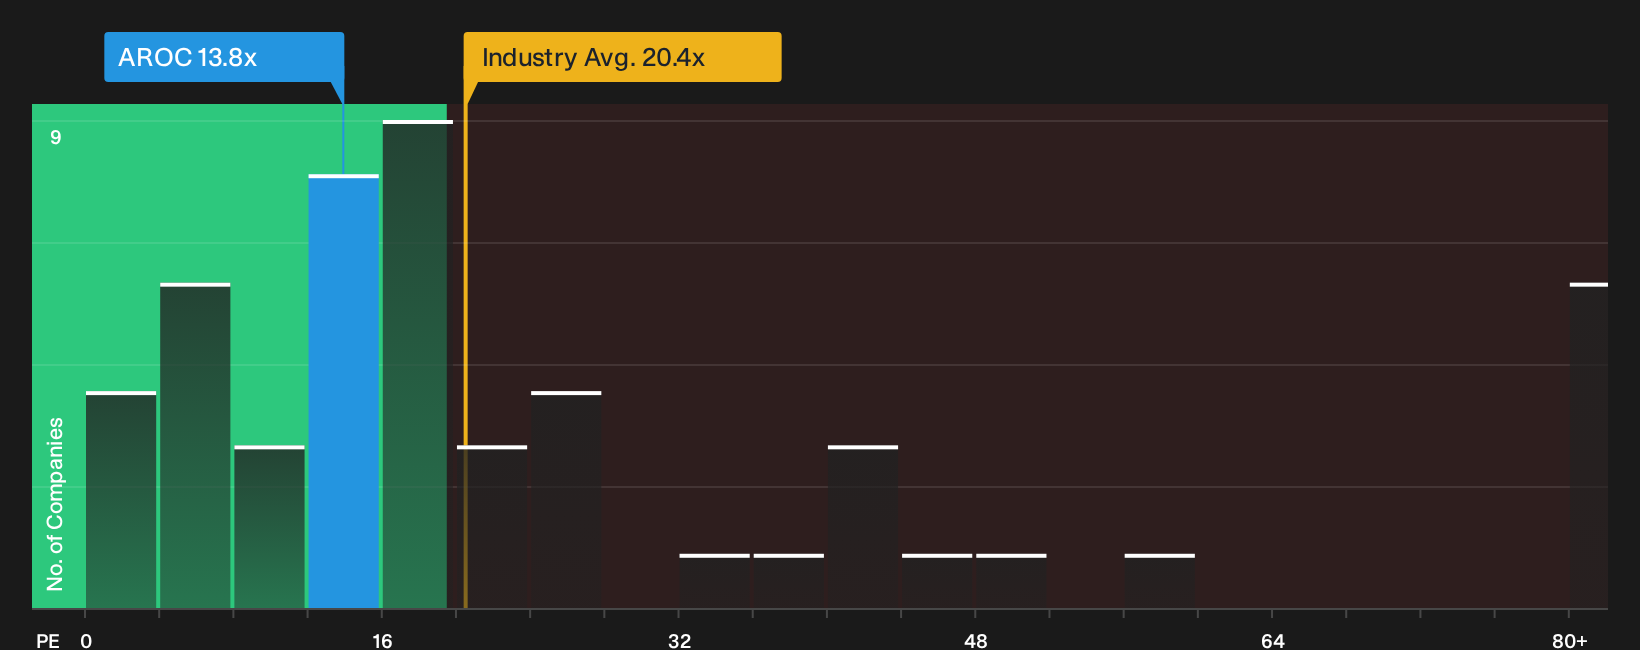
The P/E ratio is a useful way to see what you are paying today for each dollar of Archrock earnings. On this measure, Archrock trades on about 13.8x, which is well below the wider Energy Services sector average of roughly 20.4x and also under the peer group level near 26.8x.
Because the Fair Ratio benchmark suggests a higher multiple would usually fit Archrock's mix of growth profile, profitability and risk, the current P/E indicates that the stock may be undervalued on this framework. Despite the planned HiVolt acquisition giving Archrock a broader power and compression platform, the present earnings multiple still prices the shares at a discount to both the industry and direct peers. This valuation profile is where investors focused on valuation metrics may want to look more closely. Explore the numbers behind Archrock's P/E valuation.
The Archrock Narrative: What Would Justify Today's Price?
Narratives for Archrock pick up where the P/E puzzle leaves off and explain which paths for Archrock's future margins, earnings and growth would need to play out for the current share price to look materially higher or lower. They appear on Simply Wall St's Community page and turn a single valuation output into a set of concrete assumptions that you can watch over time to see whether the story behind that number is holding up.
One of the top community narratives on Archrock: 41% undervalued
According to Composite_Research, an investor in the Simply Wall St Community, Archrock is being framed as a critical link between AI data centers and natural gas infrastructure.
"All these 'behind-the-meter' production processes create an absolute need for site-specific gas compression infrastructure so that the gas from the pipeline can be fed…"
Discover why this Narrative puts Archrock at 41% undervalued.
One more Archrock check that belongs beside the earnings multiple
The last missing piece is who is steering Archrock and how their pay packets line up with your interests as a shareholder. This is a separate lens that can change how you read every valuation metric. See who runs Archrock and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com