
What Are Wall Street Analysts' Target Price for UDR Stock?
With a market cap of $11.6 billion, UDR, Inc. (UDR) is a leading real estate investment trust (REIT) that owns, operates, acquires, develops, and manages multifamily apartment communities across major residential markets in the United States. Headquartered in Highlands Ranch, Colorado, the company focuses on providing rental housing in high-demand metropolitan areas, including coastal markets and major Sun Belt cities.
Shares of the company have underperformed the broader market over the past 52 weeks. UDR stock has soared 4.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 11.3%. Moreover, shares of the company have declined 1.6% over the past six months, compared to SPX’s 2.8% gain.
Zooming in further, shares of UDR have lagged behind the State Street Real Estate Select Sector SPDR ETF’s (XLRE) 6.9% return over the past 52 weeks.
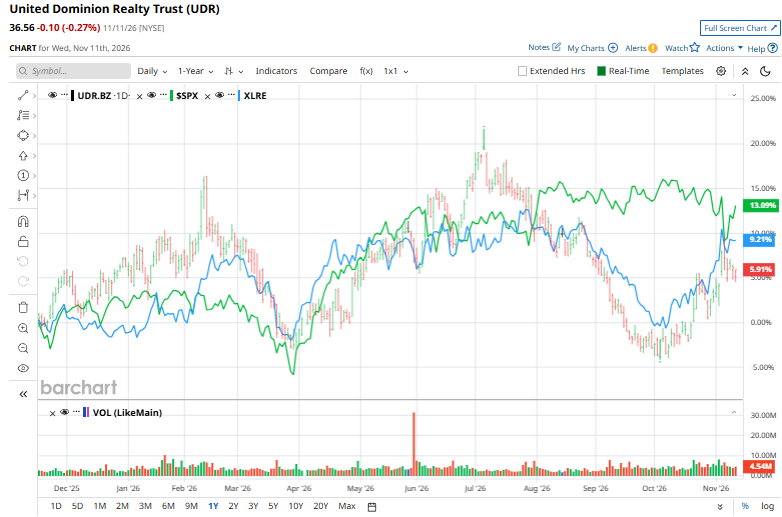
On Nov. 2, UDR reported third-quarter earnings, and its shares popped 1.1%. It posted total revenue of $428.08 million, down marginally from $431.86 million in Q3 2025. Rental revenue declined approximately 1.1% to $424.58 million, reflecting the impact of property sales, partially offset by contributions from same-store and acquired communities.
Net income attributable to common stockholders increased to $214.9 million, or $0.67 per diluted share, compared with $39.2 million, or $0.12 per share, a year earlier. The substantial increase was primarily driven by $190.1 million in gains from real estate sales. Meanwhile, FFO per diluted share remained unchanged at $0.62, while FFOA per diluted share was also flat at $0.65, exceeding the consensus estimate of $0.64. Operationally, same-store revenue increased 1.8% year-over-year, while operating expenses rose 2.2%, resulting in a 1.6% increase in same-store NOI.
During the quarter, UDR completed a strategic $2 billion joint venture with Apollo, contributing 19 apartment communities comprising 7,059 homes. The transaction provided $1.34 billion in equity capital, strengthened the company's balance sheet, reduced leverage, and allowed UDR to retain approximately one-third ownership in the portfolio while continuing to manage the properties. The company also continued its portfolio optimization strategy through property dispositions, joint venture expansions, and share repurchases.
For the fiscal year ending in December 2026, analysts expect UDR’s FFOA to remain flat to $2.54 per share. However, the company’s earnings surprise history is promising. It beat or met the consensus estimates in the last four quarters.
Among the 23 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on nine “Strong Buy” ratings, 12 “Holds,” and two “Strong Sells.”
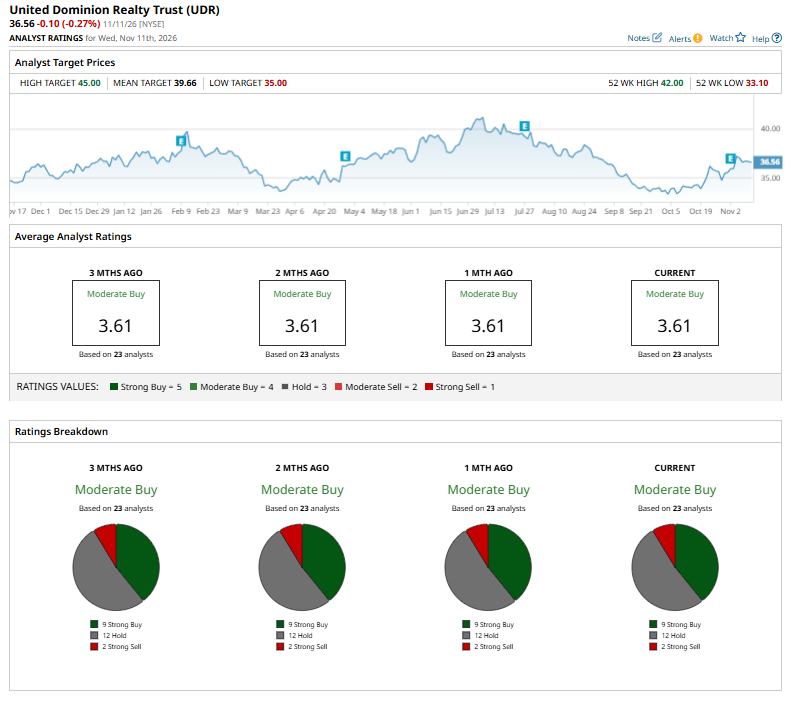
On October 19, Morgan Stanley maintained its “Equal-Weight” rating on UDR while lowering its price target to $41 from $42, indicating a slightly more cautious valuation outlook.
The mean price target of $39.66 represents a 8.5% premium to UDR’s current price levels. The Street-high price target of $45 suggests a 23.1% potential upside.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.