
How Raised Guidance Will Impact Middleby (MIDD) Investors
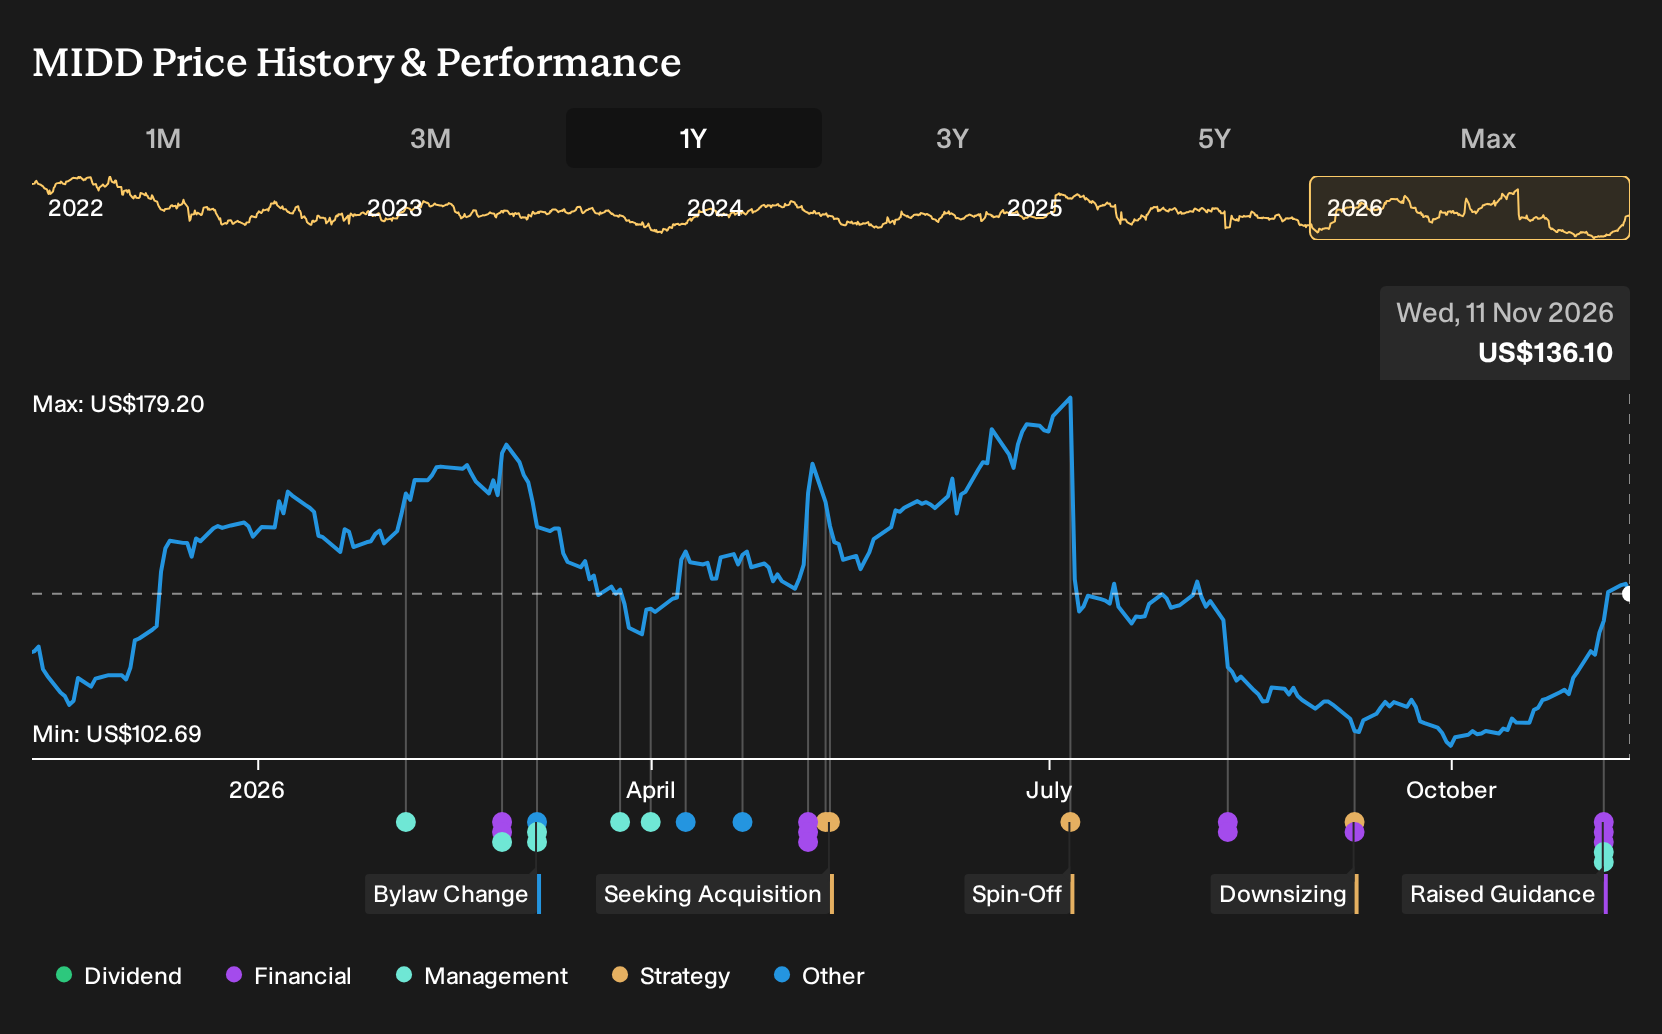
- Middleby raised its full year 2026 revenue guidance to US$2.519b to US$2.534b, reported third quarter sales of US$652.58m with weaker profitability, and outlined a CEO transition from Timothy J. FitzGerald to current Chief Commercial Officer Steven P. Spittle in early 2027.
- The combination of higher revenue guidance, mixed earnings that include a small third quarter net loss, and a planned leadership handover gives investors fresh information on how Middleby is balancing growth ambitions with profitability and succession planning.
- We will now look at how Middleby's higher full year revenue guidance might reshape the existing investment narrative for the business.
Middleby Investment Narrative Recap
To own Middleby, you need to believe the commercial foodservice focus can translate into steadier earnings as operational programs and portfolio simplification play through. The raised 2026 revenue guidance and new fourth quarter sales range support the idea that demand is holding, even as the third quarter loss highlights near term pressure on profitability.
The analyst consensus Narrative on Simply Wall St leans heavily on margin expansion from Ice & Beverage, automation and cost work. That remains the key short term catalyst. The biggest current risk is that lower margin platforms and cost inflation keep squeezing EBITDA just as the business invests and prepares for the CEO transition.
The planned CEO handover to Steven Spittle from April 2027 is the announcement that ties closest to these catalysts. He has been closely involved with commercial execution, large quick service customers and major brands like Pitco and Blodgett. This experience sits directly on top of the operational excellence and beverage automation themes analysts focus on.
For you, the question is whether this leadership change supports consistent execution on the lean program, the brewing exit and the ramp of Ice & Beverage and aftermarket service. Any slip in rollout pace, pricing discipline or capital allocation around these projects could slow the margin uplift that many investors are watching most closely.
Middleby's narrative projects US$2.8b revenue and US$360.7m earnings by 2029, based on analyst assumptions of revenue declining 5.8% per year and earnings rising by about US$40.7m from US$320.0m today.
Uncover why Middleby's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Middleby’s aftermarket service build out as the real swing factor rather than Ice & Beverage. Before this guidance, that group was modeling about US$2.7b revenue and US$407.4m earnings by 2029, well above consensus. Those views were set before the latest outlook, so you may see them shift as fresh information beds in.
Explore another Middleby fair value estimate, including one that suggests there could be as much as 15% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Middleby research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Middleby. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Middleby's overall financial health at a glance.
Looking for more investment ideas beyond Middleby?
Once you have a view on Middleby, it can help to cross check that thinking against other businesses with different balance sheet strength, income profiles and risk levels. The Simply Wall St Screener lets you filter quickly so you spend more time judging quality and less time trawling through tickers.
- If capital preservation sits high on your list, consider a curated set of relatively resilient companies by scanning the 30 resilient stocks with low risk scores that may better suit a steadier risk profile.
- For investors who care most about financial quality and valuation, sift through a focused collection of stronger balance sheets and fundamentals via the list of solid balance sheet and fundamentals (23 results) that can complement your Middleby work.
- If you are hunting for underfollowed opportunities, broaden your watchlist with a group of lesser known businesses that still show solid fundamentals using the 19 high quality undiscovered gems to round out your research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com