
TTM Technologies (TTMI) Rides AI And Defense Demand As Valuation Questions Return
Fresh earnings have put TTM Technologies (TTMI) in focus after the printed circuit board maker reported Q3 2026 revenue up 60% year over year and a record adjusted EBITDA margin.
That earnings surprise landed after a rough stretch for TTM Technologies, with the 30 day share price return down 28.67% and the 90 day move down 43.33%. This comes even though the year to date share price return sits at 11.46% and the 1 year total shareholder return is 11.63%, capped by a very large 3 year total shareholder return above 7x that hints at strong long term momentum. Shorter term sentiment has recently swung negative and then snapped back with an 8.96% 1 day share price jump around the Q3 release.
Scan beyond TTM Technologies and line up other potential beneficiaries of the same AI and electronics cycle with our hand picked 53 AI infrastructure stocks today.
For TTM Technologies, the question now is whether that sharp pullback and sudden rebound mostly reflect changing sentiment in the market or signal a reset toward what the underlying cash generation could justify next in terms of valuation.
Most Popular Narrative: 58% Undervalued
At a last close of $78.70 versus a narrative fair value of $185.80, the analyst consensus Narrative on Simply Wall St frames TTM Technologies as heavily discounted on its modeled future cash generation, with that view built on specific growth, margin and discount rate assumptions rather than sentiment alone.
Global capacity investments of more than US$1.2b through 2029 in Syracuse Ultra HDI, Penang and multiple China expansions, together with initial European manufacturing footholds via Swiss Technology Group and ILFA, position TTM Technologies to support reshoring, AI and regional defense demand and to scale future revenue. Penang’s progress toward breakeven helps protect margins.
See why 50 investors see TTM Technologies as 58% undervalued.
Result: Fair Value of $185.8 (UNDERVALUED)
Still, that story can crack if the US$1.1b Epiq deal keeps leverage elevated or if the large AI data center build plans fall short.
Find out about the key risks to this TTM Technologies narrative.
Another View: What TTM Technologies' P/E Is Really Saying
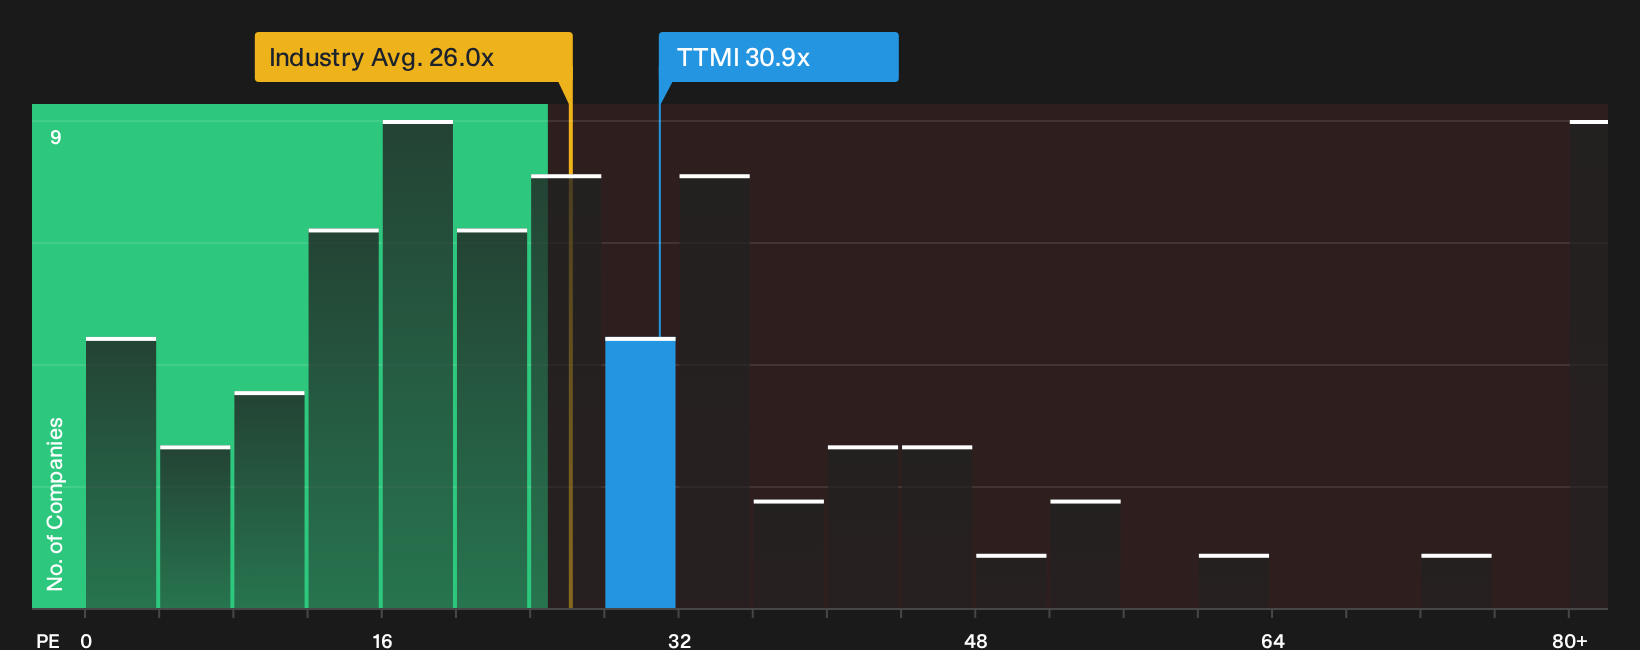
There is a very different message coming from plain P/E math. TTM Technologies trades on 30.9x earnings, richer than the US Electronic industry at 26x, yet below both its peer average of 38.1x and an estimated fair ratio of 56.7x that the market could move toward. That mix of premium sector pricing and discount versus peers and the fair ratio points to real valuation risk if sentiment cools, but also room for re rating if earnings delivery keeps investor confidence intact, so which side of that tradeoff feels closer to your own expectations?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed messages on TTM Technologies so far, and only you can decide which side carries more weight. Act while the data is fresh and stress test both sides of the story by reviewing 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TTM Technologies?
If you only stop at TTM Technologies, you could miss opportunities where quality, valuation and income potential line up even more cleanly across the wider market.
- Target resilient balance sheets and consistent fundamentals by scanning a list of solid balance sheet and fundamentals (23 results) that filters out weaker financial profiles.
- Focus on potential value opportunities by reviewing a 32 high quality undervalued stocks built around strong cash generation and healthier balance sheets.
- Strengthen your income stream by reviewing a curated 6 dividend fortresses focused on higher yielding businesses with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com