
Will Lowered Revenue Guidance Change Expro Stock Narrative
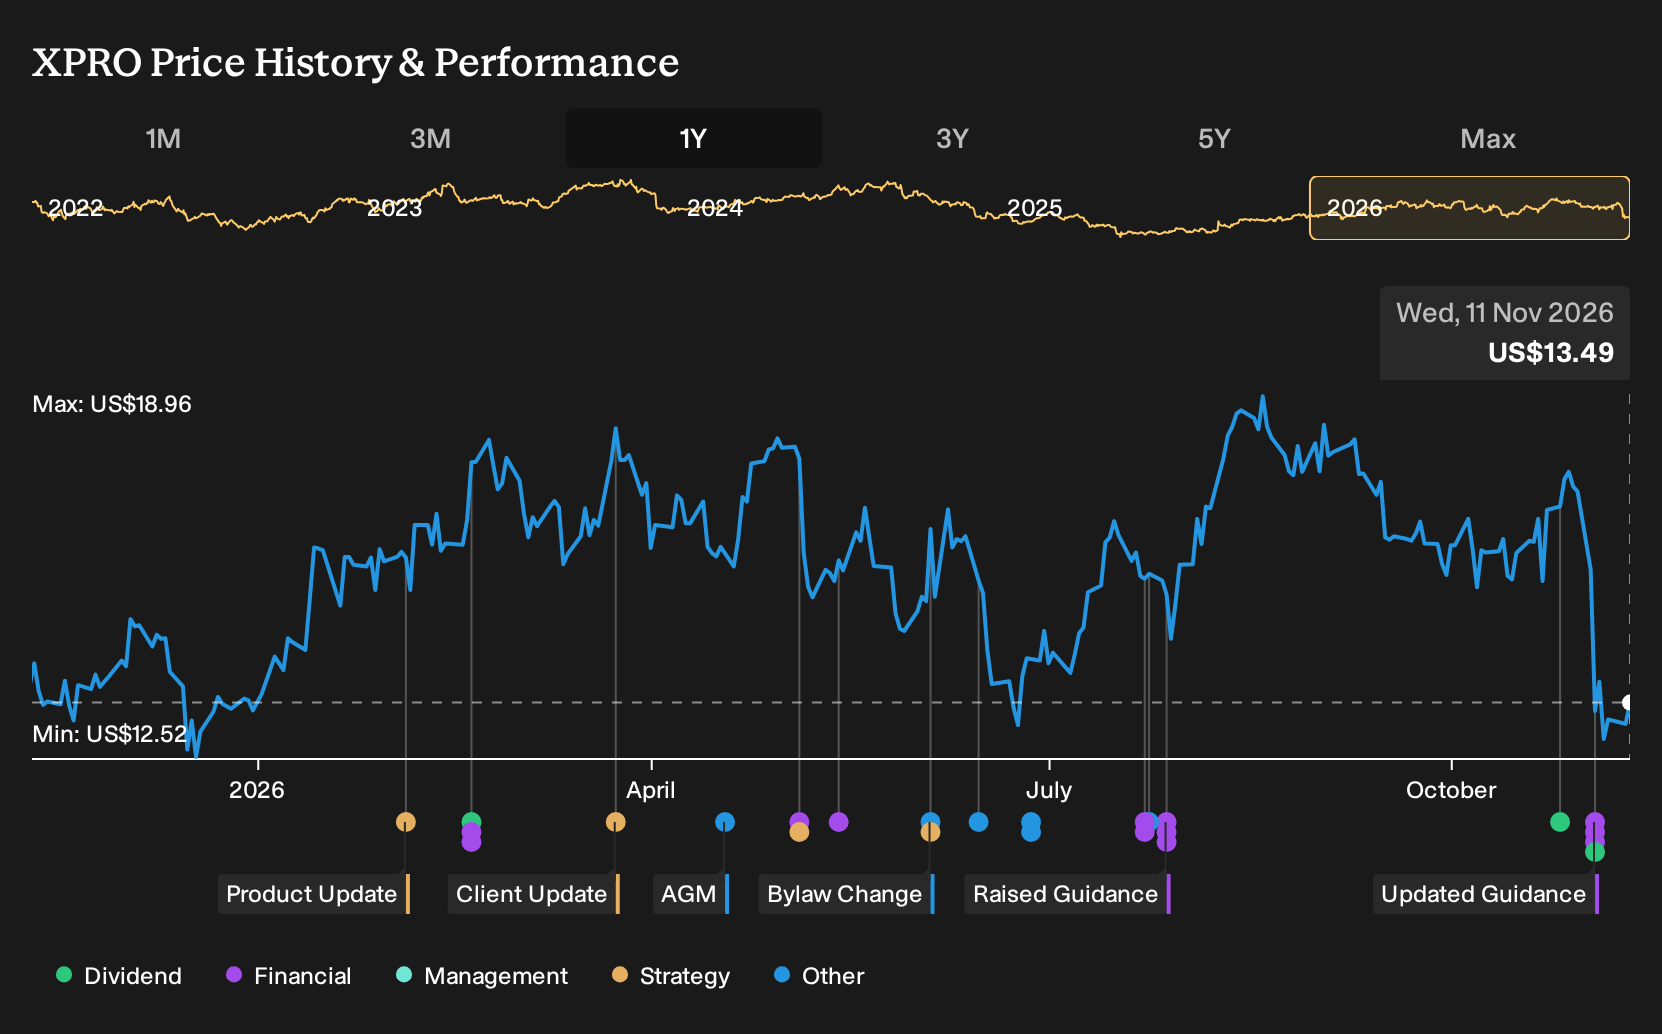
- Expro reported third quarter 2026 sales of US$439.94 million and a net loss of US$5.2 million, and modestly lowered full year 2026 revenue guidance to a US$1,660 million to US$1,680 million range, while also outlining fourth quarter revenue expectations of US$465 million to US$485 million.
- The business is combining weaker profitability with a US$100 million share repurchase program that has already retired 3,227,537 shares for US$52 million. This puts capital returns alongside margin pressure and mixed sales trends in the investment debate.
- We will now look at how Expro's investment narrative is affected by the net loss trend alongside the slightly reduced 2026 guidance.
Expro Investment Narrative Recap
To own Expro, you need to be comfortable with a story that leans heavily on offshore and international activity, and on improving margins from a low base. The analyst consensus Narrative on Simply Wall St frames execution on cost cuts, higher value services and acquired technologies as the key driver. The third quarter loss and softer full year guidance keep the main near term catalyst on execution of the Drive 25 margin program rather than on top line surprises.
The biggest current risk is that already thin profitability stays pressured while international work remains exposed to geopolitical issues and project timing. Lower profit margins versus last year and recent one off items reinforce that concern. The updated outlook does not radically change that balance. However, it keeps investor attention on cash conversion and project delivery into early 2027.
The share repurchase program of up to US$100 million, with US$52 million already deployed, is the announcement that most directly frames this news. Buybacks are running alongside a period of net losses and mixed revenue trends. As a result, your interpretation will likely hinge on how confident you are in Expro turning cost work into more durable earnings.
Completed repurchases of 3,227,537 shares, which is 2.85% of the share count, tighten the equity base at a time when analysts in the consensus Narrative still anchor on earnings growth and margin expansion as the main upside drivers. That keeps execution risk front and center, since returning capital while profitability is under pressure heightens the importance of delivering on project backlogs and cost savings.
Expro's narrative projects US$1.9b revenue and US$210.9 million earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of roughly US$209 million from US$1.6 million today.
Uncover why Expro's fair value indicates a 17% potential upside to its current price, which could narrow quickly if Expro delivers on its margin plans.
Exploring Other Perspectives
Bullish analysts focus on Expro’s capital returns as a catalyst. Before this guidance cut and fresh loss, the most optimistic forecasts already penciled in US$1.9b of revenue and US$185.1 million of earnings by 2029. You can see how those expectations paint a far more upbeat story that may now be retested as views adjust.
Explore 2 other Expro fair value estimates, including one that suggests as much as 248% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Expro research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Expro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Expro?
If the Expro story has sharpened your focus on guidance, profitability and capital returns, it can be useful to compare it with other opportunities filtered by clear, rules-based criteria. The Simply Wall St Screener lets you do that quickly without getting buried in noise.
- Prioritise financial resilience and balance sheet strength by reviewing companies that pass a list of solid balance sheet and fundamentals (23 results). This allows you to focus on businesses with sturdier foundations.
- Hunt for potential mispriced opportunities by scanning a 19 high quality undiscovered gems that highlights lesser-known stocks with fundamentals that may be stronger than their profiles suggest.
- If you prefer a calmer ride over big swings in price moves, focus on a 30 resilient stocks with low risk scores that filters for companies with more modest risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com