
AXT (AXTI) Stock Trades At A Premium After Its 21x Run
AXT, Inc. has delivered an exceptionally strong share price run in recent years, which naturally raises a simple question for you as an investor: Is the current price tag on AXT stock adequately grounded in the earnings power the business is generating today?
- Over the past 3 years, AXT shares have gained about 21x, so any view on the stock now rests heavily on how sustainable its profit engine proves to be.
- Record revenue tied to indium phosphide demand, along with a shift from loss making to meaningful profitability, can reshape how you think about the durability and timing of future cash flows.
- Your read on AXT is one view; the desks covering it have another. See what analysts think AXT's shares could be worth.
The issue now is whether the earnings of AXT at its latest close of US$46.97 are enough to justify that price when judged against a Fair Ratio benchmark.
If AXT has put indium phosphide in focus for you, it can be useful to compare that theme with 25 quantum computing stocks.
Has AXT Run Too Far on Earnings?
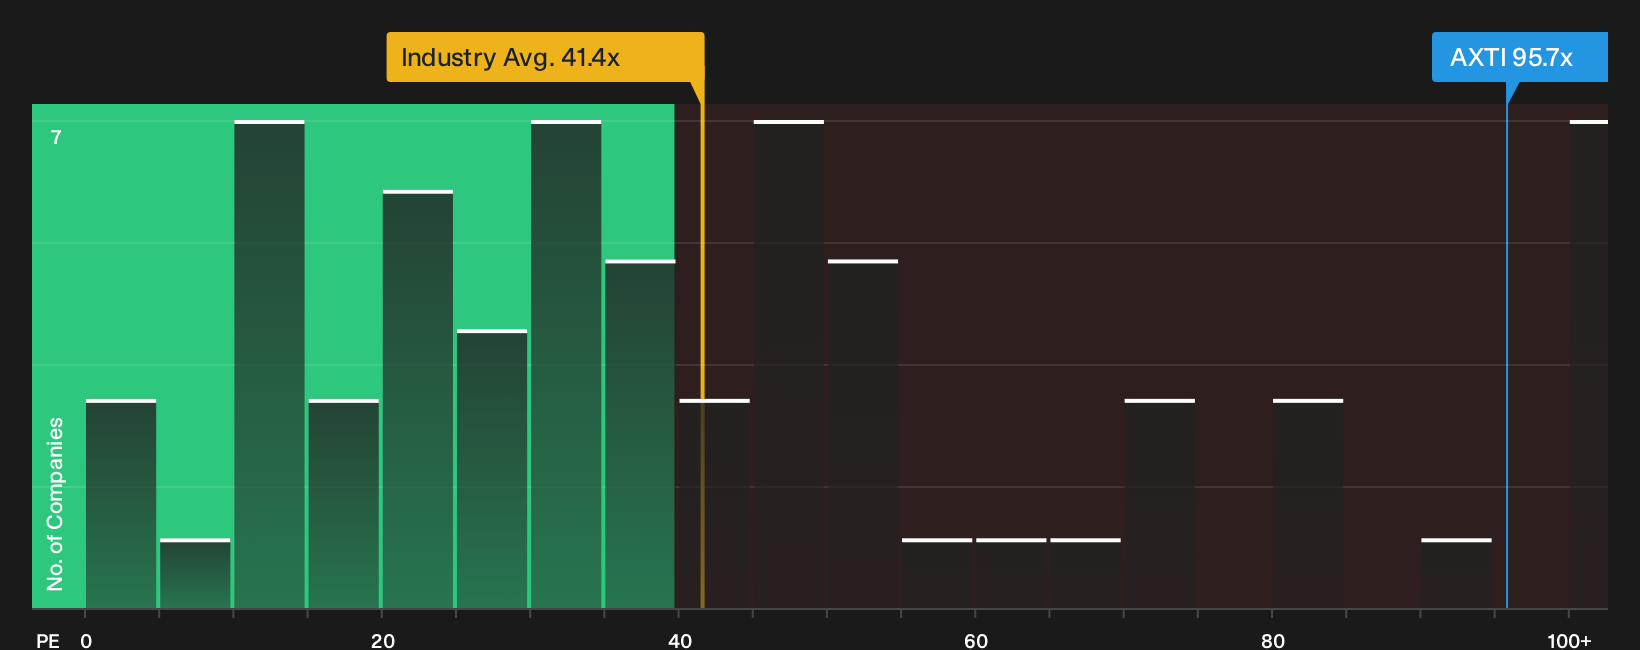
The P/E ratio fits AXT because earnings have moved into positive territory and investors are now paying directly for that income stream. At the latest price, AXT trades on a P/E of 95.7x, which is richer than the Semiconductor industry average of 41.4x and above the peer group on about 81.9x. A Fair Ratio, which blends the company’s growth profile, margins, risk and size into a tailored yardstick, also points to the current valuation sitting on the expensive side of what those fundamentals might usually support.
Record Q3 2026 profit tied to indium phosphide demand helps explain why the market is willing to pay such a premium multiple, although that enthusiasm already bakes a lot of optimism into the share price. For you as a shareholder or potential buyer, the key question is whether the earnings base that delivered that 95.7x P/E can be maintained or improved enough to make this premium feel justified over time. Explore the numbers behind AXT's P/E valuation.
The AXT Narrative: What Would Justify Today's Price?
Narratives on AXT sit between the rich P/E discussion and your own expectations, because they spell out which paths for revenue growth, profitability and earnings power would need to play out for the current share price to look materially higher or lower over time. Where a single ratio or model gives you one neat output, these narrative paths unpack the future that number relies on so you can watch how AXT's actual progress lines up.
One of the top narratives on AXT: 49% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Analysts expect AXT to continue building on its position in indium phosphide substrates for AI data center optics, supported by long-term supply agreements, a large backlog, and expanded capacity…"
Discover why this Narrative puts AXT at 49% undervalued.
AXT's price tag is only one piece of your decision
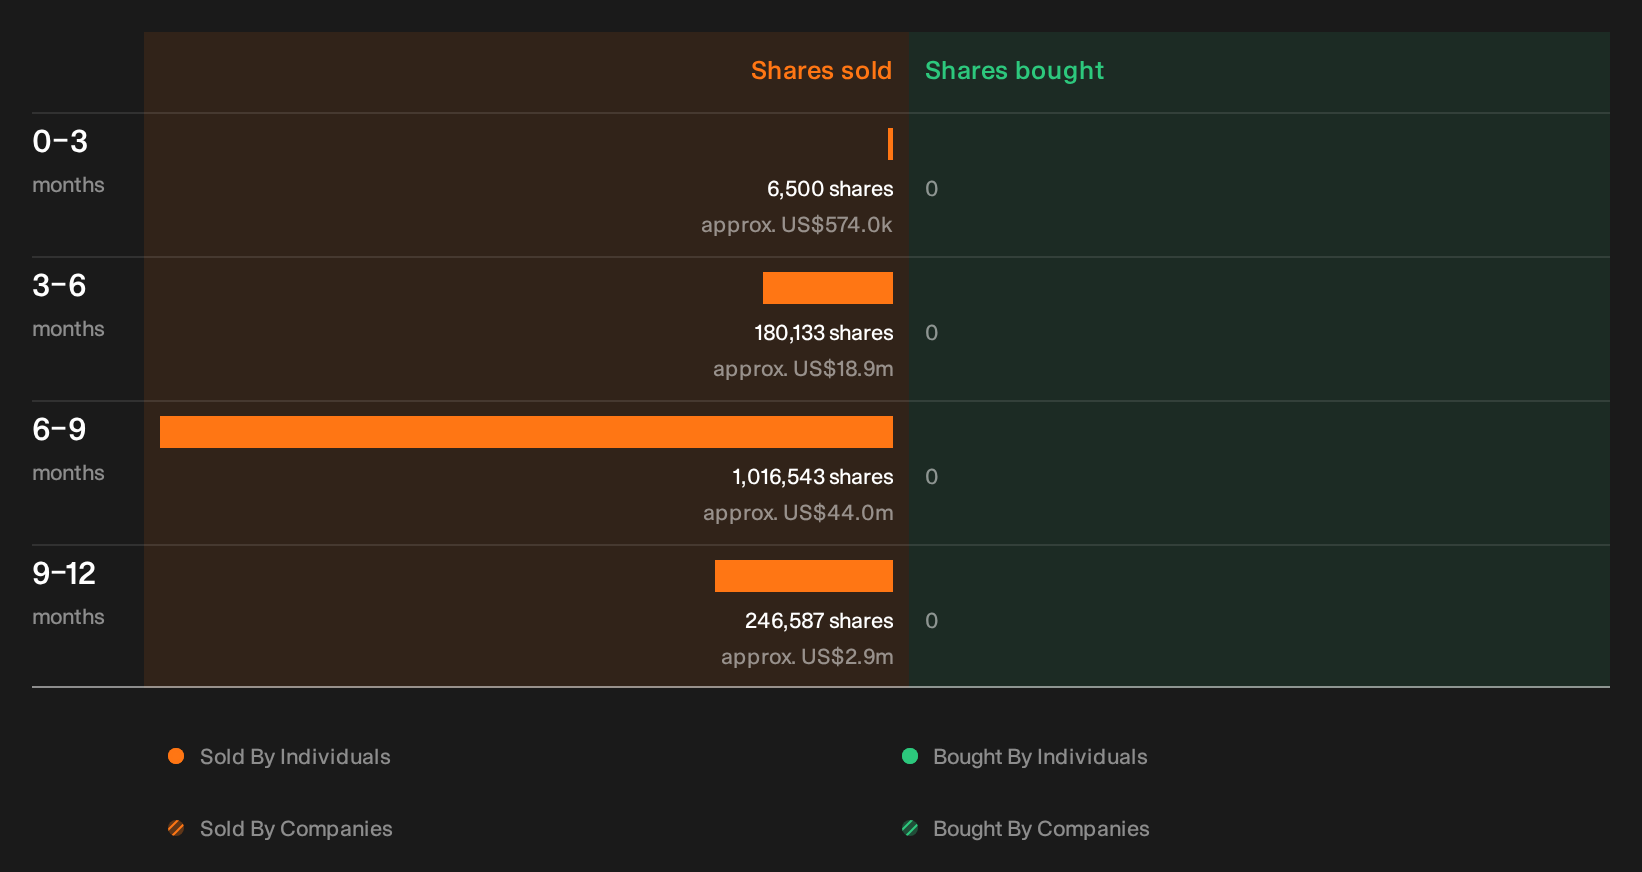
Before you stop at the valuation work, it is worth knowing that recent trading by people inside AXT has been flagged by our checks, with who sold, how much and why still for you to review in detail. See the recent insider selling flagged for AXT.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com