
How Vessel Earnings Strength At Nordic American Tankers Stock Has Changed Its Investment Story
- Nordic American Tankers recently reported what its CEO called a tanker bonanza, with average Time Charter Equivalent earnings of about $144,000 per day per vessel against cash operating costs under $10,000 per day. This supports ongoing profitability despite softer industry rates.
- The company is leaning on disciplined cost control and a dividend policy tied to its operating model rather than short term rate spikes. Management has also flagged expectations for softer revenue and earnings over the next few years, while signaling a focus on sustained cash generation.
- Next, the focus will be on how Nordic American Tankers' investment narrative is shaped by strong vessel earnings that comfortably exceed operating costs.
What Is Nordic American Tankers' Investment Narrative?
The big picture for a Nordic American Tankers shareholder is simple. You need to believe this is a pure play on Suezmax crude transport that can turn volatile day rates into steady cash, mainly through disciplined costs and a repeatable dividend framework. The recent tanker bonanza update fits that thesis neatly, because vessel earnings are running far above sub US$10,000 per day operating costs. In the short term, the key swing factors are still spot demand, charter pricing, and how actively NAT leans its 20 vessel fleet into that market.
Where it gets trickier is duration. Management is already signaling that revenue and earnings could be softer over the next few years, even as current cash generation looks strong. That message lines up with forecasts calling for declining earnings and revenue, and with a dividend that is not fully covered by profits. Add in capital intensive ships and a meaningful debt load, and the story becomes less about one quarter of eye catching rates and more about how NAT handles the next downshift in the cycle.
Even so, before treating Nordic American Tankers as a straightforward cash machine, there is an uncomfortable wrinkle around ...
There's only one way to know the right time to buy, sell or hold Nordic American Tankers. Head to Simply Wall St's company report for the latest analysis of Nordic American Tankers's Fair Value.
Exploring Other Perspectives
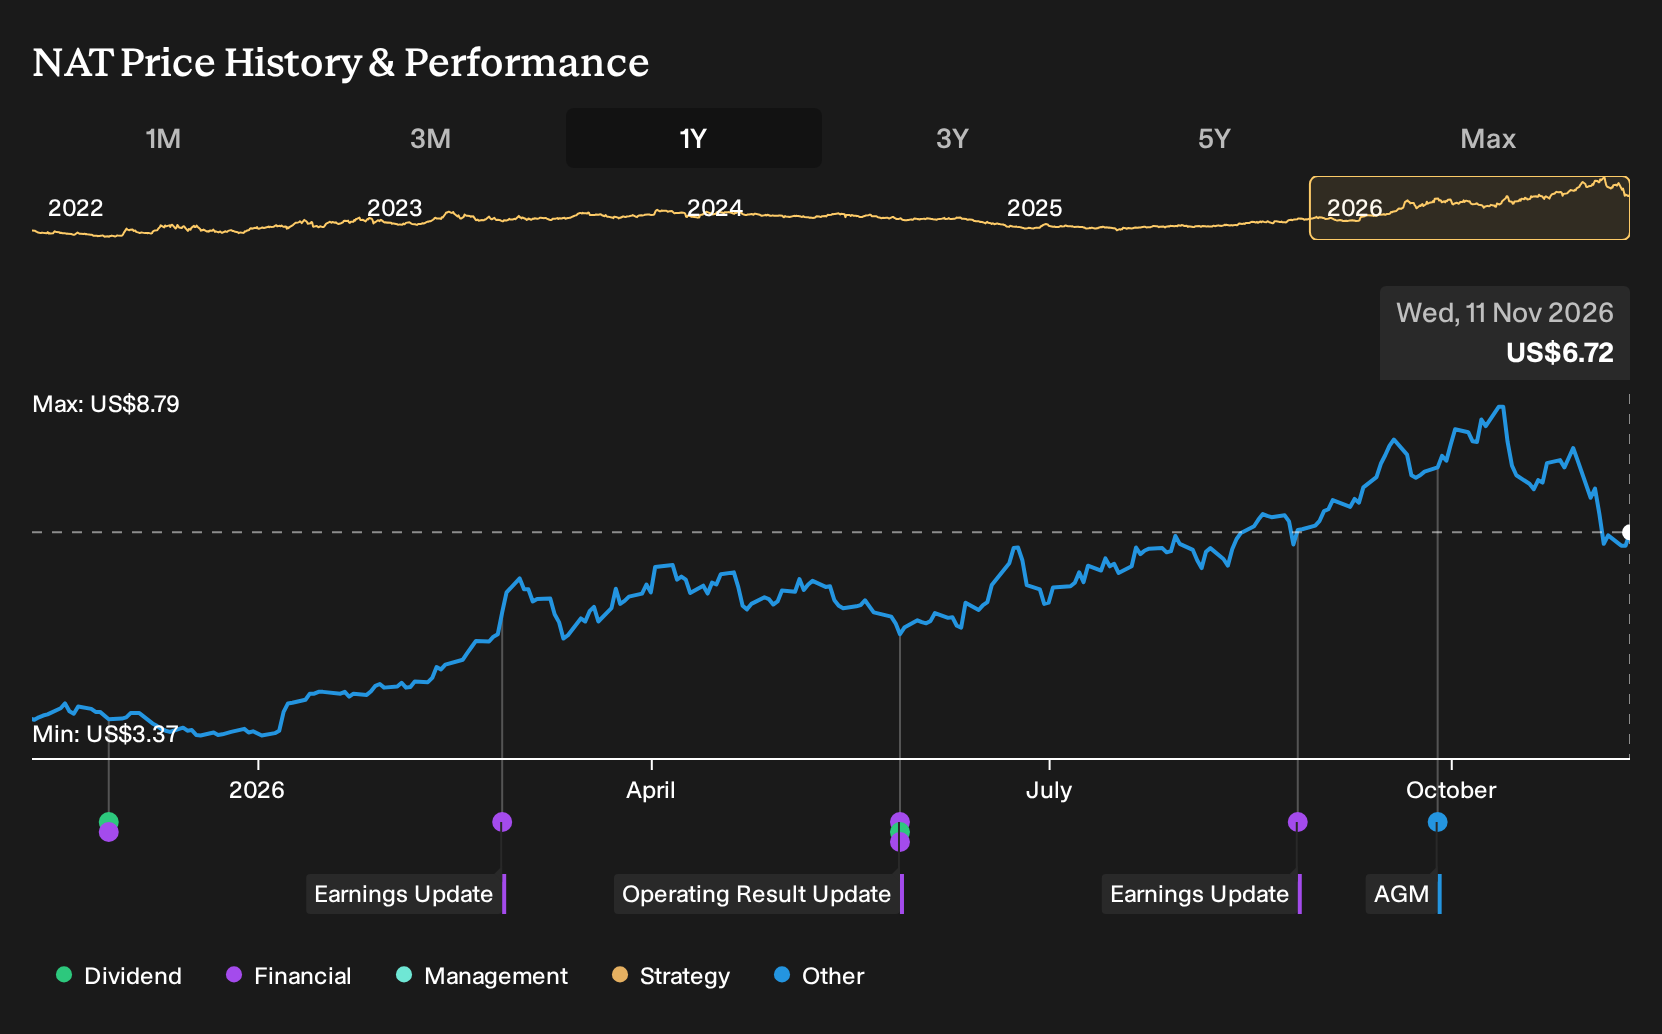
The Simply Wall St Community only has two fair value estimates for Nordic American Tankers so far, clustered between about US$6.77 and US$8.50 per share. Those views were formed before the recent tanker bonanza update, so fresh cash flow data could shift opinions and provide more contrasting viewpoints for you to consider.
Explore another Nordic American Tankers fair value estimate, including one that suggests as much as 26% upside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nordic American Tankers research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nordic American Tankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordic American Tankers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Nordic American Tankers?
If the Nordic American Tankers story has sharpened your focus on cash generation and risk, it can help to set that side by side with other businesses that share similar traits. The Simply Wall St Screener lets you quickly compare different types of opportunities without losing sight of balance sheets, dividends, or valuation discipline.
- If capital preservation matters most, scan for companies that score well on resilience and financial risk using the 30 resilient stocks with low risk scores.
- If you want a broader bench of potentially underpriced opportunities with robust fundamentals, line up candidates with the 32 high quality undervalued stocks.
- If consistent cash returns appeal to you, review income focused candidates through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com