
How AI Data Partnerships Will Impact FactSet (FDS) Investors
- FactSet Research Systems has recently partnered with Carbon Arc and Hamilton Lane, reaffirmed its fiscal 2027 guidance, and detailed AI focused product expansion at its Investor Day.
- The company is tying alternative data, private markets benchmarks, and AI driven tools directly into its workstation and MCP stack, reshaping how clients run research and portfolio analytics.
- We will now look at how FactSet’s push into AI ready alternative and private markets data could influence its broader investment narrative.
Scan how FactSet Research Systems’ push into AI ready data stacks up against peers by reviewing our curated list of 53 AI infrastructure stocks that are shaping the next generation of market infrastructure.
FactSet Research Systems Investment Narrative Recap
To own FactSet Research Systems, you need to believe that AI centric data workflows can keep clients engaged and willing to pay for richer analytics, even as markets scrutinize spending. According to LunaRodas, an investor in the Simply Wall St Community, the key swing factor is whether the AI flywheel around the Model Context Protocol translates into durable Annual Subscription Value momentum.
In the near term, the reaffirmed fiscal 2027 revenue and EPS guidance sets a clear execution bar. The quarterly dividend points to an ongoing capital return commitment. The main operational risk sits around debt levels and the heavier technology investment already flowing through margins, especially if consumption based pricing makes forecasting less predictable.
The Carbon Arc partnership looks central to that AI ASV story. By pushing more than 60 alternative data providers and over 500 data assets directly into the workstation and MCP ecosystem, FactSet Research Systems is trying to turn AI tools from a demo feature into something analysts lean on every day for research and idea generation.
For catalysts, this matters because LunaRodas sees MCP adoption and contract expansion as the practical test of the AI thesis. If Carbon Arc data leads to deeper use of AI agents and higher ASV per client, that would support management’s longer term margin recovery and growth targets. Execution risk is that complexity slows integration or clients underuse the new datasets.
LunaRodas anchors the fair value for FactSet Research Systems at US$258.69, built mainly on the belief that MCP driven AI workflows, higher ASV per client and the stated FY2026 margin floor together justify paying up for what is framed as a completed infrastructure cycle.
Uncover why FactSet Research Systems' fair value indicates a 23% potential downside to its current price, suggesting a premium that may not hold.
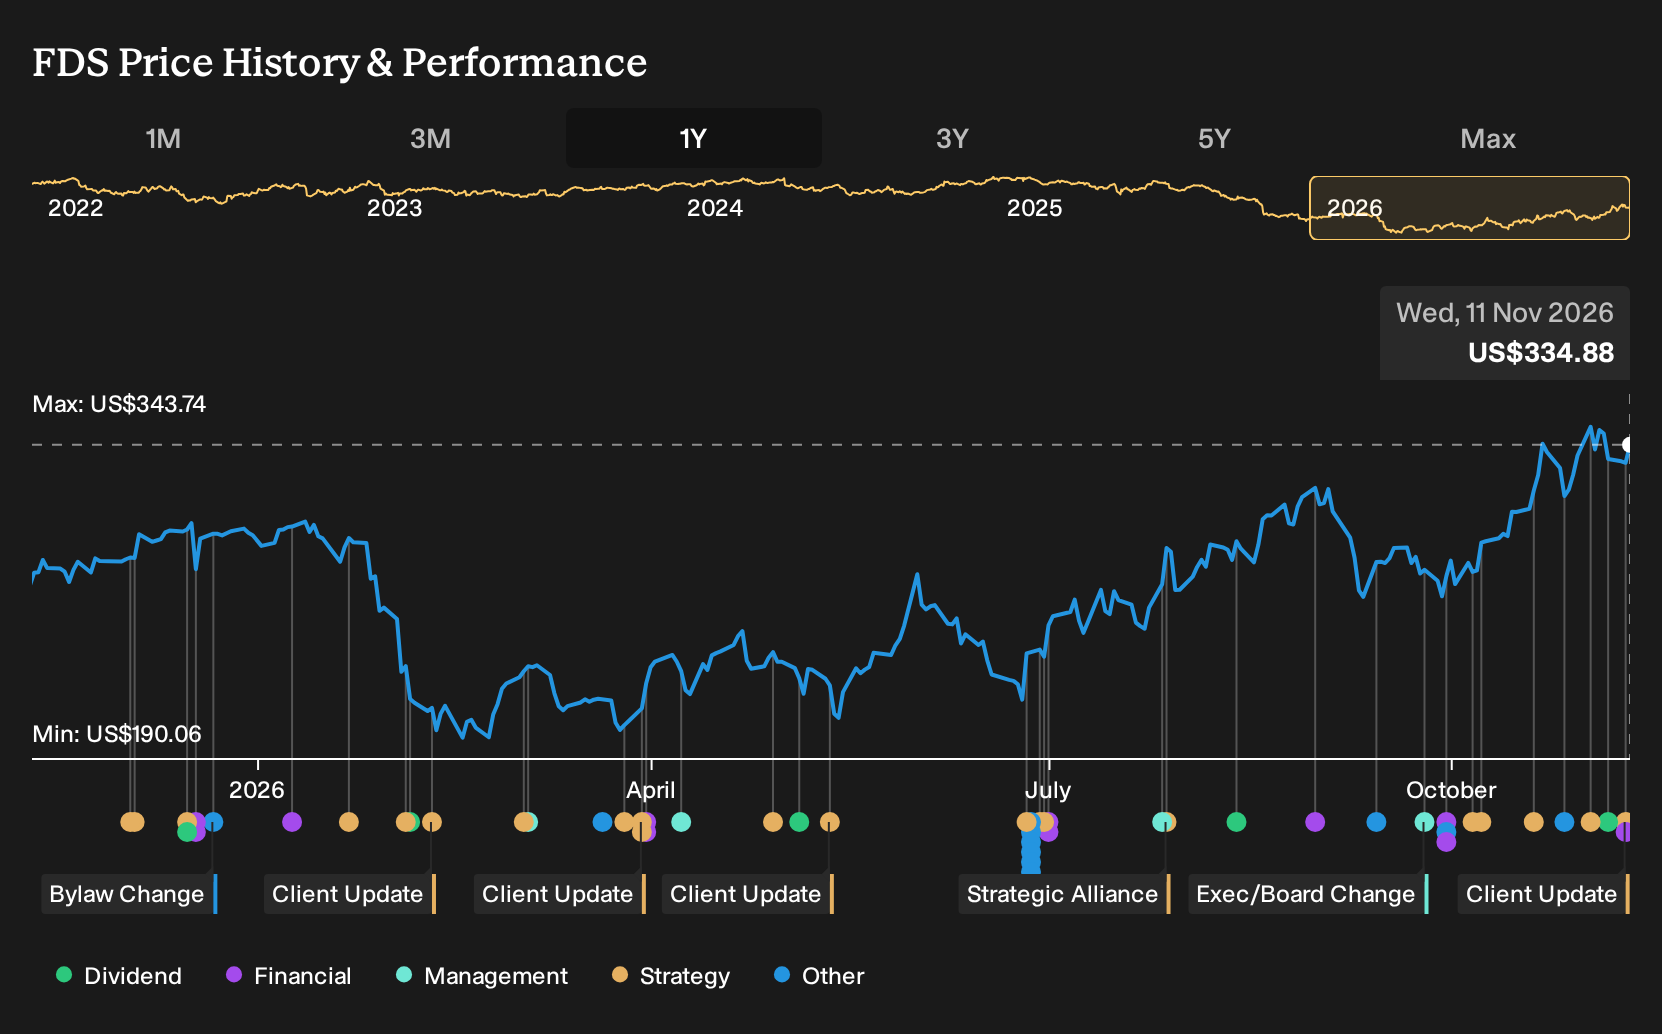
Exploring Other Perspectives
Some of the lowest ranked analysts frame a very different risk for FactSet Research Systems, focusing less on AI partnerships and more on slower growth. They were only pencilling in about 5.6% annual revenue growth and earnings of roughly US$655.2m by 2029. Those forecasts came before this news, so their narrative may shift meaningfully.
Explore 5 other FactSet Research Systems fair value estimates, including one that suggests as much as 33% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your FactSet Research Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FactSet Research Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FactSet Research Systems' overall financial health at a glance.
Looking for more investment ideas beyond FactSet Research Systems?
Once you have a handle on FactSet Research Systems, it often helps to zoom out and compare it with other opportunities that match your risk tolerance, income needs, and views on quality.
- If you want potential mispriced opportunities with stronger fundamentals, scan a curated 32 high quality undervalued stocks that combines solid financials with room for sentiment to catch up.
- If resilience matters more than excitement, focus on a handpicked 30 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier business profiles.
- If you are hunting for future leaders before they hit the spotlight, browse a targeted 19 high quality undiscovered gems built around companies with robust underlying metrics that the market may not fully be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com