
Top 3 Canadian Low Volatility Stocks To Watch In November 2026
Energy supply worries around the Strait of Hormuz have pushed inflation and interest rate decisions back into the spotlight, which puts balance sheet strength front and center for Canadian investors. When shocks hit, companies with low risk profiles and solid finances can give a portfolio its staying power. This article highlights three low volatility Canadian stocks from our quality filter that aim to offer that kind of foundation.
The three examples below are a starting sample, and the full Low Risk Leaders screen surfaced 6 more companies with equally compelling narratives that are not covered in this article. To identify and analyze those additional ideas with the same filters used here, head straight into the Low Risk Leaders screener.
Sprott (TSX:SII)
Sprott is a Toronto based asset manager focused on capital preservation, best known for physically backed precious metals funds and low volatility mandates that fit the Low Risk Leaders theme. Revenue is led by Exchange Listed Products at about $236 million, with Managed Equities at $94 million and Private Strategies at $78 million. The business is valued at roughly $4.2b.
For investors who want a foundation built on conservative products rather than leverage, Sprott’s fee based precious metals and wealth platforms offer recurring income streams, strong profitability and a debt free balance sheet. The main question is how generously that stability should be priced if one unseen pressure on growth and valuations shifts.
If you want to see how that trade off between stability and valuation is being priced into Sprott today, go straight to the DCF valuation analysis for Sprott for the full picture.
Torex Resources (TSX:TXR)
Torex Resources is a Toronto based precious metals producer anchored by its 100% owned Morelos Complex in Guerrero, Mexico, a cash generating operation that fits the Low Risk Leaders focus on solid balance sheets. The mine complex delivered about $2.0b in revenue and supports a market value near $6.8b.
The appeal of Torex Resources in a low risk foundation screen comes from that producing Morelos hub, which funds growth projects while keeping the balance sheet front and center in the analyst consensus Narrative on Simply Wall St.
"Successful completion and ramp-up of the Media Luna project, now supported by underground mining rates ahead of plan at Media Luna and ELG and on-schedule progress toward first ore at Media Luna North by late 2026, is set to materially increase production volumes and extend mine life, supporting long-term revenue growth and cash flow stability."
The real swing factor is how pressure on future cost levels and capital spending shapes that otherwise steady cash flow story.
That cost pressure is exactly what the full narrative for Torex Resources unpacks, highlighting where Torex Resources could see changes in value and where today’s relatively stable profile might be masking potential swings.

Imperial Oil (TSX:IMO)
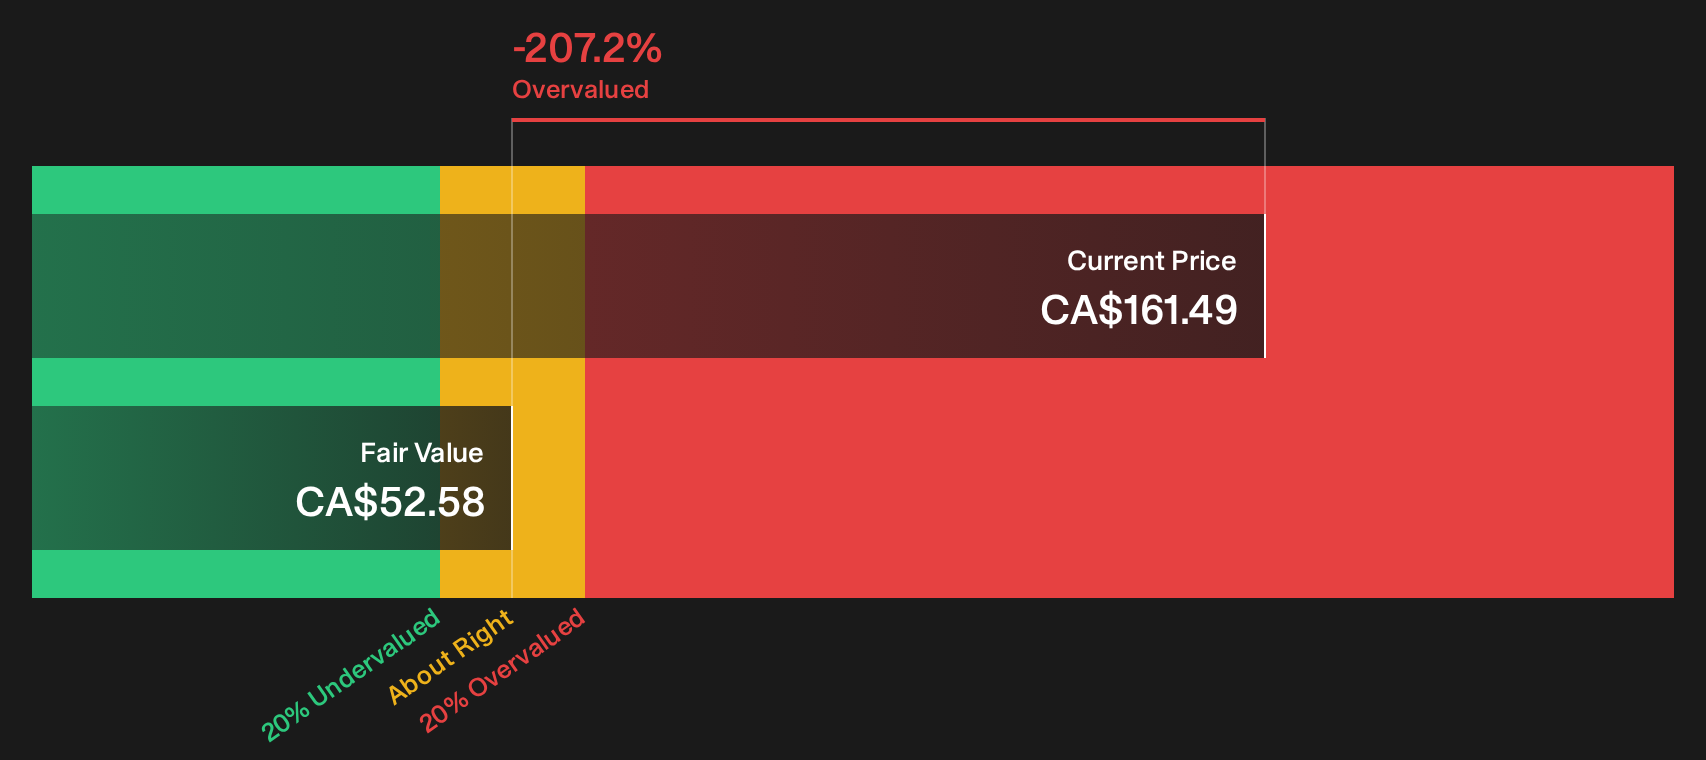
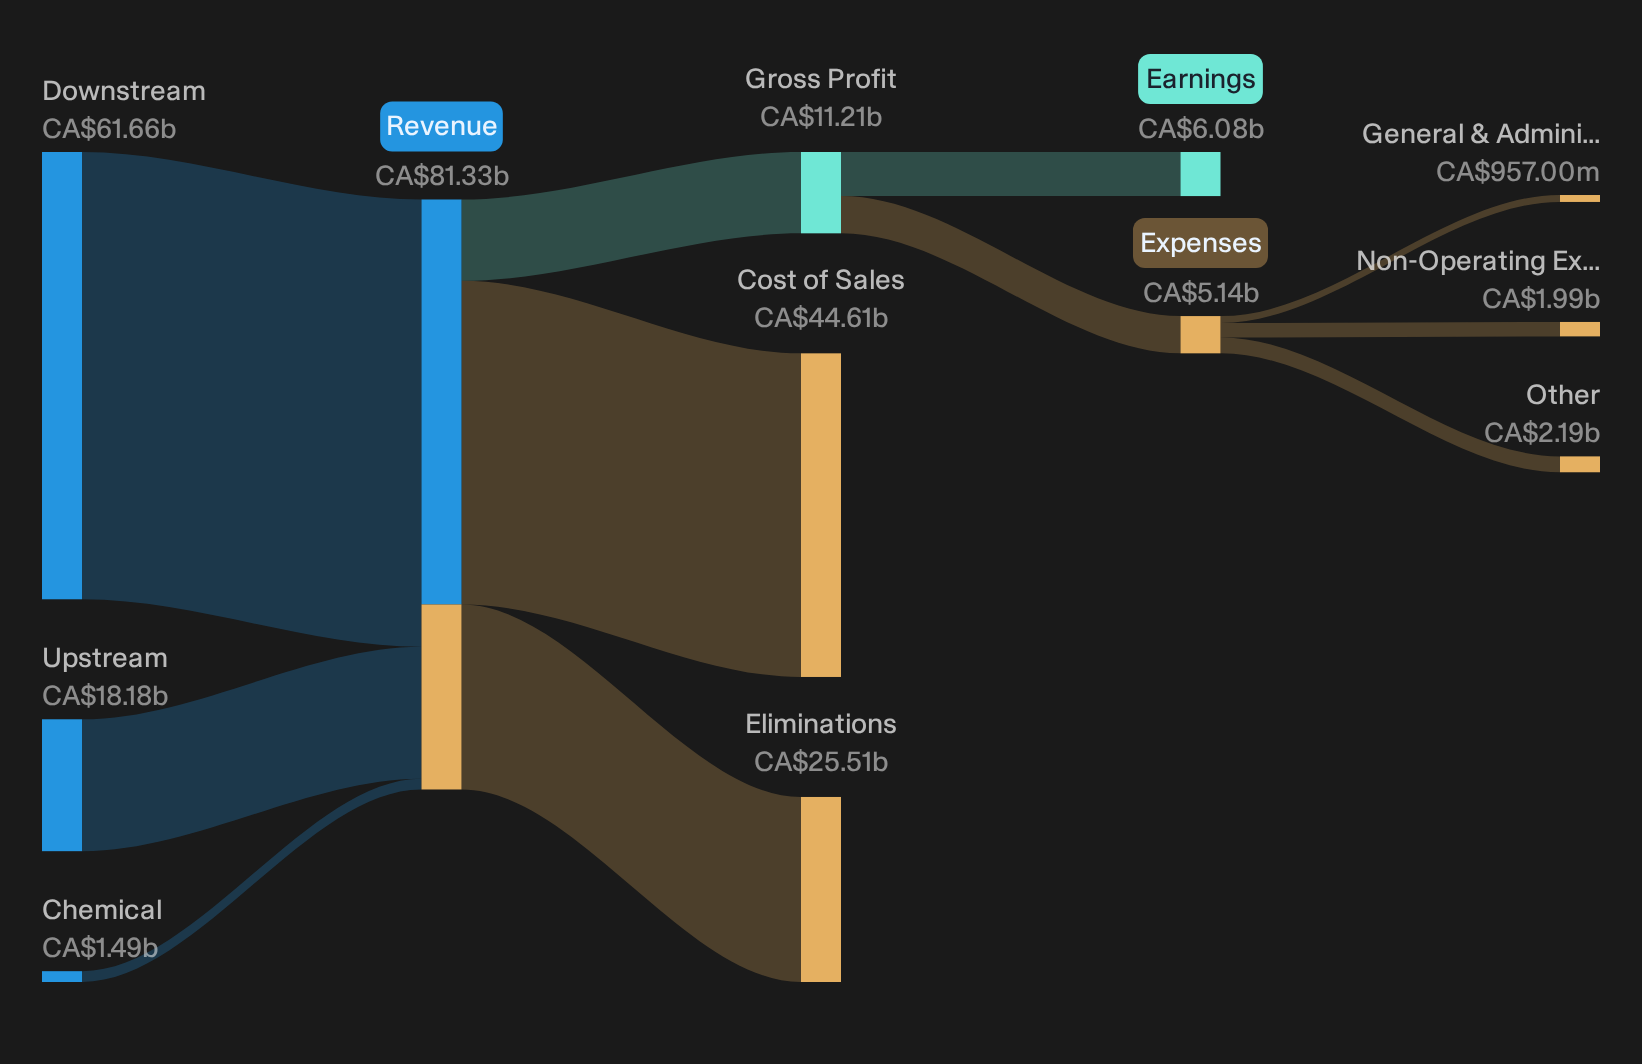
Imperial Oil is a Calgary based integrated energy business, with most revenue coming from its Downstream arm, which generated about CA$61.7b out of roughly CA$80.5b in segment sales, supported by CA$18.2b from Upstream and CA$1.5b from Chemicals, and a market value near CA$82.6b.
Imperial Oil brings something slightly different to this Low Risk Leaders group, because its Esso and Mobil branded refining and marketing network sits alongside the upstream oil sands engine that drives the headlines. The analyst consensus Narrative on Simply Wall St captures how that mix supports a foundation style profile while still providing room for operational improvement.
"Major efficiency improvements at Kearl, including delivery of unit cash costs below US$20 per barrel in 2025 and a stated target of US$18 per barrel with 300,000 bpd by 2027, together with 4 year turnaround intervals now in place, support the view that Imperial Oil can keep lifting upstream net margins and earnings power."
The real test for Imperial Oil is how one future shift in cost and throughput assumptions filters through to the steadier downstream cash flows investors count on.
That turning point is exactly where the full narrative for Imperial Oil shows how Imperial Oil’s cash engine could be accelerating, masking risks or quietly reshaping long term potential.
Seeking Alternatives Before Everyone Else?
Fresh opportunities move fast as momentum shifts, prices break out, and yesterday’s under the radar ideas start flying. Scan what others might miss while it matters and get in early.
- Target resilient income first by reviewing a curated group traders use for stability, then pressure test your watchlist against the 3 dividend fortresses.
- Hunt for early tech momentum by checking a filtered pool of future facing plays in the 53 AI infrastructure stocks before interest spreads and entry points start dropping.
- Track the next phase of energy infrastructure by reviewing a focused group that could benefit from grid upgrades with the 42 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com