
Soitec (ENXTPA:SOI) Faces An AI Valuation Test, Is The Stock Still Undervalued?
Soitec (ENXTPA:SOI) is drawing fresh attention as debate intensifies over whether its recent share performance and AI exposure fairly reflect future cash flow potential in a tougher European semiconductor backdrop.
Over the past year, Soitec has become one of the more debated semiconductor stocks in Europe as its share price return and AI narrative have pulled in different directions at different points. The 1 day share price return of 11.93% at a latest price of €108.35 comes after a 30 day share price return that fell 29.87% and a 90 day share price return that declined 18.66%. The year to date share price return is very large at about 335.67%, and the 1 year total shareholder return of 173.75% contrasts with a 3 year total shareholder return that fell 34.09% and a 5 year total shareholder return that declined 54.70%. This signals strong recent momentum set against a weaker longer term record.
Compare Soitec's sharp swing in returns with other chipmakers by scanning the 53 AI infrastructure stocks that are tightly linked to data centers and AI hardware demand.
Soitec’s surge this year sits awkwardly against its weaker multi year record, which leaves a simple puzzle. Has the business really changed that quickly, or has sentiment just swung too far?
Most Popular Narrative: 34% Undervalued
On the analyst consensus Narrative on Simply Wall St, Soitec’s fair value of €164.79 sits well above the last close of €108.35. This puts the recent share rebound in a different light when set against the analysts’ long run cash flow assumptions and discount rate of 11.75%.
The ongoing large-scale transition to AI, data center expansion and proliferating connected devices is now feeding directly into Soitec’s Photonics-SOI platform. This platform has already reached more than $100m of revenue with growth above 30% year on year and guidance for revenue to more than double again in FY27. This points to a growing contribution to group revenue and potentially higher margin mix.
See why 25 investors see Soitec as 34% undervalued.
Result: Fair Value of €164.79 (UNDERVALUED)
Still, Soitec’s RF-SOI inventory overhang and the tax settlement that removes roughly €320m of loss carry forwards could easily disrupt that upbeat cash flow story.
Find out about the key risks to this Soitec narrative.
Another View: What Multiples Say About Soitec
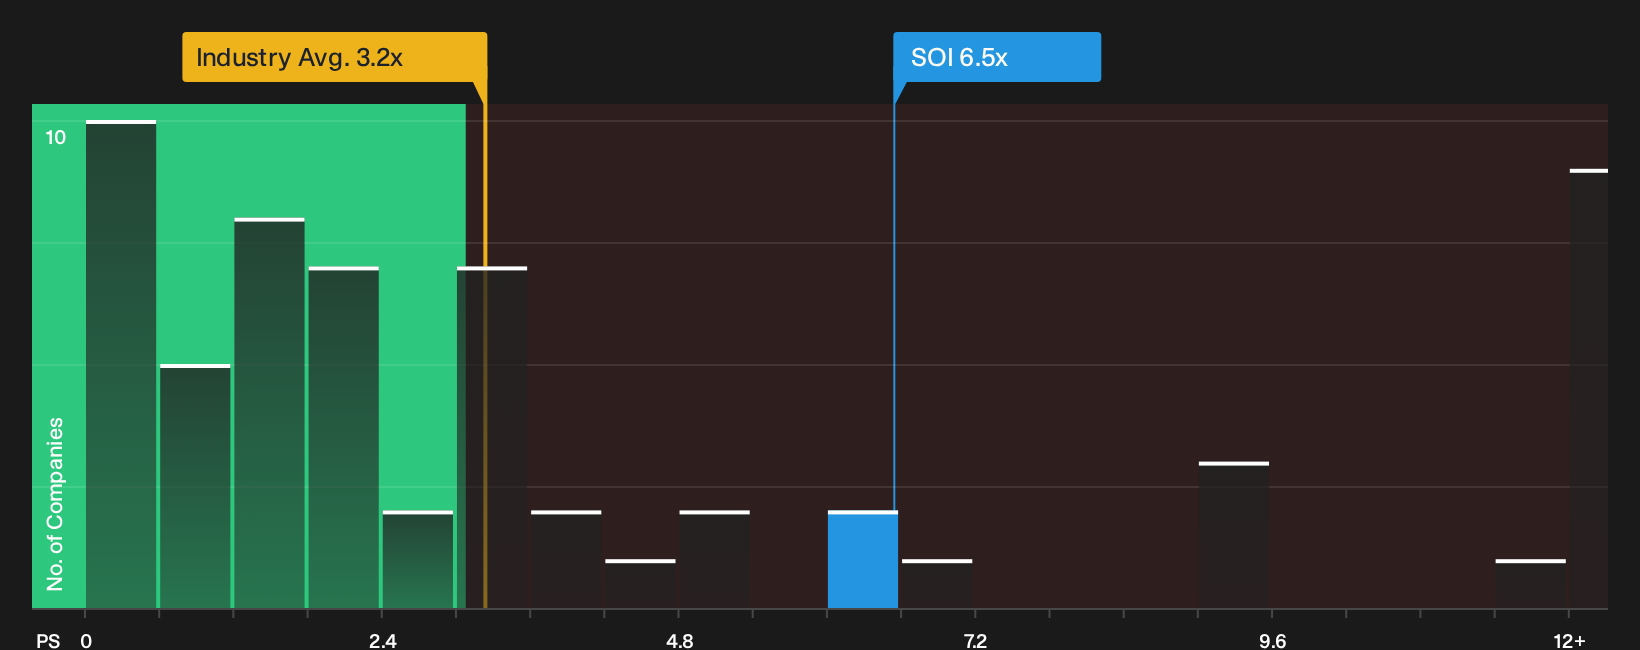
Analyst models currently indicate Soitec as undervalued against a fair value of €164.79, yet the market’s own yardstick tells a different story. On a P/S of 6.5x, the stock trades far above the European semiconductor average of 3.1x, the peer group on 4.1x and even its own fair ratio of 4.1x. That gap highlights valuation risk if sentiment cools or growth expectations slip, so how comfortable are you paying a premium on sales today?
To pressure test that sales multiple further and see how it compares against detailed peer and fair ratio work, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Conflicted by Soitec’s sharp rebound and its mixed longer term record? Move quickly from headline moves to the underlying risk reward mix by weighing 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Soitec?
If Soitec has sharpened your focus on valuation and risk, use that same lens to hunt for other stocks where the numbers and story truly line up.
- Target resilient balance sheets by filtering for companies with strong financial footing through the list of solid balance sheet and fundamentals (198 results).
- Spot potential mispricings by zeroing in on companies that score well on quality yet trade below intrinsic value using the 195 high quality undervalued stocks.
- Prioritize consistency and lower volatility by scanning companies screened for stability and resilience with the 206 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com