
Illumina (ILMN) After Its MRD Workflow Launch With Valuation Still In Focus
Why Illumina's MRD Duplex Workflow Matters For The Stock
Illumina (ILMN) has put its molecular residual disease research ambitions front and center with an early access duplex sequencing workflow that targets ultra low level circulating tumor DNA detection.
For you as an investor, this is not just another technical product tweak. It connects Illumina’s NovaSeq X hardware, DRAGEN software, and oncology focused consumables into a single MRD oriented workflow that could influence how consistently customers use its sequencing ecosystem.
The program is for research use only, and early access kits are scheduled to ship in the first quarter of 2027. Any commercial implications therefore sit on a multi year timetable rather than an immediate revenue shift.
Illumina’s share price has climbed 58.49% year to date to US$212.93, with a 90 day share price return of 11.55%, suggesting momentum has cooled recently after a sharp pullback of 21.48% over the past month.
That near term swing comes against a 1 year total shareholder return of 77.55% and a 3 year total shareholder return of 130.15%. The MRD workflow launch, raised 2026 revenue guidance, and the SG INSIGHT whole genome contract all feed into a story where expectations are already reset higher, and every new product update can shift how investors think about future execution risk.
Surface other genomics players riding similar precision medicine themes by scanning our curated list of 37 healthcare AI stocks that are pushing sequencing, data and AI deeper into healthcare.After a 77.55% 1 year run and a 21.48% pullback over the past month, Illumina sits in an awkward middle zone. Investors may be considering whether to commit now or wait for a cleaner entry based on the numbers.
Most Popular Narrative: 19% Undervalued
Illumina’s analyst consensus Narrative on Simply Wall St puts fair value at $261.45 per share, above the last close of $212.93. This frames the MRD workflow and broader clinical push inside a valuation that already incorporates meaningful progress but still signals upside according to that model.
Illumina's current valuation implies that the market is already pricing in high single digit revenue growth and substantial operating margin expansion toward 2030. This suggests limited room for the share price if the company delivers anything less than that path, so this narrative views the stock as overvalued and leans bearish.
See why 55 investors see Illumina as 19% undervalued.
Result: Fair Value of $261.45 (UNDERVALUED)
Still, Illumina’s MRD and AI data efforts could outpace cautious assumptions, and sustained clinical consumables demand might challenge a bearish narrative built on limited upside.
Find out about the key risks to this Illumina narrative.
Another View On Illumina's Valuation
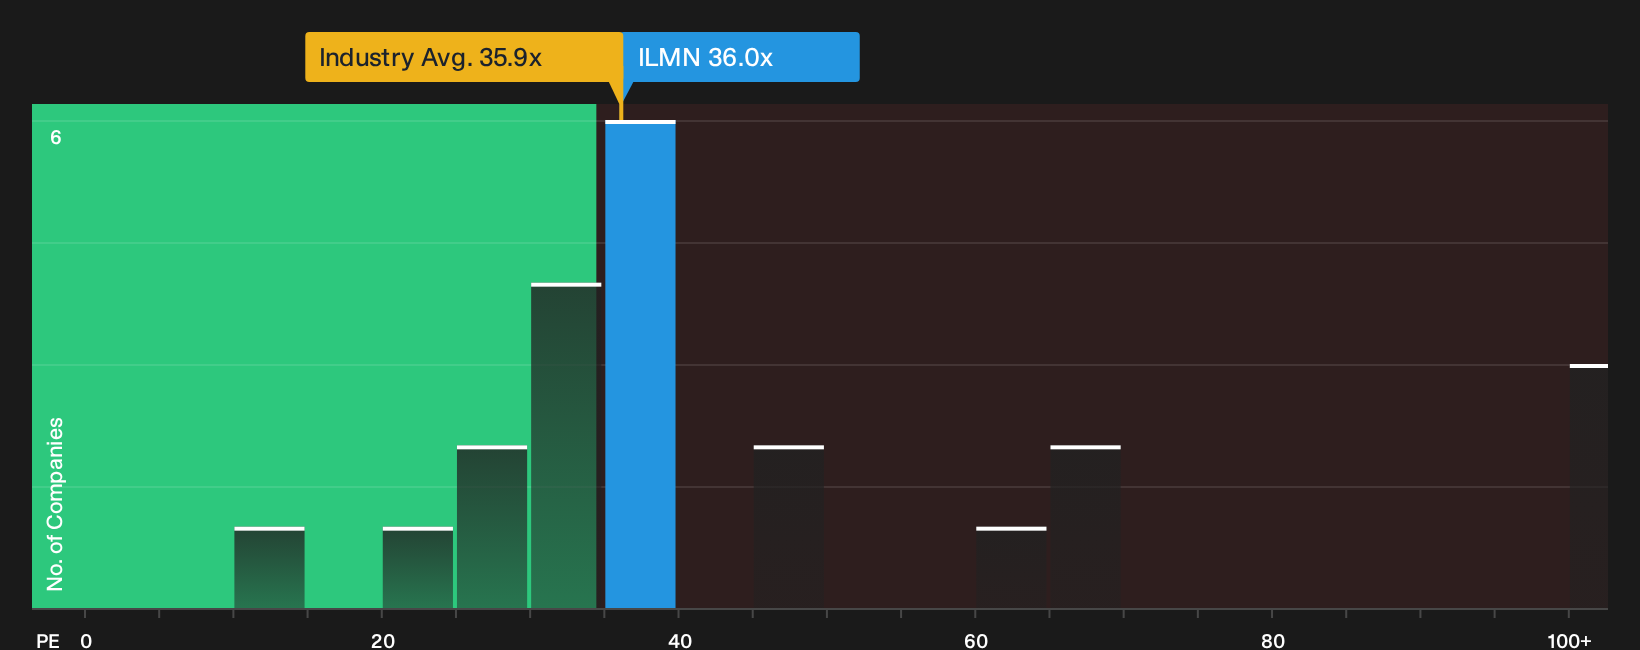
On the other side of the ledger, Illumina trades on a P/E of 36x, compared with a fair ratio estimate of 27.7x and a global Life Sciences average of 35.9x. That premium hints at less margin for error. If growth stumbles, how quickly could that valuation gap close?
For a closer look at what this pricing gap might mean in practice, including how it stacks up against similar businesses, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals on Illumina leave you torn, act quickly, review the underlying data, and pressure test both sides of the story using 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Illumina?
If Illumina has sharpened your appetite for opportunity, do not stop here. Put that curiosity to work and line up your next edge with a focused stock search.
- Target potential mispricings early by scanning a curated pool of 19 high quality undiscovered gems that pair solid fundamentals with lower investor attention.
- Prioritise resilience by filtering for 30 resilient stocks with low risk scores that score well on financial stability and business risk metrics.
- Stress test your income ideas against a list of solid balance sheet and fundamentals (23 results) so you are not relying on dividends backed by weak finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com