
Is Formula One Group (FWON.K) Fully Valued After Strong Q3 2026 Earnings?
Formula One Group (FWON.K) has moved into focus after releasing third quarter 2026 results, reporting revenue of US$1,226 million and net income of US$163 million, alongside improving sentiment toward the stock.
The earnings release has arrived alongside strong trading momentum, with Formula One Group’s share price up 19.5% over the past month and 13.4% year to date, while the 3-year total shareholder return of 75.1% points to solid longer term compounding.
Scan how Formula One Group’s recent momentum compares with other fast moving opportunities by checking the hand picked 19 high quality undiscovered gems in the market right now.
Bulls point to Formula One Group’s surging earnings and momentum, while bears question how much optimism is already priced in. The numbers give some clues once you line them up against today’s valuation.
Preferred P/E of 78.5x: Is it justified?
On a simple earnings yardstick, Formula One Group carries a P/E of 78.5x, while the last close sits at $111.17. That is a rich tag compared with many peers and it reflects a lot of optimism already embedded in the share price.
The P/E multiple compares the current share price to earnings per share. For a media and sports rights business like Formula One Group, it captures how much investors are willing to pay today for each dollar of current profit, given the growth profile, contract visibility, and perceived resilience of the motorsports franchise.
Earnings have grown strongly, with profit up 59.9% over the past year and an annual rate of 30.6% over 5 years, and earnings are forecast to grow about 22% per year. That helps explain why the market is paying a premium. Yet the current 78.5x P/E sits well above the estimated fair P/E of 26.4x, a level the market could move toward if expectations cool, and it also towers over both the US Entertainment sector on 16.7x and the peer average of 33.3x, which points to an aggressively priced stock rather than a bargain.
Explore the SWS fair ratio for Formula One Group.
Result: Price-to-earnings of 78.5x (OVERVALUED)
Still, any wobble in Formula One Group’s earnings trajectory, or a sharp reset in risk appetite toward high P/E media stocks, could quickly pressure that premium story.
Find out about the key risks to this Formula One Group narrative.
Another view on Formula One Group’s value
On earnings alone, Formula One Group looks expensive, and the SWS DCF model points in the same direction. At $111.17, the share price sits above an estimated future cash flow value of $92.51, which suggests limited valuation cushion if sentiment cools. How much premium are you comfortable paying for a star asset?
Look into how the SWS DCF model arrives at its fair value.
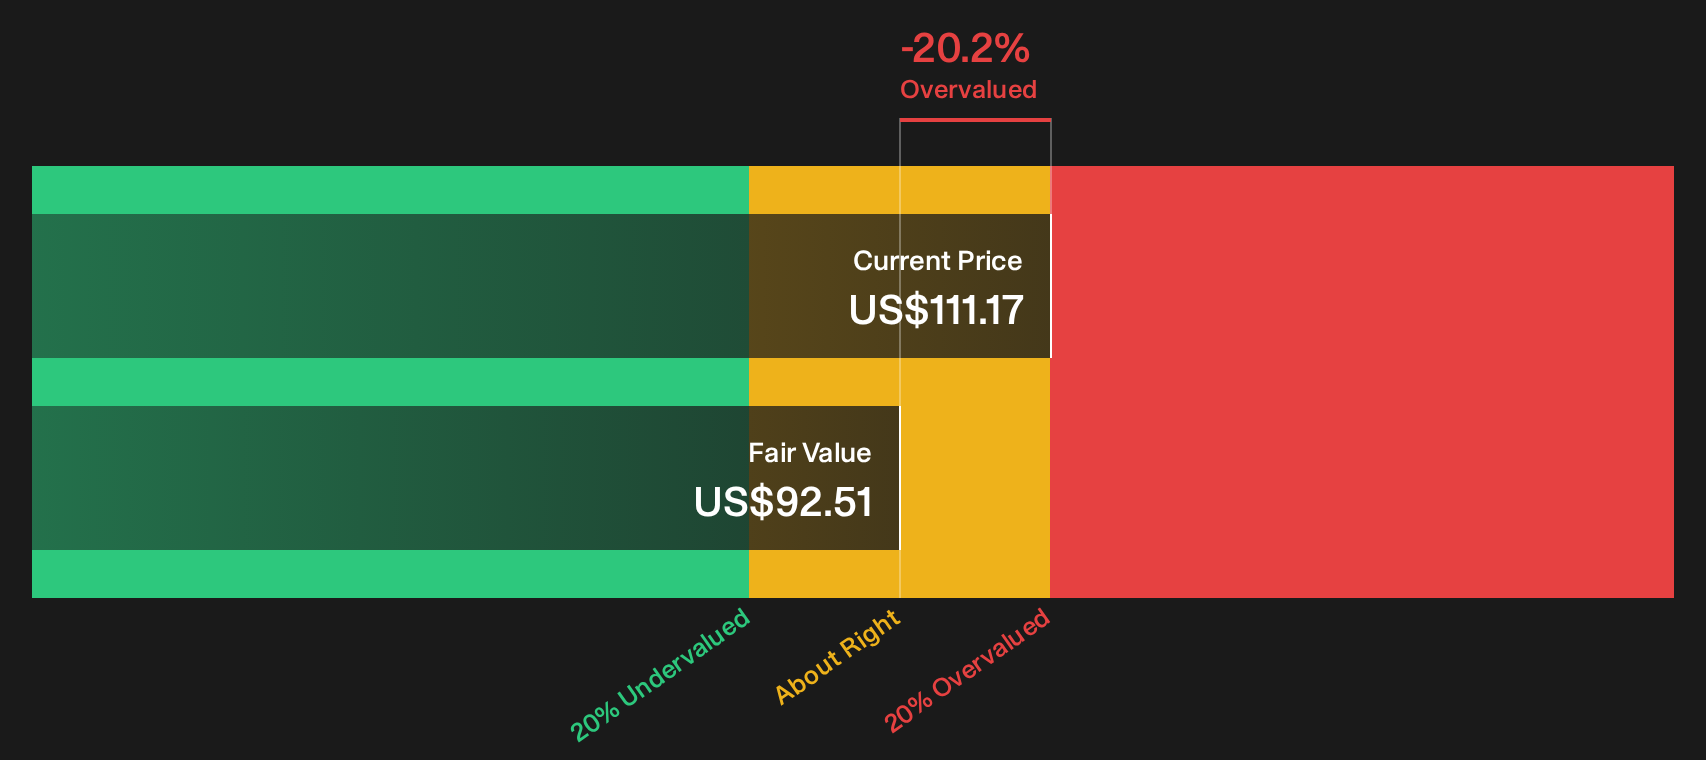
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Formula One Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Formula One Group is clearly split, which is exactly when real price setters do their own homework quickly and reach an independent view. To see what the optimism is based on, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Formula One Group?
If Formula One Group has sharpened your focus on quality, do not stop here. Broaden your opportunity set with a few targeted stock ideas that match clear objectives.
- Target stronger value by scanning companies that combine quality fundamentals with attractive pricing using the 32 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses with sturdier financial footing.
- Dial down volatility risk by checking a 30 resilient stocks with low risk scores tailored to highlight more stable return profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com