
Carter's (CRI) Stock Looks About Right Despite Its Low Earnings Price
Carter's has seen its share price fall a long way over the past few years, even as management reshapes the business and emphasizes earnings-focused initiatives. This puts a spotlight on whether the current valuation really lines up with its profit power. With the stock recently closing at US$34.60, the key issue for investors is whether that price still makes sense given what the company is earning today.
- Over the past 5 years the share price has declined 60.3%, which puts pressure on the case that the existing earnings profile can support a sustained recovery in investor confidence.
- The recent leadership restructure that tightens alignment across product, sales, brand, and operations may support a different earnings mix, with potential implications for margins and how resilient profits can be through consumer cycles.
- Your read on Carter's is one view; the desks covering it have another. See what analysts think Carter's's shares could be worth.
The stock's next move may depend on whether the current price is justified by Carter's earnings when set against a Fair Ratio benchmark.
If you are weighing Carter's against other earnings driven stories, it can help to line it up beside 32 high quality undervalued stocks.
Is Carter's Fairly Priced on Earnings?
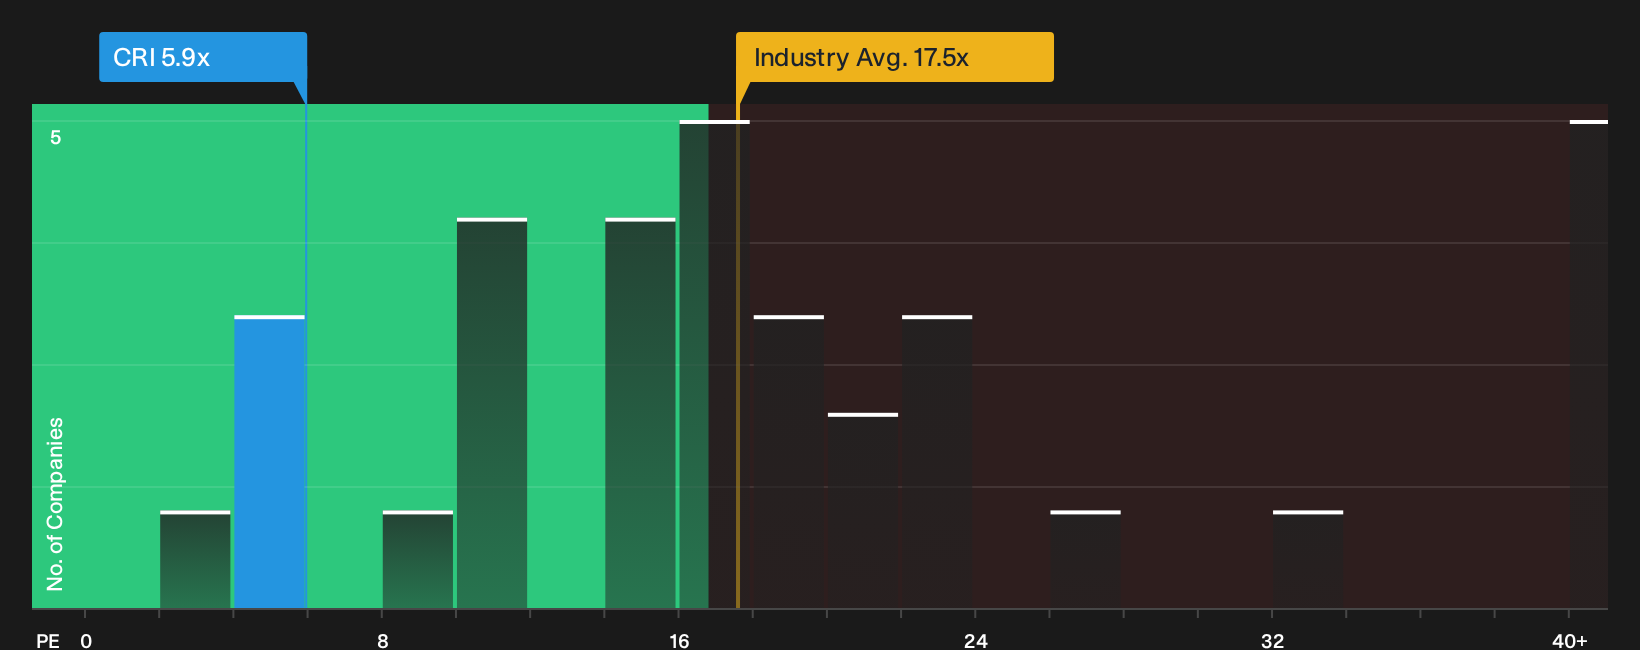
The P/E ratio suits Carter's because earnings remain the main lens investors use to judge the business. At around 5.9x, the stock trades at a sizable discount to the Luxury industry average of 17.5x and below the peer group average of 14.2x, which points to a cautious view on the durability of the profit stream. A Fair Ratio model that blends growth, margins, size and risk suggests the current multiple is broadly in line with what those fundamentals support, so the low headline P/E does not automatically imply a clear bargain.
Because the recent leadership restructure coincides with margin gains but a lower near term revenue outlook, the market appears to be giving Carter's some credit for earnings quality while still pricing in uncertainty about how dependable that profit base will be. The current valuation leaves investors weighing whether the discounted P/E reflects overly downbeat sentiment or simply a realistic assessment of the business earnings profile. Explore the numbers behind Carter's's P/E valuation.
The Carter's Narrative: What Would Justify Today's Price?
Simply Wall St Narratives step in after the valuation puzzle for Carter's and explain which paths for revenue, profitability and earnings would need to unfold for the share price to justify a meaningfully higher or lower level than today. Rather than relying on a single multiple or model line, each scenario lays out the key building blocks behind its view of fair worth so you can compare those assumptions with Carter's actual results over time.
The bullish and bearish narratives on Carter's sit on opposite sides of the valuation fence, and they hinge on very different earnings paths.
Bull case: 9% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which folds multiple forecasts into one shared scenario.
"The current numbers and recent share price performance imply that the market is still pricing Carter's cautiously despite delivery on revenue growth, cash generation, and cost savings..."
Discover why this Narrative puts Carter's at 9% undervalued.
Bear case: 24% overvalued
The bearish analyst Narrative on Simply Wall St sees the same Carter's data and leans toward a more cautious setup for earnings and sales.
"The current valuation and guidance suggest that Carter's share price already reflects a fairly valued, bearish scenario in which earnings drift lower in 2026, while cash generation and cost savings remain supportive..."
Explore why this Narrative puts Carter's at 24% overvalued.
One more Carter's check that sits beyond the share price maths
Price ratios only tell you so much, because the real lever on future outcomes is who runs Carter's, how their incentives are set, and whether those pay packets truly align with your interests. See who runs Carter's and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com