
Charles River Climbed 100% While Sales Fell
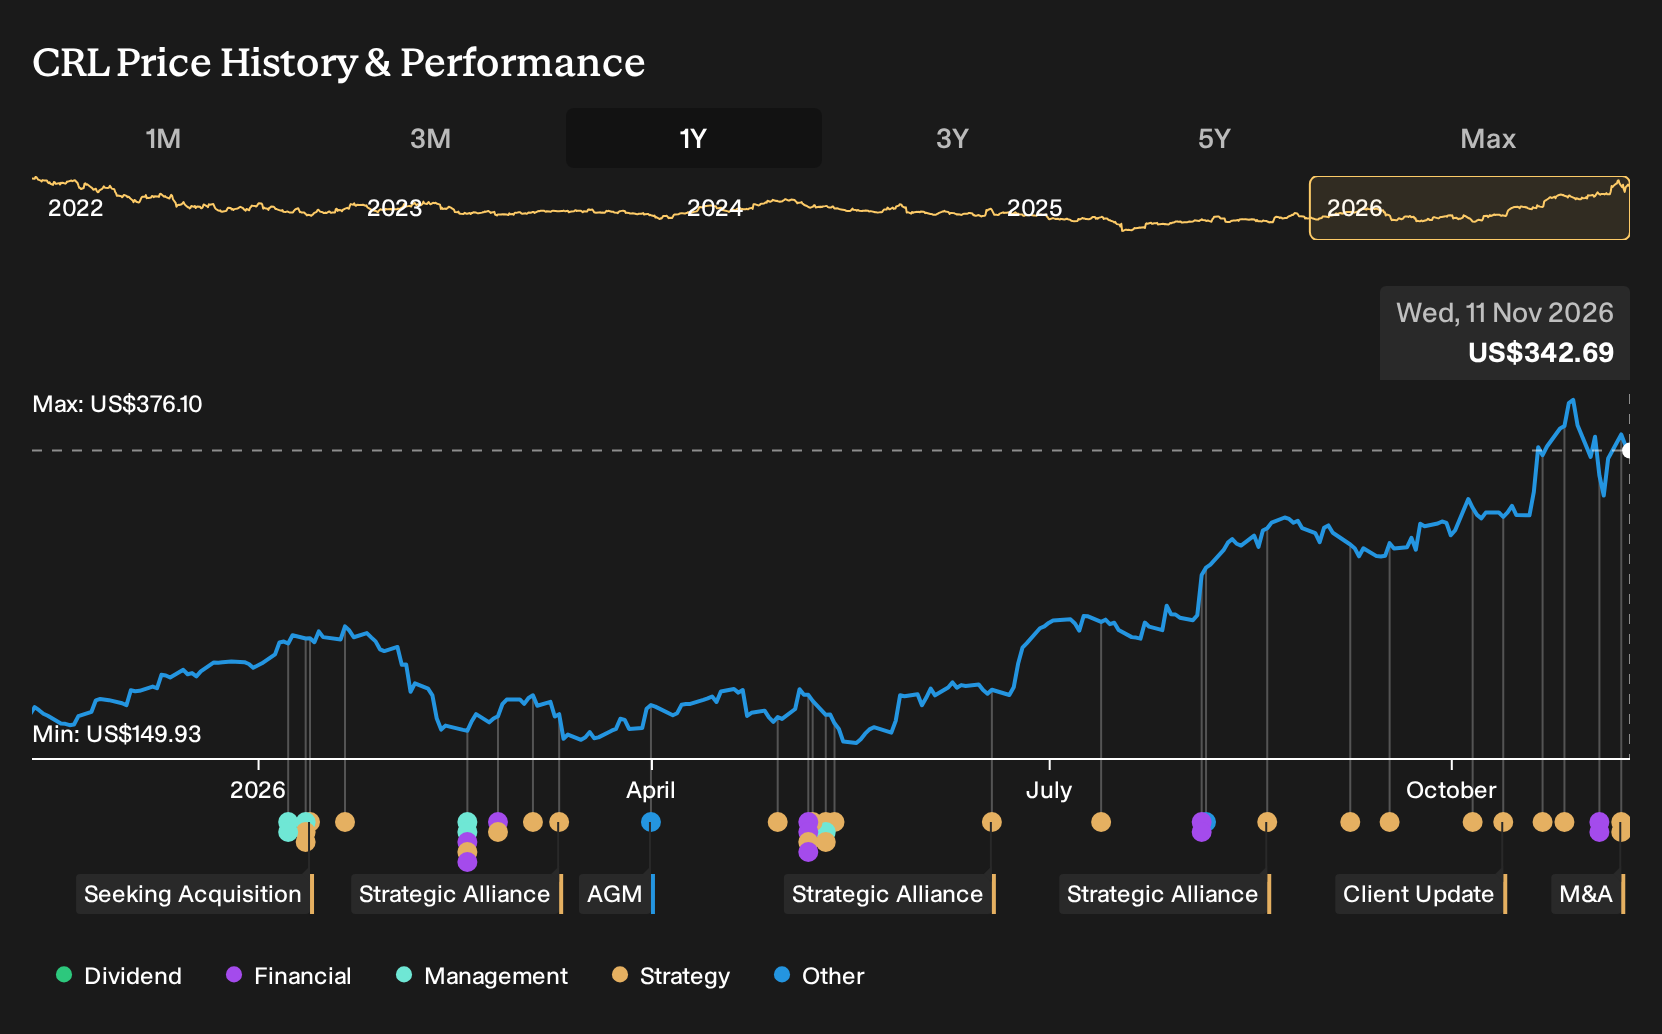
If Charles River Laboratories International sat on your watchlist instead of in your portfolio, the recent move probably feels expensive in hindsight. Investors who held Charles River Laboratories International over the past year are up 99.8%, including dividends. That outcome invites a harder question. Given the early split between bulls betting on rapid NAMs adoption and bears warning that regulatory shifts would shrink animal testing, what business assumption about Charles River’s role in alternative methods could reasonably have guided you a year ago?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Charles River Laboratories International harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Two Competing Stories Around Charles River Laboratories International
The shares cost US$174 at the start of the period, so any view on Charles River Laboratories International began with whether that quote already captured the next few years of NAMs adoption and regulatory change.
The bullish narrative set Fair Value at US$200, 15% above the start price, based on the idea that rapid New Approach Methods uptake and integrated digital services could accelerate revenue growth and lift margins through higher operating leverage.
The bearish case put Fair Value at US$79.1, 54% below the start price, with the argument that regulatory shifts toward alternatives to animal testing would steadily erode demand for Charles River’s core preclinical services and weigh on long term revenue.
What The Results Changed For The Charles River Laboratories International Debate
The clearest development was Charles River Laboratories International locking in Q3 2026 net income of US$333.1 million on revenue of US$982.7 million, which pushed net margin up to 33.9% from 5.4% a year earlier. That profitability shift backed the bullish view on margins and operating leverage, although the drop in revenue kept the bear case on growth risks alive. Overall, the evidence cut both ways.
The hinge assumption a year ago was whether Charles River’s shift toward NAMs, AI tools and higher value services would show up in margins faster than any drag from pressure on animal testing work. When assessing another contract research group, focus first on the direction of net margin and mix commentary around newer platforms, not just headline revenue.
What Charles River Laboratories International’s Run Already Prices In
After a 99.8% gain over the past year, Charles River Laboratories International now trades at US$343. The bearish analyst narrative on Simply Wall St places its fair value below that level and argues the recent recovery already bakes in a lot of execution success.
The distinct concern is not the science. It is whether digital modernization, NAM adoption and higher margin services actually convert into the earnings power implied by today’s valuation, especially if cost savings, study volumes or pricing traction fall short.
"The numbers imply the share price already reflects strong execution on cost savings, mix shift toward higher margin segments, and sustained biotech funding support, which leaves limited room for disappointment if demand, pricing, or margin expansion fall short of current expectations."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 38% below our estimate - helps clients untangle complex failures, user risks and regulatory questions in AI programs.
- Company 2 - 34% below our estimate - ties subscription software and AI services to existing standardized cloud infrastructure for customers.
- Company 3 - 44% below our estimate - supplies GPU systems that AI data centers prioritize when power, space and tools are constrained.
Those are three of them. See every one of the 23 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com