
Earnings Jump Might Change The Case For Investing In AMAG Austria Metall Stock (WBAG:AMAG)
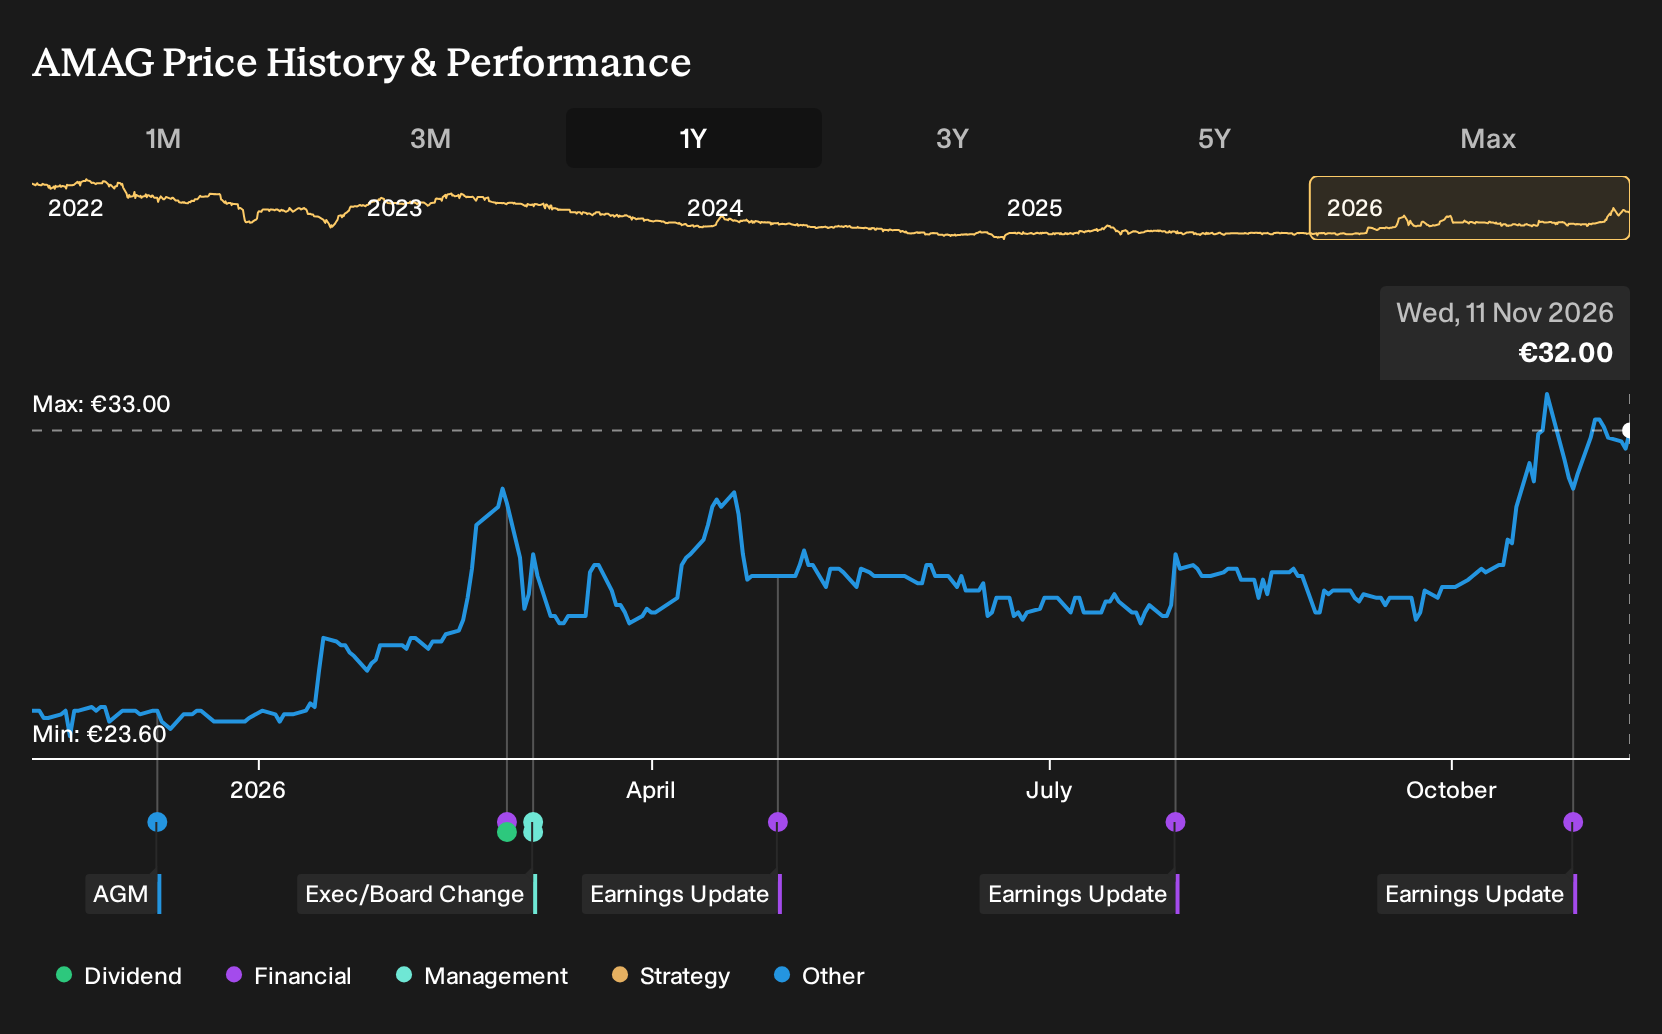
- AMAG Austria Metall reported third quarter 2026 sales of €472.7 million and net income of €41 million, with nine month figures at €1,323.4 million of sales and €81.7 million of net profit, all compared with the same periods a year earlier.
- The sharp step up in profitability relative to the prior year highlights how AMAG Austria Metall's mix shift and aluminium pricing environment are feeding through to the income statement. This matters for a business model heavily exposed to recycling economics and premium flat rolled products.
- We will now look at how AMAG Austria Metall's stronger third quarter earnings reshape the existing investment narrative around margins and cash.
Scan how AMAG Austria Metall's earnings momentum compares with other industrials by checking a curated set of list of solid balance sheet and fundamentals (198 results)
AMAG Austria Metall Investment Narrative Recap
To own AMAG Austria Metall, you need to believe the recycling heavy model and premium flat rolled focus can keep earning power resilient through aluminium cycles. The analyst consensus narrative on Simply Wall St leans on mix shift into higher margin segments and long term aluminium demand. The latest quarter, with €472.7 million in sales and €41 million in net income, supports that story but raises a fresh question: can this level of profitability hold if pricing or product mix soften?
The near term catalyst is still cash conversion. First half 2026 showed negative operating and free cash flow despite just over €100 million of EBITDA, mainly from working capital and valuation effects. Strong third quarter earnings help sentiment but do not yet resolve concerns around leverage, dividend cover and whether debt is well supported by future operating cash flow.
The most relevant datapoint to set against these results is the earlier disclosure that operating cash flow for the first half of 2026 was a €57 million outflow, with free cash flow at a €76 million outflow. That sits uncomfortably next to the very large year on year earnings growth that Simply Wall St highlights and it is where many investors will keep their focus.
For you as a shareholder, the link between these strong reported profits and actual cash generation is the operational hinge. Working capital tied up in higher aluminium prices and backwardation driven valuation effects can reverse, yet they can also repeat. How AMAG Austria Metall manages this, while funding R&D supported by the €86.6 million European Investment Bank loan and handling debt that is not well covered by operating cash flow, will likely shape how durable this quarter’s earnings look in hindsight.
AMAG Austria Metall's current analyst story links a forecast for €1.7 billion of revenue and €72.6 million of earnings by 2029 to an assumed 2.8% yearly revenue growth rate and an earnings increase of about €21.3 million from today’s €51.3 million profit base.
Uncover why AMAG Austria Metall's fair value indicates that earnings expectations are roughly in line with its current price.
Exploring Other Perspectives
One alternate view on AMAG Austria Metall leans hard into utilization as the real catalyst. The most optimistic analysts were already pencilling in about €1.7b of revenue and roughly €73.7 million of earnings by 2029, before this quarterly jump in profit. That camp sees the stock as undervalued, so you may want to compare how this fresh earnings print could reshape both the cautious cash flow story and the more upbeat high utilization case.
Explore another AMAG Austria Metall fair value estimate, including one estimate that suggests it could be worth as much as €31.95.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AMAG Austria Metall research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AMAG Austria Metall. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMAG Austria Metall's overall financial health at a glance.
Looking for more investment ideas beyond AMAG Austria Metall?
Once you have a view on AMAG Austria Metall, it can help to compare it with other opportunities and see where it really earns a spot in your portfolio.
- If you care most about strong fundamentals and conservative risk, start with a carefully filtered 206 resilient stocks with low risk scores that aims to keep downside in check.
- For investors looking for quality at a reasonable tag, compare AMAG Austria Metall with a 195 high quality undervalued stocks that pairs solid business metrics with prices that may not fully reflect them yet.
- Income-focused readers can broaden their shortlist by scanning a 213 dividend fortresses that offers sizeable yields backed by more robust balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com