
Will Earnings Beat Change Arrow Electronics' (ARW) Narrative
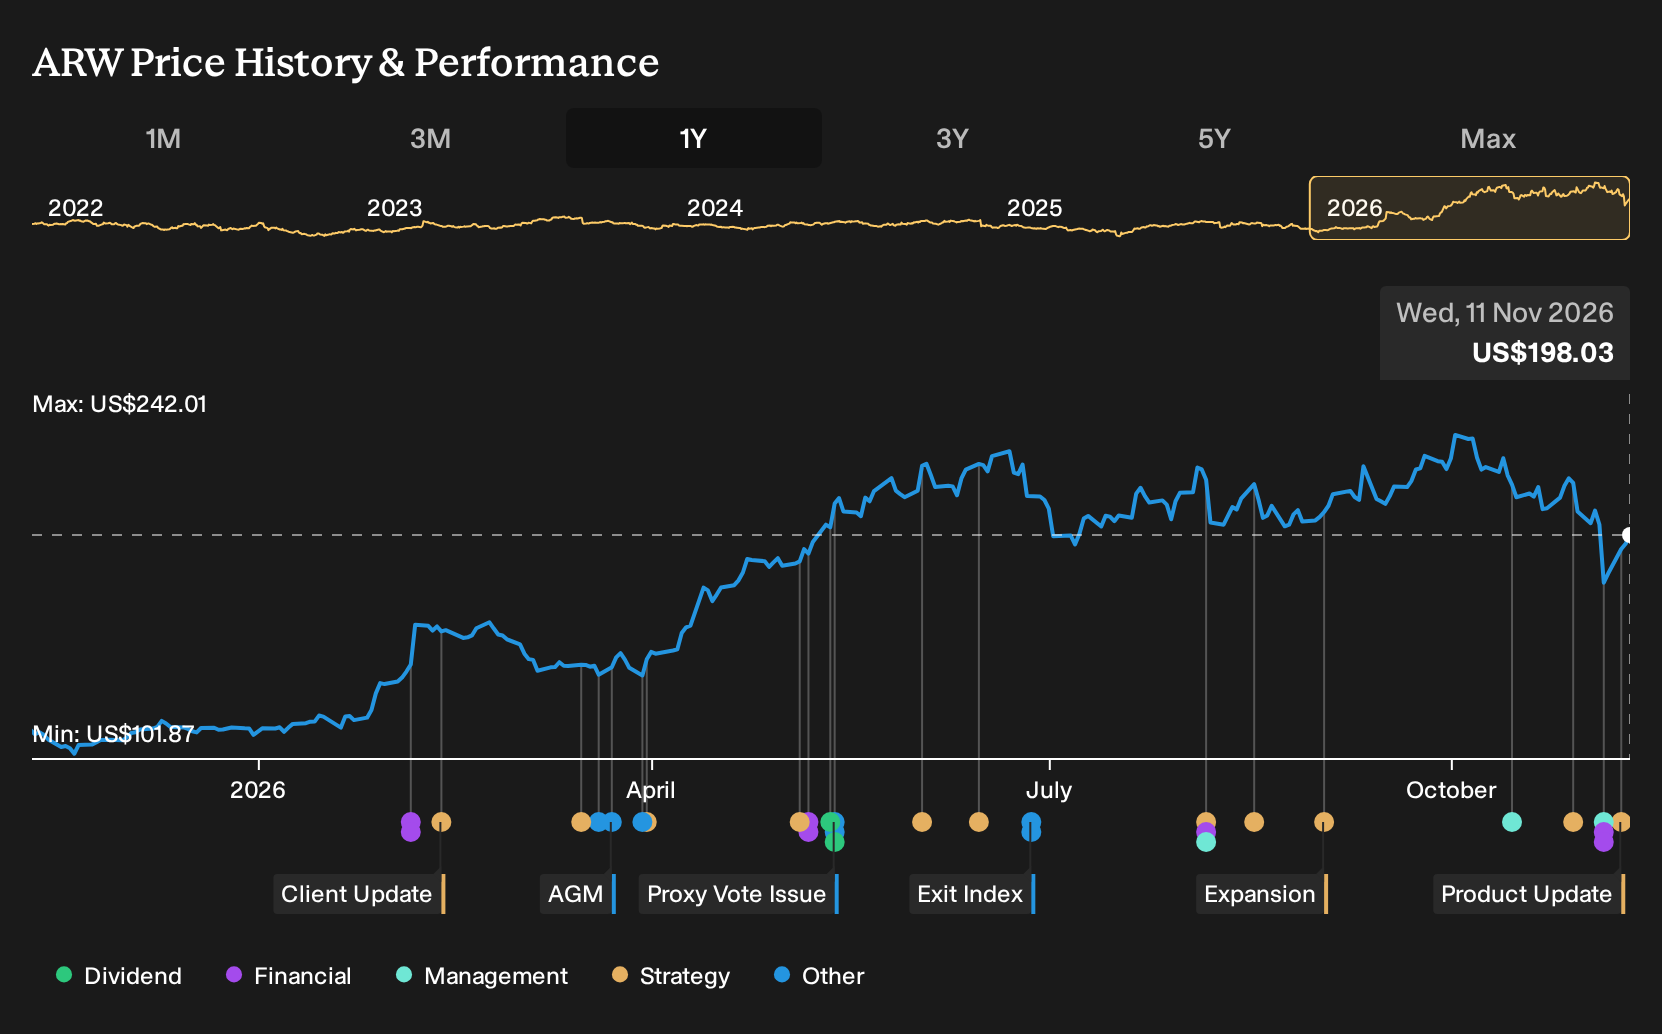
- Arrow Electronics reported third quarter 2026 sales of US$10,717.74m and net income of US$318.38m, with earnings per share from continuing operations well above the prior year. The company also issued fourth quarter guidance that outlines expected consolidated sales between US$11.55b and US$12.15b and diluted EPS of US$6.25 to US$6.45.
- Alongside these results, Arrow Electronics is launching Capstone to focus on interconnect, passive and electromechanical products and has continued share repurchases, which together highlight management attention on higher value offerings, execution support across key end markets and active capital allocation.
- We will now look at how Arrow Electronics' stronger recent earnings and guidance could influence the broader investment narrative around the business.
Arrow Electronics Investment Narrative Recap
To hold Arrow Electronics, you need to believe the business can keep turning strong demand in components, AI related infrastructure and services into steady earnings while managing restructuring noise in ECS. The analyst consensus narrative on Simply Wall St leans on higher margin services and cost discipline. Recent Q3 results and Q4 guidance largely support that operating story and do not meaningfully change the near term thesis.
Right now, the key near term swing factor is whether earnings settle near guided levels after an unusually strong first half in Supply Chain Services. The largest operational risk is that further ECS contract actions or normalization in data center activity pressure margins, especially if expectations remain anchored to early 2026 strength.
The Capstone launch looks most relevant to these catalysts because it concentrates Arrow Electronics effort around IP&E components that sit across data centers, transportation, industrial and other growth categories. A focused unit with its own brand and coverage can make it easier for customers to specify and scale IP&E, which feeds directly into the Global Components engine.
Capstone is also tightly linked to AI data centers, 800V architectures and edge processing. These areas line up with the demand drivers behind the analyst consensus narrative on Simply Wall St. Execution risk is real, since Capstone needs to integrate smoothly with Arrow Electronics broader platform while the firm is still dealing with ECS restructuring. If it performs as described it could support the push toward higher value services and more resilient margins.
Arrow Electronics' narrative references analyst expectations for revenue of US$51.8b and earnings of US$1.4b by 2029. This implies forecast earnings of US$1.4b in that year, based on revenue growing at 10.0% annually and an earnings increase of about US$400m from current earnings of US$1.0b.
Uncover why Arrow Electronics' fair value indicates a 12% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One alternate view says the real risk is Arrow Electronics relying too heavily on a few high fee Supply Chain Services and AI related ECS programs. The most cautious analysts were only modeling about US$49.8b of revenue and US$1.4b of earnings by 2029, so the Capstone launch and recent Q3 strength may eventually force that story to shift.
Explore 4 other Arrow Electronics fair value estimates, including one that suggests as much as 53% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Arrow Electronics research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Arrow Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arrow Electronics' overall financial health at a glance.
Looking For More Ideas Beyond Arrow Electronics?
Once you have formed a view on Arrow Electronics, it can help to compare that thesis with other stocks that share similar qualities or offer a very different risk profile. The Simply Wall St Screener is built for this kind of side by side review so you can pressure test your thinking rather than rely on a single story.
- If you care most about limiting downside, start by scanning a set of 30 resilient stocks with low risk scores that aim to keep volatility in check.
- For investors hunting for potential mispricing, look through a curated 32 high quality undervalued stocks that combine balance sheet strength with cash generation.
- Those who prefer steady cash payouts can focus on income opportunities through a targeted 6 dividend fortresses that may suit a yield focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com