
3 British Penny Stocks To Own In November 2026
Fresh data showing the UK economy growing 0.7% in the third quarter, helped by AI related activity, has turned the spotlight back on smaller British companies that could benefit if this trend continues. That is where low priced shares in financially healthier early stage businesses become interesting. This article walks through three such penny stocks from our quality focused screener that merit a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses with healthier balance sheets. However, if you want the names that matter most, these 17 elite penny stocks are the strongest companies we've found.
Baltic Classifieds Group (LSE:BCG)
Baltic Classifieds Group runs online marketplaces across autos, property, jobs, services and general listings, which fits neatly with the Financially Fit Penny Stocks focus on recurring, fee based digital revenue. It generated about €31 million from Auto, €26 million from Real Estate, €17 million from Jobs & Services and €14 million from Generalist portals, and the group is valued at roughly €1.1b.
The analyst consensus Narrative on Simply Wall St highlights how Baltic Classifieds Group is using its entrenched position in Baltic online marketplaces to push further into higher margin, data rich services that build on its classifieds roots.
"The very large traffic leads across Baltic Classifieds Group portals, coupled with proprietary data assets such as car history tools and valuation databases, provide a foundation for new high margin data products that can support earnings expansion."
What really matters from here is how a quietly building pressure on profitability plays out against those data driven ambitions.
If that tension between profit pressure and data ambitions has your attention, read the full narrative for Baltic Classifieds Group to see what could accelerate or stall Baltic Classifieds Group next.

Ashmore Group (LSE:ASHM)
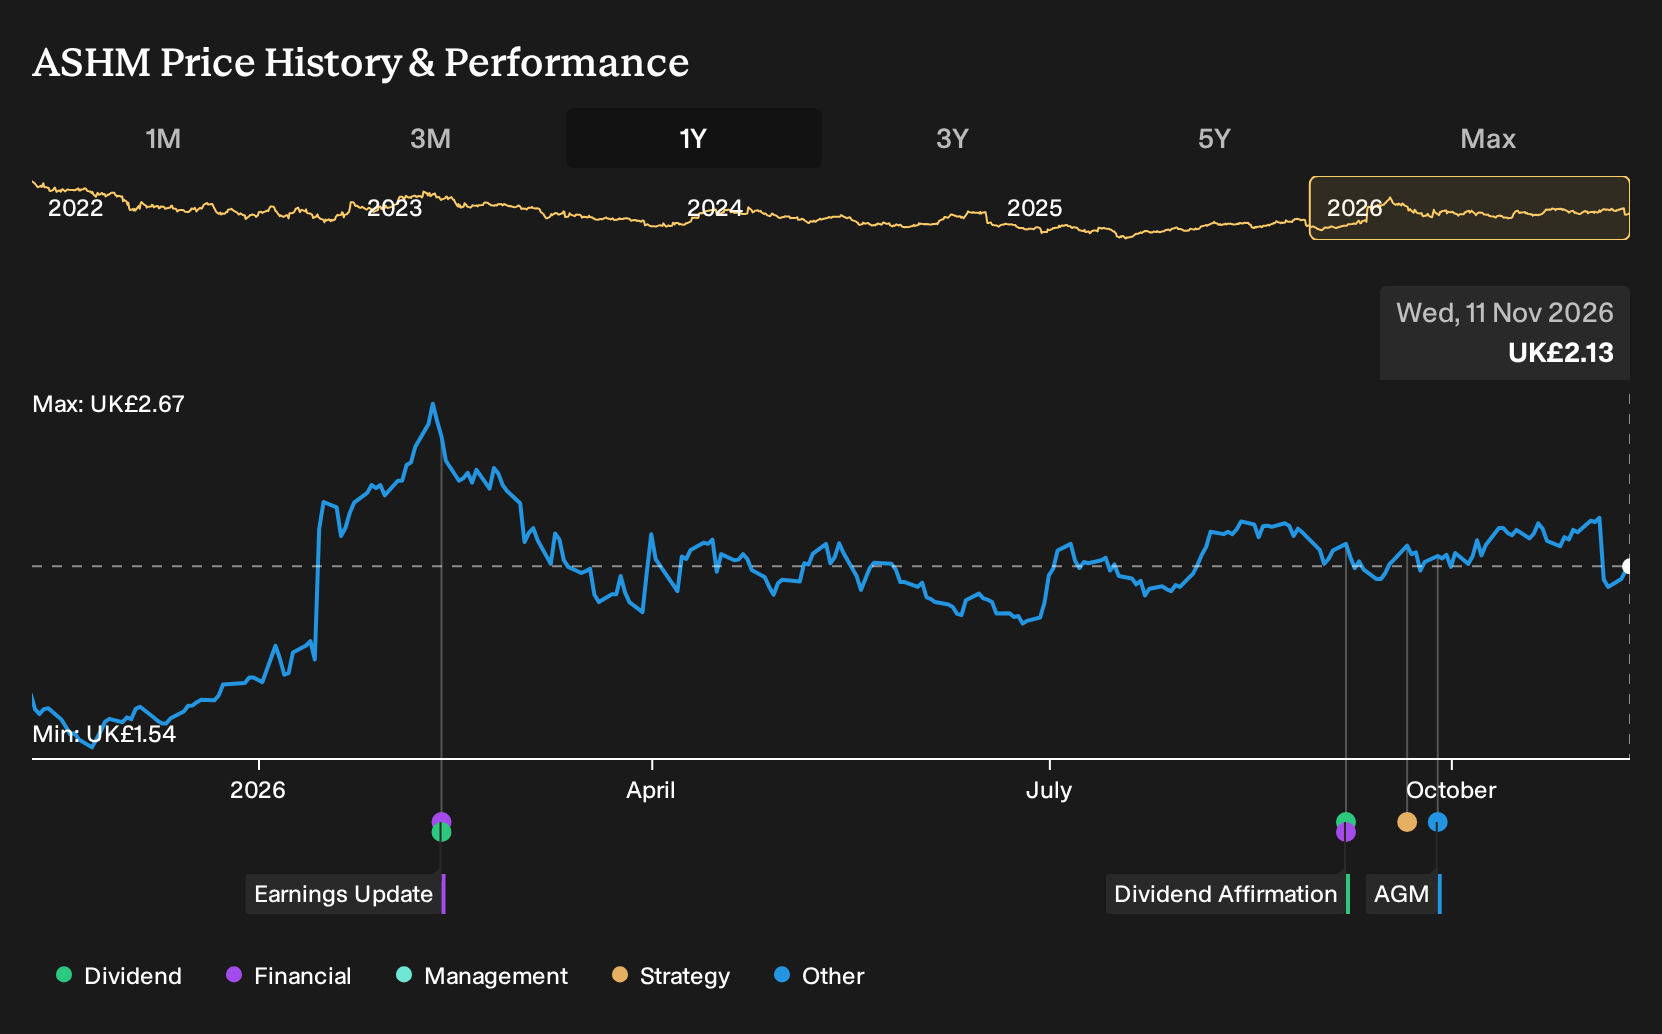
Ashmore Group gives this screener indirect access to financially healthier emerging market penny stocks, because it runs equity and bond funds that often target smaller, lower priced issuers, and earns about £139 million from investment management services on a market value of roughly £1.4b.
The analyst consensus Narrative on Simply Wall St frames Ashmore Group as a fund manager where the real story for this screener is how its emerging markets flows behave from here, not just the current yield or headline valuation.
"Client activity levels at Ashmore Group are now reflected in rising subscriptions of about $12.5b for FY 2026 and the lowest redemptions in over 10 years. Any further improvement in net flows could add to management fee revenue, while a reversal would quickly pressure fee income and keep the stock grounded."
What happens when that flow picture meets one unseen pressure on earnings quality and funding costs will matter a lot for investors watching Ashmore Group.
With that pressure point in mind, read the full narrative for Ashmore Group to see how Ashmore Group’s fee engine could accelerate or stall from here.
Currys (LSE:CURY)
Currys is a long established omnichannel retailer of consumer electronics and tech services. The iD Mobile virtual network and wider recurring service lines bring a more penny stock style growth pocket within a financially stronger group that fits this screener’s focus.
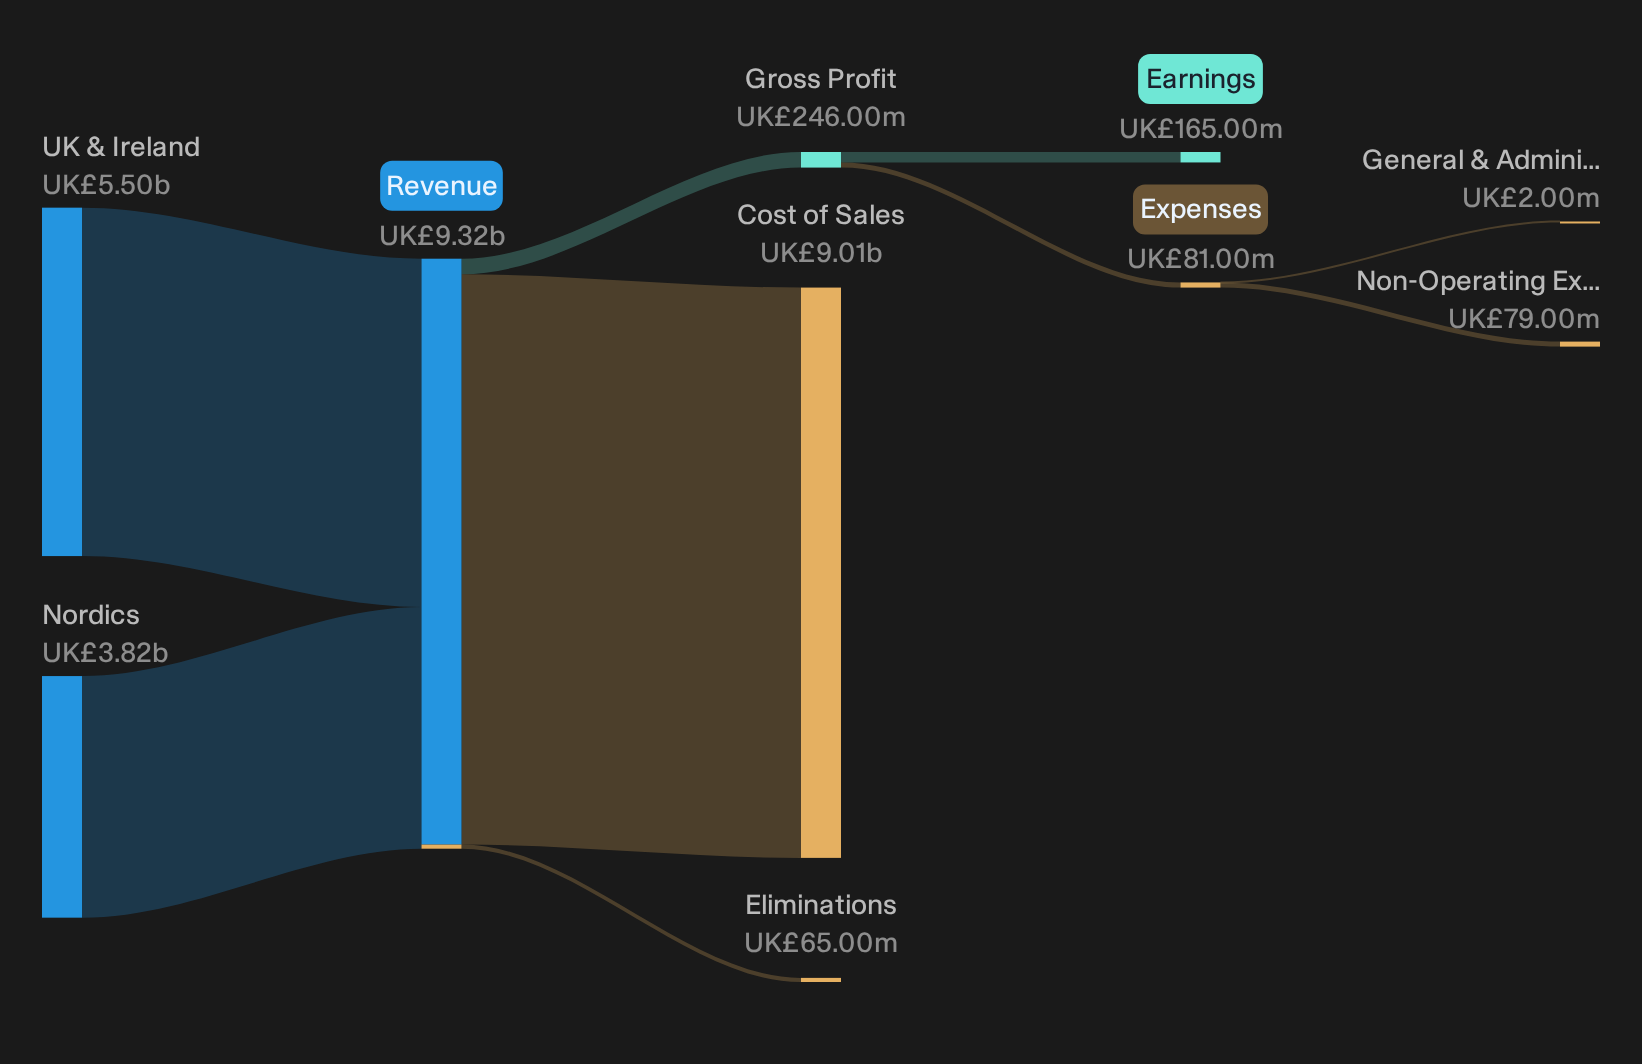
Currys generates about £5.5b from UK and Ireland and £3.8b from the Nordics, with small eliminations between regions, and the group is valued at roughly £1.5b.
Currys matters here because this is a large retailer that still has a smaller, faster moving engine inside it. The analyst consensus Narrative on Simply Wall St argues that this engine is increasingly built on recurring services and connectivity rather than one off gadget sales.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can keep lifting Currys group revenue quality and EBIT margins as more customers shift into these offers."
What really moves the dial is whether one quiet shift in how customers pay for and stay connected to their devices can keep feeding those margins.
If that quiet shift in how customers pay is what interests you, read the full narrative for Currys to see whether Currys’ service engine is accelerating or stalling next.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first and get rewarded, while slow money gets caught chasing breakouts after momentum is already flying. Scan these under the radar lists while it matters and consider your options early.
- Explore potential breakouts in smaller, cash generative businesses by screening a curated set of 17 high quality undervalued stocks before they stop looking overlooked.
- Track where real cash profits meet AI momentum by scanning 42 profitable AI stocks that aren't just burning cash that focus on companies already funding their own expansion.
- Target stability with movement by reviewing a tight 5 resilient stocks with low risk scores that focuses on resilient balance sheets while prices are still dropping under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com