
Linde (LIN) Stock May Look Fully Valued Following Strong Q3 Results
Linde has delivered a strong multi‑year run, and with the stock recently closing at US$526.55, the central question is whether that price still lines up with what its earnings can support.
- Over the past 5 years the share price has gained 70.2%, which puts real weight on whether the current earnings base and its trajectory are enough to back that move.
- Recent earnings updates point to solid profit growth and continued investment across electronics, chemicals, and energy end markets, which can shape how investors think about the durability and timing of future cash flows.
- There is a second opinion on Linde worth weighing. See what analysts think Linde's shares could be worth.
The issue now is whether Linde's current market value is appropriately anchored to the earnings it is generating today.
If you want more ideas with a similar earnings driven story to Linde, using a focused screener of 32 high quality undervalued stocks can be a useful next step in your research.
Does Linde Look Pricey on Earnings?
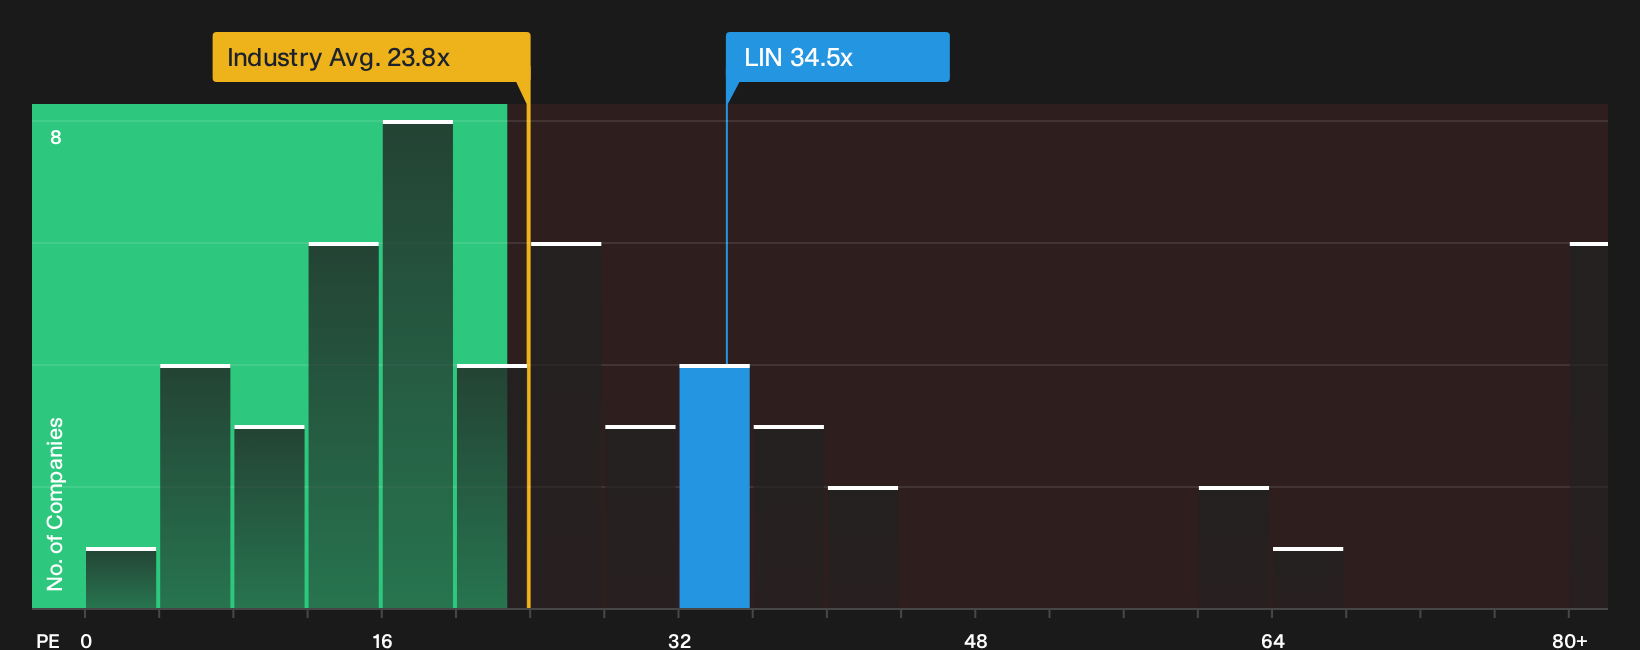
The P/E ratio is a useful lens for Linde because earnings remain a key anchor for how investors view this industrial gas business. On current figures, the stock trades on a P/E of 34.5x, compared with around 23.8x for the broader chemicals group and a peer set closer to 57.1x. This leaves Linde priced above the sector average, yet below some of the higher-valued direct comparables where investors are paying more for each dollar of profit.
Using a tailored fair multiple that reflects Linde's growth profile, profitability and risk mix, rather than raw sector averages alone, the present 34.5x sits above where this framework would place the shares and screens as overvalued on this metric. Because management is guiding to mid to high single digit EPS growth for 2026, the recent Q3 earnings strength already appears well reflected in the rating, rather than indicating a clear valuation gap. Explore the numbers behind Linde's P/E valuation.
The Linde Narrative: What Would Justify Today's Price?
Linde Narratives on Simply Wall St are built to answer the question that follows the P/E puzzle. They spell out which paths for growth, margins and earnings would need to play out for the stock to be worth much more or noticeably less than today. Where a single ratio or model gives one number, these narratives unpack the future it relies on so you can monitor whether that story continues to line up with reality over time.
One of the top narratives on Linde: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Linde converts its electronics, commercial space, helium and energy transition opportunities into higher quality earnings..."
Discover why this Narrative puts Linde at roughly fairly valued.
Before you stop at price, Linde has one more check to clear
Valuation only tells part of the story for Linde, because the research has also highlighted specific risk checks that could change how you frame the whole case. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com