
3 AI Infrastructure Stocks Investors Are Watching After The Nvidia Shock
The Nvidia shock has cracked open a rare window, with an 8% premarket drop and roughly US$590b in market value suddenly in question. Investors are being forced to rethink where the real AI infrastructure power sits. When a key supplier looks shaky, capital often goes hunting for alternatives. This article walks through three large, liquid AI infrastructure stocks exposed to this news, and explains why each could matter for your watchlist right now.
The three stocks below are just a sample, and the full screen surfaced 34 more large, liquid AI infrastructure companies with equally compelling narratives that are not covered in this article. To identify potential non Nvidia AI infrastructure leaders that fit your own risk and time horizon, head straight into the Non-Nvidia AI Infrastructure Leaders (Semiconductors & Cloud Platforms) screener.
ASRock Rack Incorporation (TWSE:7711)
ASRock Rack Incorporation designs and sells cloud computing server hardware for AI focused data centers, offering storage systems, multi node servers, and server and workstation motherboards used in large scale compute builds. The business has a market cap of about NT$38.8b.
ASRock Rack sits squarely in the Non Nvidia AI Infrastructure Leaders theme because its whole business is building the servers that run AI workloads, from GPU heavy racks to liquid cooled systems. For investors watching how Nvidia related spending could be redirected, this supplier is tied directly to the physical build out of alternative AI data center capacity. One unresolved pressure is likely to decide how much of that demand translates into durable profitability.
That unresolved pressure is exactly what you want to unpack with the 3 key rewards and 3 important warning signs (2 are major!) while the market is still recalibrating Nvidia exposure.

CDW (CDW)
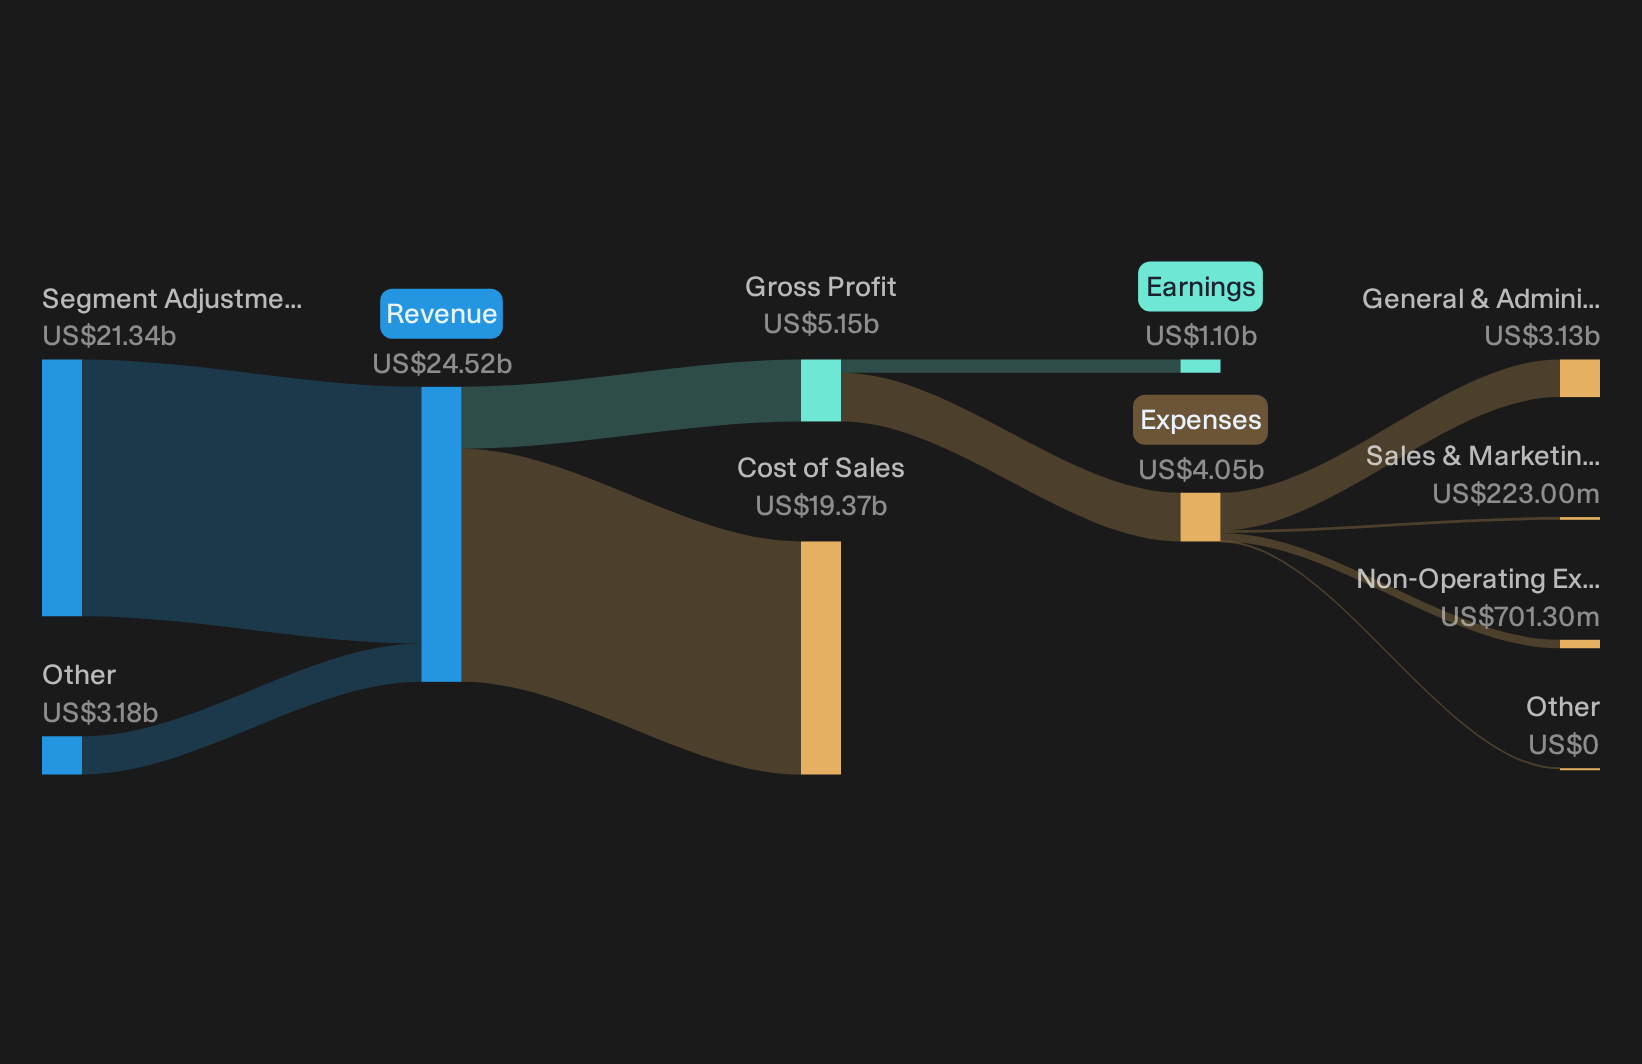
CDW is one of the clearest ways this screener taps into real world AI infrastructure spending. The analyst consensus Narrative on Simply Wall St highlights how its role as an IT integrator links everyday server and cloud orders to the bigger AI build out story.
"Accelerating adoption of AI, cloud, and cybersecurity solutions, supported by strong Q2 2026 demand for servers, storage, networking, security, software, and cloud, positions CDW to pursue larger infrastructure and security projects that can support revenue and gross profit growth as current written production converts from backlog into invoicing."
The real swing factor is how one subtle shift in where customers spend inside CDW, hardware versus higher value services, ultimately flows through to earnings power.
That mix of hardware exposure and higher margin services is exactly what the full narrative for CDW unpacks, revealing where accelerating AI demand could be masking or amplifying risk.
Realtek Semiconductor (TWSE:2379)
Realtek Semiconductor plugs into this Non Nvidia AI Infrastructure Leaders theme through the communications and connectivity chips that sit behind AI ready PCs, routers, consoles and data center equipment. The analyst consensus Narrative on Simply Wall St frames why its next product wave matters.
"Realtek Semiconductor’s move into high speed optical connectivity, including plans for a 100 gig optical PHY and development of 112 Gbps and 224 Gbps SerDes IP on 4 nm, opens a future product stream tied to AI and cloud data center demand that can add new revenue sources and support earnings diversification."
Realtek Semiconductor’s earnings power depends heavily on how one quiet shift in product mix and pricing pressure ultimately settles.
That quiet mix shift is exactly what the full narrative for Realtek Semiconductor unpacks, highlighting where accelerating AI connectivity demand could amplify opportunity or quietly cap Realtek Semiconductor’s upside.

Seeking Fresh Alternatives Before Others
Market momentum shifts fast, and fresh breakout ideas rarely stay under the radar for long. Scan these curated lists before the crowd catches on and act now.
- Target resilient compounding potential with a curated 207 resilient stocks with low risk scores that helps you focus on companies where balance sheets and risk profiles work in your favor.
- Spot early breakout trends in automation by tracking curated 86 robotics and automation stocks chosen for real world exposure to factories, warehouses, and smarter industrial systems.
- Explore potential momentum in hard assets by zeroing in on curated 33 elite gold producer stocks built around producers with meaningful exposure to the gold price cycle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com