
Tourmaline Oil (TSX:TOU) Following Strong Q3 And Higher Cash Flow Guide Looks Undervalued
Tourmaline Oil (TSX:TOU) moved into focus after reporting third quarter revenue of CA$1,852.05 million and net income of CA$641.51 million, along with a higher 2027 free cash flow estimate and rising LNG linked exposure.
The latest earnings release and higher 2027 free cash flow guide have arrived alongside firm share price momentum, with a 90 day share price return of 8.88% and a 1 year total shareholder return of 7.54%. This adds to a very large 5 year total shareholder return of 103.83%, suggesting interest in Tourmaline Oil is building rather than fading.
Scan stocks that share Tourmaline Oil's focus on cash flow and capital discipline by jumping into our hand picked list of list of solid balance sheet and fundamentals (5 results)
Bulls point to Tourmaline Oil's richer earnings, rising free cash flow estimates, and LNG exposure, while bears flag production trends and commodity risk. Which story do the current valuation markers support?
Most Popular Narrative: 9% Undervalued
Tourmaline Oil’s last close at CA$64.75 sits below the analyst consensus Narrative fair value of CA$71.07, based on a 6.44% discount rate in the analyst consensus Narrative on Simply Wall St. This valuation is tied directly to detailed volume, pricing and cash flow assumptions rather than simple multiples.
The phased Northeast BC Montney infrastructure build out, including the Aitken and Groundbirch Monias plants and associated pipelines, is expected to add 1.1 billion cubic feet per day of gas handling capacity and generate an anticipated structural incremental annual cash flow contribution of over $400 million once both phases are complete, which directly supports net margins and free cash flow.
See why 110 investors see Tourmaline Oil as 9% undervalued.
Result: Fair Value of CA$71.07 (UNDERVALUED)
Still, the story around Tourmaline Oil can change quickly if Western Canadian gas prices stay weak or if the Northeast BC build out faces longer delays and higher costs.
Find out about the key risks to this Tourmaline Oil narrative.
Another View: What Multiples Say About Tourmaline Oil
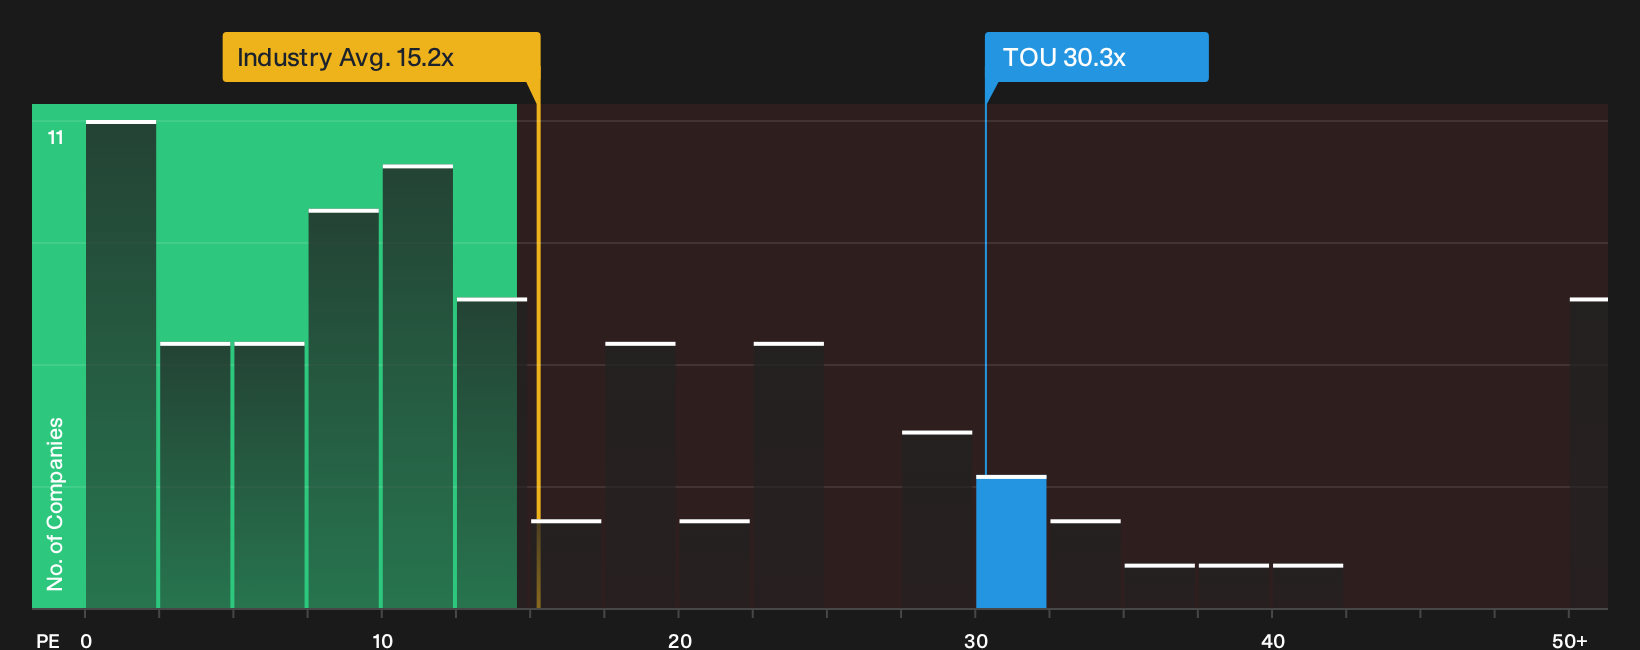
On a simple earnings multiple, Tourmaline Oil does not look cheap. The stock trades on a P/E of 30.3x, compared with 17.9x for peers and 15.2x for the wider Canadian Oil and Gas group, while the fair ratio sits lower again at 21.1x.
That spread means investors are currently paying a premium for each dollar of Tourmaline Oil’s earnings. This raises the risk that any disappointment in gas prices, project execution or cash returns compresses the P/E toward the fair ratio and sector levels. The question is whether the LNG linked volumes and infrastructure build out justify keeping that gap open.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the bullish and bearish angles around Tourmaline Oil? Move quickly from headline impressions to hard evidence and weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Tourmaline Oil?
Do not stop your research with Tourmaline Oil. Broaden your watchlist using targeted stock ideas built from the Simply Wall St screener so you stay ahead of the next move.
- Hunt for potential mispriced opportunities by scanning our highest quality value candidates in the 5 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature in the 3 dividend fortresses.
- Dial down portfolio stress and focus on resilience by assessing the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com