
Should AI Travel Threats Require Action From Booking (BKNG) Investors?
- Booking Holdings recently completed multiple euro-denominated fixed income offerings, including senior unsecured and subordinated notes across 2029, 2032, 2035, and 2038 maturities, with major global banks added as co-lead underwriters, while also reporting third quarter 2026 results and affirming a quarterly dividend.
- In the same week that Booking Holdings expanded its eurobond funding stack and showcased stable earnings and dividends, travel industry sentiment turned cautious as OpenAI’s acquisition of Odessia raised fresh questions about how artificial intelligence could reshape online travel platforms.
- This article examines how Booking Holdings' investment narrative interacts with fresh AI disruption concerns highlighted by OpenAI's Odessia acquisition.
Scan how Booking Holdings stacks up against other travel and AI exposed platforms by comparing it with 20 high quality undiscovered gems that may be flying under most investors' radar.
Booking Holdings Investment Narrative Recap
To own Booking Holdings, you need to believe its global platforms can keep converting travel demand into high quality earnings while managing working capital swings that, as John_Eric, an investor in the Simply Wall St Community, argues, can blur the true cash picture. The latest quarter showed revenue of US$8,893 million and net income of US$2,717 million, which keeps the earnings engine very relevant to the thesis.
In the short term, the key operational swing factor is how travel volumes and mix feed into that cash float and reported profit, especially with AI driven competition raising questions around customer acquisition costs. The biggest current risk sits in execution around regulation, fees and high debt levels, rather than the eurobond activity, which does not materially change the near term business catalyst.
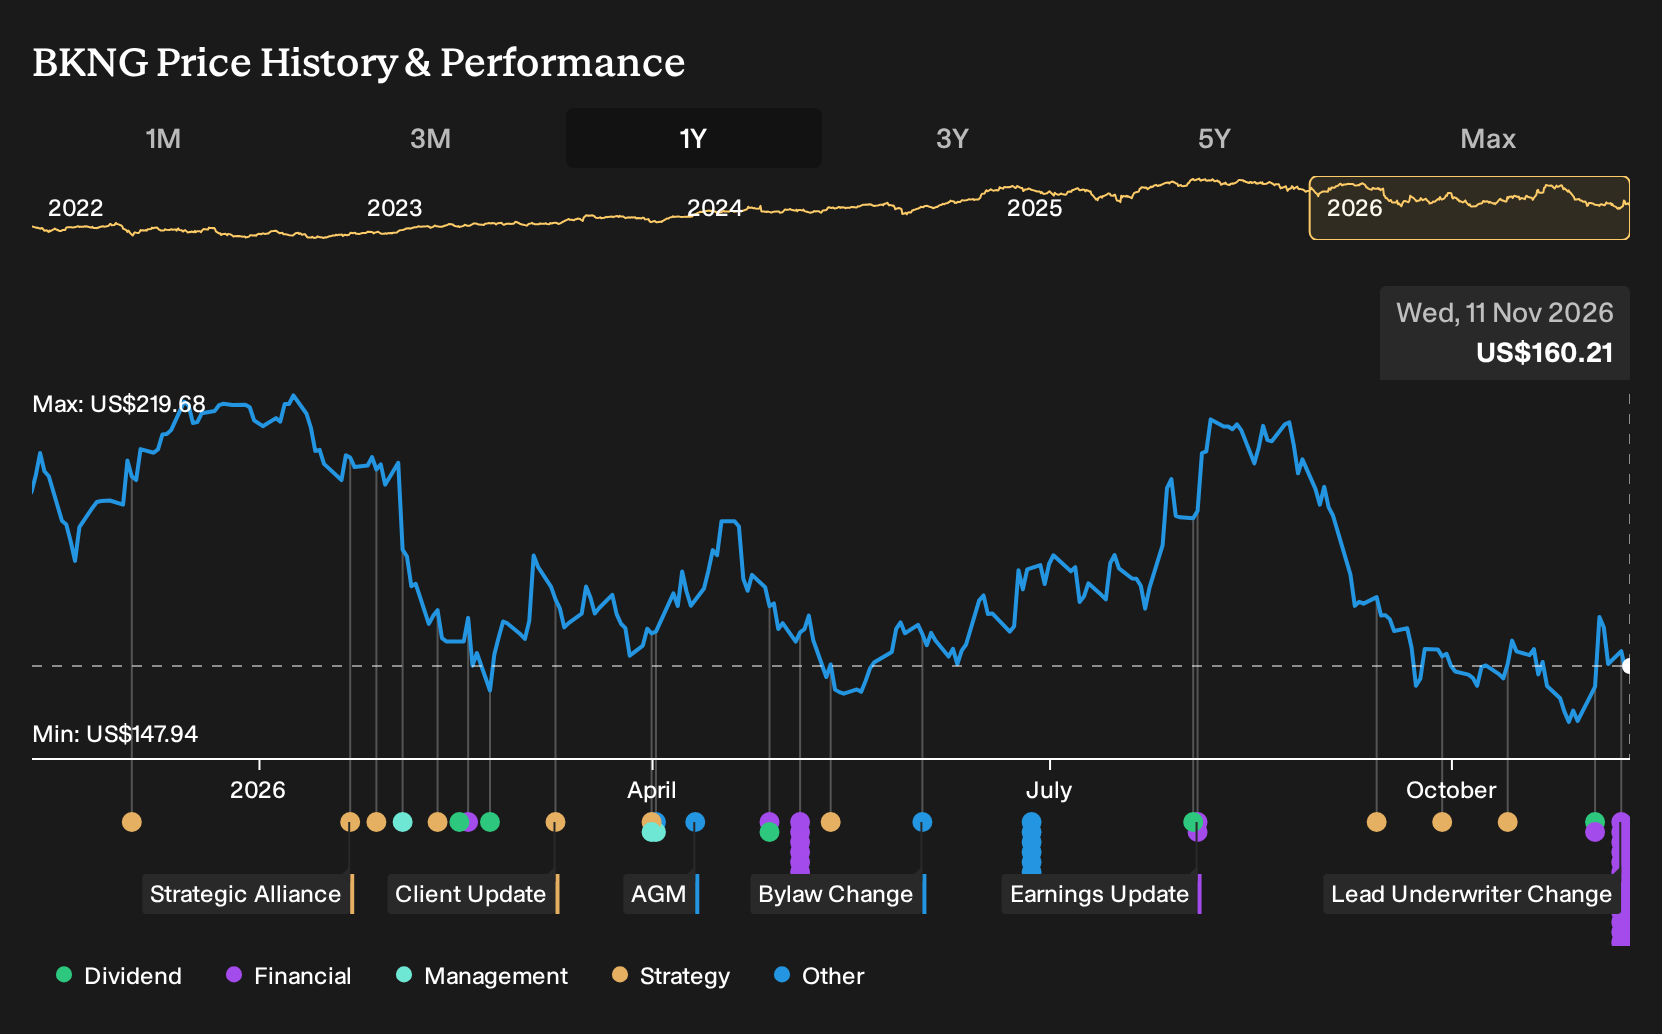
The clearest link between the big funding news and the day to day Booking Holdings story is the cluster of euro denominated fixed income offerings in November 2026, such as the €750 million 5.00% Notes due 2038 and €800 million 4.375% Notes due 2032. These sit alongside completed issues like the €1.25 billion 3.950% Notes due 2029 and €750 million 4.750% Notes due 2035.
Multiple tranches, largely senior and unsecured, and a wide syndicate of co lead underwriters point to an intent to keep a sizeable debt stack in place, which matters for a business already flagged as carrying a high level of borrowings. For you as a shareholder, the link back to catalysts is simple. Earnings quality and regulatory outcomes need to keep supporting interest coverage and balance sheet flexibility while AI and competition pressures play out.
On John_Eric’s updated model, Booking Holdings reaches a fair value of US$322.34 a share by applying 11.3% annual revenue growth and a 25.5% future profit margin. That combination is treated as the narrative’s own central path for how the cash flow story should mature over time.
Uncover how Booking Holdings' fair value indicates a 101% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate angle on Booking Holdings focuses less on float risk and more on an AI driven earnings catalyst. The most optimistic analysts were penciling in revenue of US$38.8b and earnings of US$11.8b by 2029 before this bond flurry, assuming AI tools and new services lift profitability. Those expectations could shift, so explore several viewpoints before deciding what you believe.
Explore 8 other Booking Holdings fair value estimates, including one that suggests as much as 3311% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Booking Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Booking Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Booking Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Booking Holdings?
Once you have formed a view on Booking Holdings, it often helps to compare that thesis with other companies that fit clear financial filters. The Simply Wall St Screener can surface a focused set of candidates so you spend less time sifting and more time weighing the few that match your approach.
- If resilience matters most to you, start with a group of companies that combine lower risk scores with steadier profiles by checking out 30 resilient stocks with low risk scores.
- For readers who care about balance sheet strength and fundamentals first, the screener highlighting a list of solid balance sheet and fundamentals (23 results) can point you toward businesses built on firmer financial footing.
- Income focused investors can zero in on higher yielding payers by scanning through a curated set of 6 dividend fortresses that may suit a dividend oriented approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com