
Learn Why The Bull Case For Agnico Eagle Mines Stock Could Change Following Cost Guidance Pressure
- Agnico Eagle Mines reported third quarter results that combined higher all in sustaining costs of $1,648 per ounce with production guidance toward the lower end of its range and cost guidance toward the upper end, while also expanding its revolving credit facility from $2 billion to $3 billion to fund capital projects.
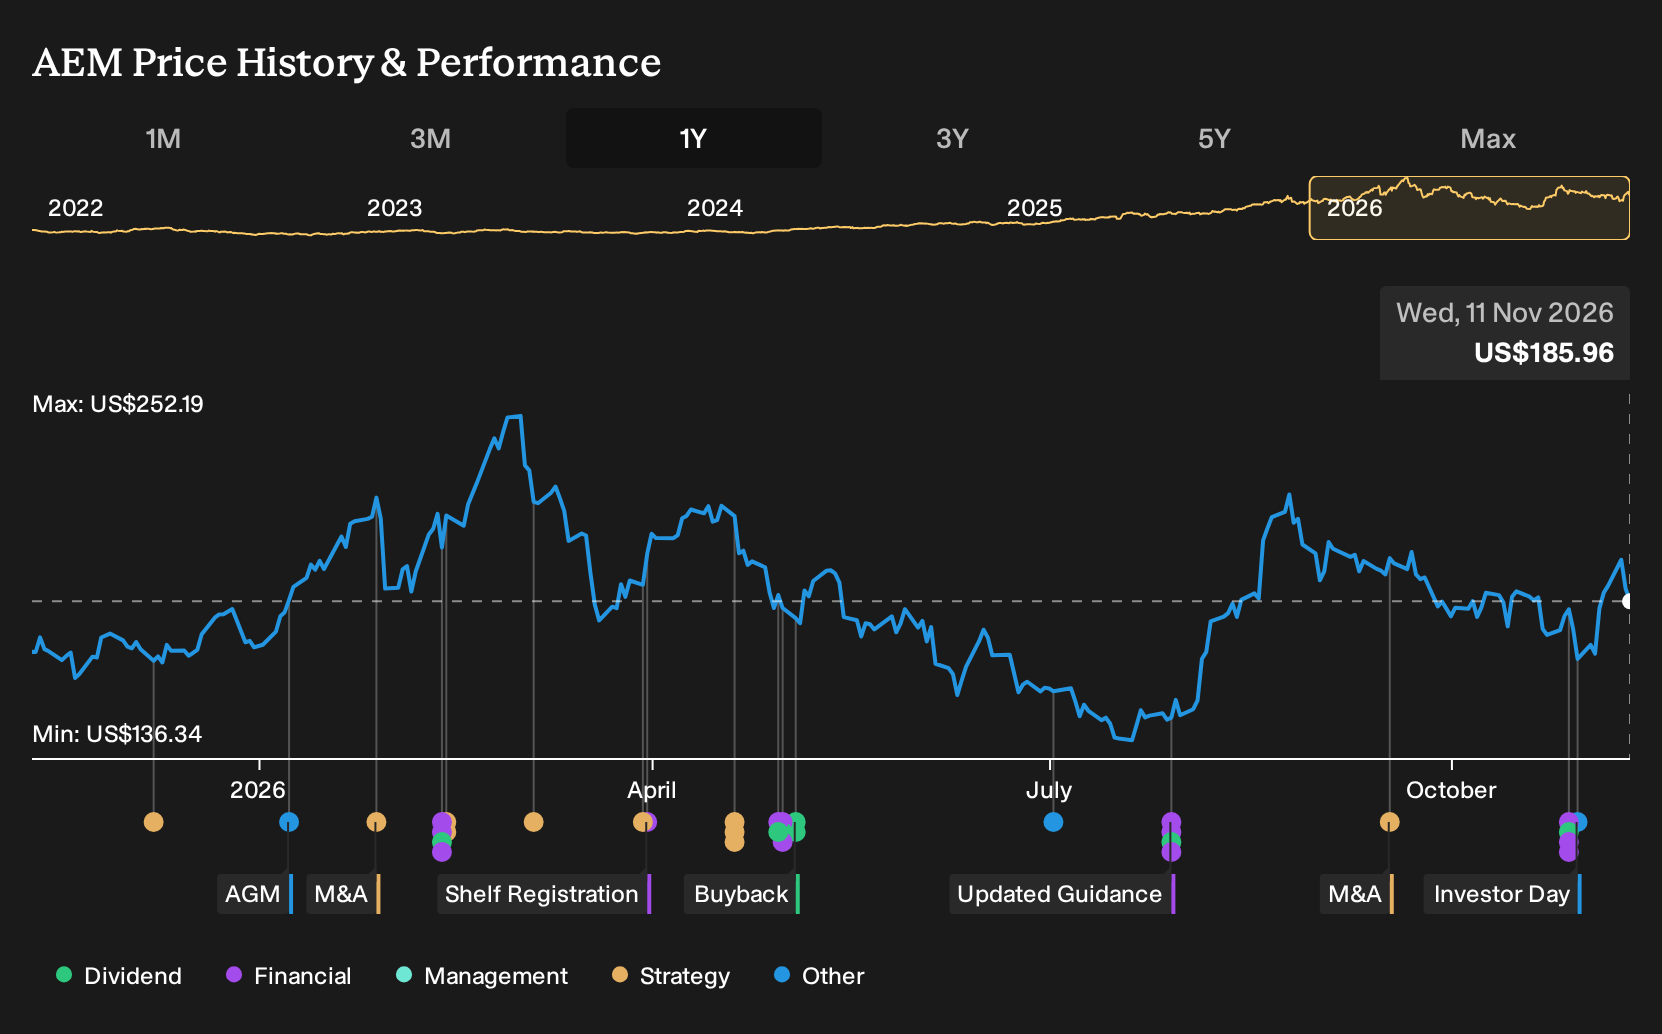
- Investors are weighing Agnico Eagle Mines' higher operating costs and inflation driven gold price swings against global bullion ETF inflows outside the U.S. These factors together shape how resilient the miner’s cash generation could be under sustained cost pressure.
- We will now look at how Agnico Eagle Mines' rising all in sustaining costs may influence the broader investment narrative around the business.
Scan beyond Agnico Eagle Mines and stress test your thesis across our hand picked list of 33 elite gold producer stocks that are also wrestling with cost inflation and shifting bullion flows.
Agnico Eagle Mines Investment Narrative Recap
Owning Agnico Eagle Mines today means believing the business can convert its diversified mine portfolio into resilient cash generation despite rising all in sustaining costs. According to lenny67, an investor in the Simply Wall St Community, the real swing factor is how effectively Agnico fills future production and processing gaps in Quebec while keeping margins in check.
The latest quarter points to higher AISC, production near the low end of guidance and cost guidance near the top, which keeps cost inflation as the biggest short term risk. The key near term catalyst is how Agnico manages asset planning at Canadian Malartic and other sites while gold price volatility and ETF flows affect sentiment around the sector.
The upsized revolving credit facility from US$2b to US$3b is the announcement that matters most right now. It gives Agnico more flexibility to fund capital projects and potential regional solutions at assets like Canadian Malartic without immediately relying on equity markets, which can be important when investors are already focused on higher operating costs.
Seen alongside the industry wide rise in production expenses and the recent volatile reaction to U.S. inflation data and rate expectations, the bigger facility sharpens the execution test. Management still has to show it can deploy that extra firepower into projects that support free cash flow while investors weigh rising AISC, forecast earnings pressure and the current P/E that screens below broader U.S. markets.
On those assumptions, the narrative from lenny67 reaches its own fair value of $123,914 by applying a very rapid 311.0% yearly revenue expansion, along with a future profit margin of 39.5%. Together, these figures imply much higher estimated earnings power for Agnico Eagle Mines over time.
Uncover why Agnico Eagle Mines' fair value indicates a 66535% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Agnico Eagle Mines, the bullish twist in the alternate narrative is production growth rather than cost pressure. The most optimistic analysts were pencilling in 6.1% annual revenue growth and earnings of about US$5.7b by 2029 before this quarter’s cost surprise. You can treat those pre news forecasts as one possible path and then compare them with your own expectations.
Explore 5 other Agnico Eagle Mines fair value estimates, including one that suggests as much as 66535% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Agnico Eagle Mines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agnico Eagle Mines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agnico Eagle Mines' overall financial health at a glance.
Looking for more investment ideas beyond Agnico Eagle Mines?
Once you have a view on Agnico Eagle Mines, it can help to cross check that thesis against other businesses with different balance sheets, dividend profiles and risk levels. The Simply Wall St Screener gives you a quick way to line up those comparisons and spot where the risk and reward trade off looks most compelling to you.
- If capital preservation and stability matter most to you right now, start with a group of 30 resilient stocks with low risk scores that our models flag with more resilient profiles.
- If you want to focus on financial strength and less leveraged operations, you can filter for a list of solid balance sheet and fundamentals (23 results) and see which businesses hold up under tougher conditions.
- If you are hunting for under followed opportunities with stronger fundamentals, cast a wider net across 20 high quality undiscovered gems that might not yet be on the market's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com