
Updated Guidance Could Be A Game Changer For Ingredion Stock (INGR)
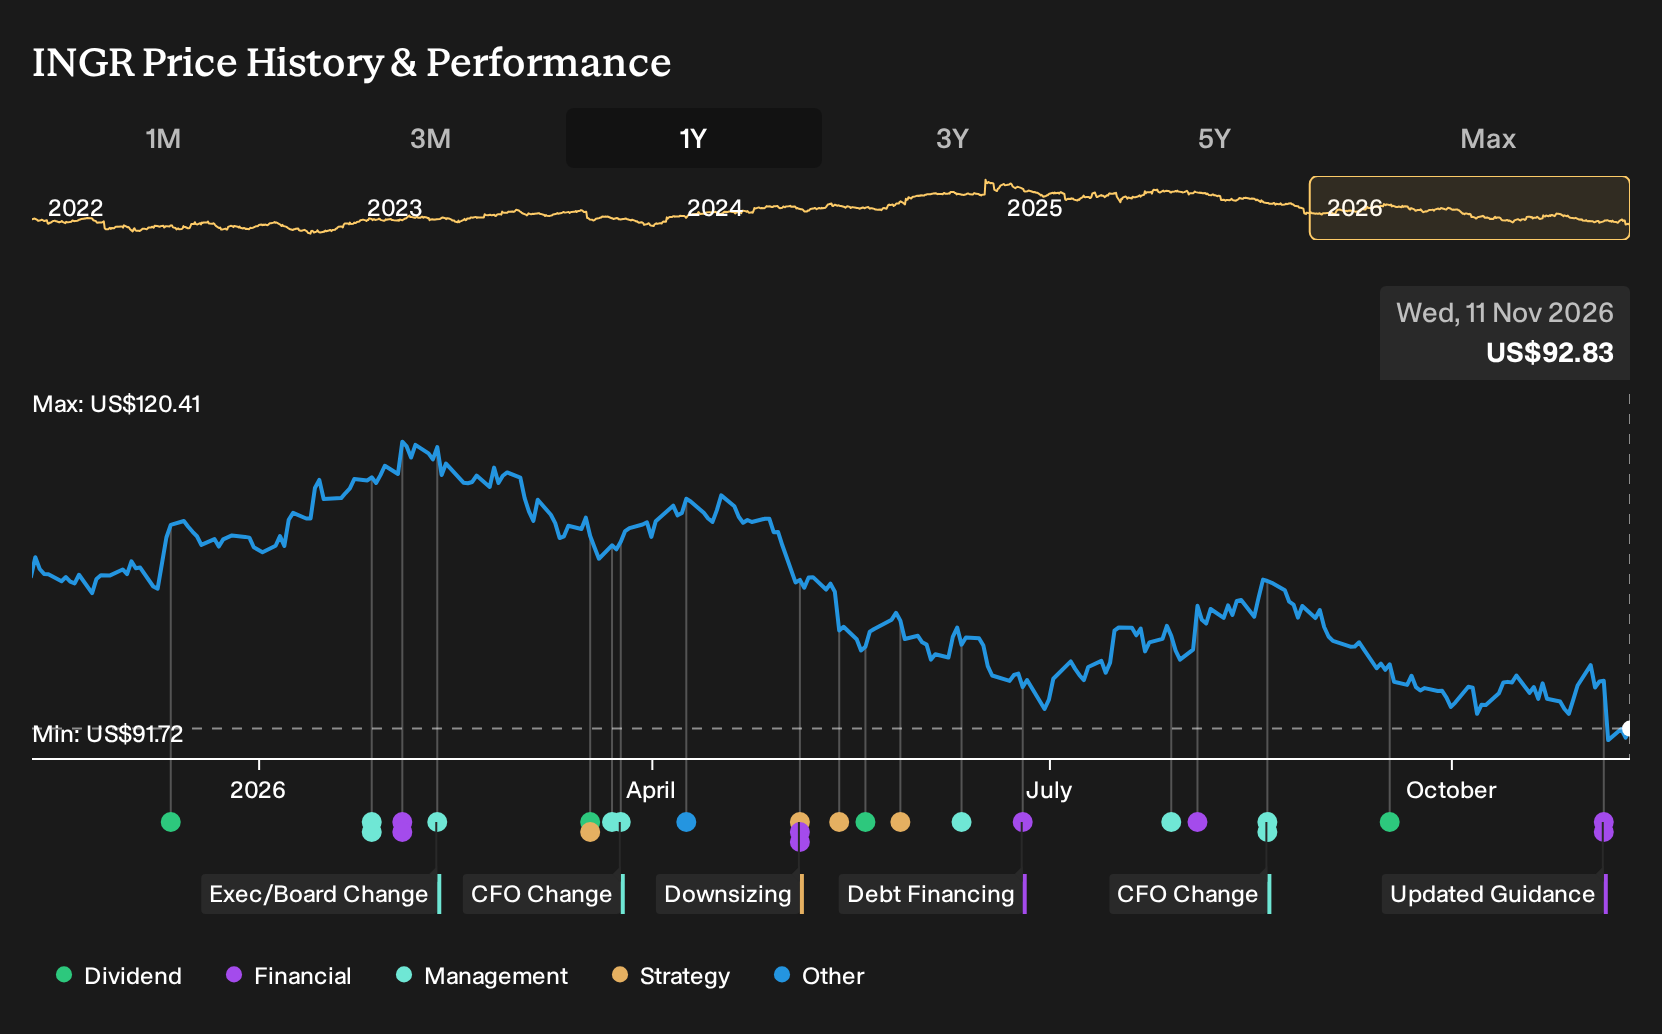
- Ingredion reported third quarter 2026 results with sales of US$1.79b and diluted EPS from continuing operations of US$2.23, and updated full year guidance to reported diluted EPS of US$8.04 to US$8.49 with flat net sales and lower reported operating income.
- The company expects volume growth and favorable foreign exchange in 2026 to be offset by a weaker price mix and the sale of its majority stake in the Pakistan business, which highlights the pressure on Ingredion's profitability despite a relatively stable top line outlook.
- We will examine how Ingredion's longer term earnings and cash flow narrative is affected by guidance for lower reported operating income.
Scan how Ingredion's guidance compares with peers facing similar pricing and margin pressure by reviewing the hand-picked 32 high quality undervalued stocks, which may offer sturdier earnings support.
Ingredion Investment Narrative Recap
To stay invested in Ingredion, you need to believe the shift toward higher value ingredients can matter more than near term pricing headwinds. AgWiz, a Simply Wall St Community investor who wrote the Narrative, argues the attraction is durable demand, customer relationships, free cash flow and dividends rather than fast expansion. The new 2026 outlook, with flat net sales and lower reported operating income, clearly pushes margin recovery further out.
The most important short term swing factor is whether Ingredion can stabilize profitability while mix improves and the Pakistan exit beds in. Guidance for a low double digit decline in reported operating income keeps pressure on execution and cost discipline. The biggest risk right now is that weaker price mix and integration work around Tate & Lyle slow any improvement in earnings quality.
The updated guidance is the key announcement to focus on. Management now expects 2026 reported diluted EPS of US$8.04 to US$8.49 with flat net sales, despite some help from volume growth and foreign exchange. That framing aligns with AgWiz’s view that the story rests more on business quality and mix shift than on rapid top line expansion.
For catalysts, the guidance for reported operating income to be down low double digits is central. It underlines that any re rating case leans on Ingredion progressing its specialty ingredients transition, integrating Tate & Lyle and protecting returns while volume recovers. Execution against those operational goals, not just headline EPS, is likely to drive how investors reassess risk and reward from here.
AgWiz’s narrative arrives at a fair value of US$88.23 for Ingredion by applying a discounted cash flow style view. This view assumes revenue growth of 2.3% a year and a future profit margin of 9.4%, which together support a higher intrinsic value than current earnings guidance alone might imply.
Uncover why Ingredion's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on Ingredion puts much more weight on margin pressure. The most cautious analysts were modelling revenue of about US$7.5b and earnings of roughly US$785.9m by 2029, with EPS near US$12.56, before this guidance. That is a tighter and more muted path for profitability. Use that as a contrast point and explore how differently others frame the same data.
Explore 3 other Ingredion fair value estimates, including one that suggests it could be worth just $88.23.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ingredion research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Ingredion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingredion's overall financial health at a glance.
Looking for more investment ideas beyond Ingredion?
If Ingredion has sharpened your focus on quality and earnings resilience, it can be useful to line it up against other opportunities that fit clear, rules-based filters. The Simply Wall St Screener helps you quickly scan for stocks that match the kind of balance sheet strength, income potential, or risk profile you want to prioritize next.
- For investors who care most about dependable finances and staying power, start with a curated list of solid balance sheet and fundamentals (23 results) that keep debt and balance sheet risk in check.
- If income is your anchor, compare Ingredion with a hand picked set of companies offering 6 dividend fortresses that aim to combine meaningful yield with resilience.
- When you want something off the beaten path, look through a focused collection of 20 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com