
3i Group Stock Falls Into Focus After Dividend Rise And Lower Half Year Profit
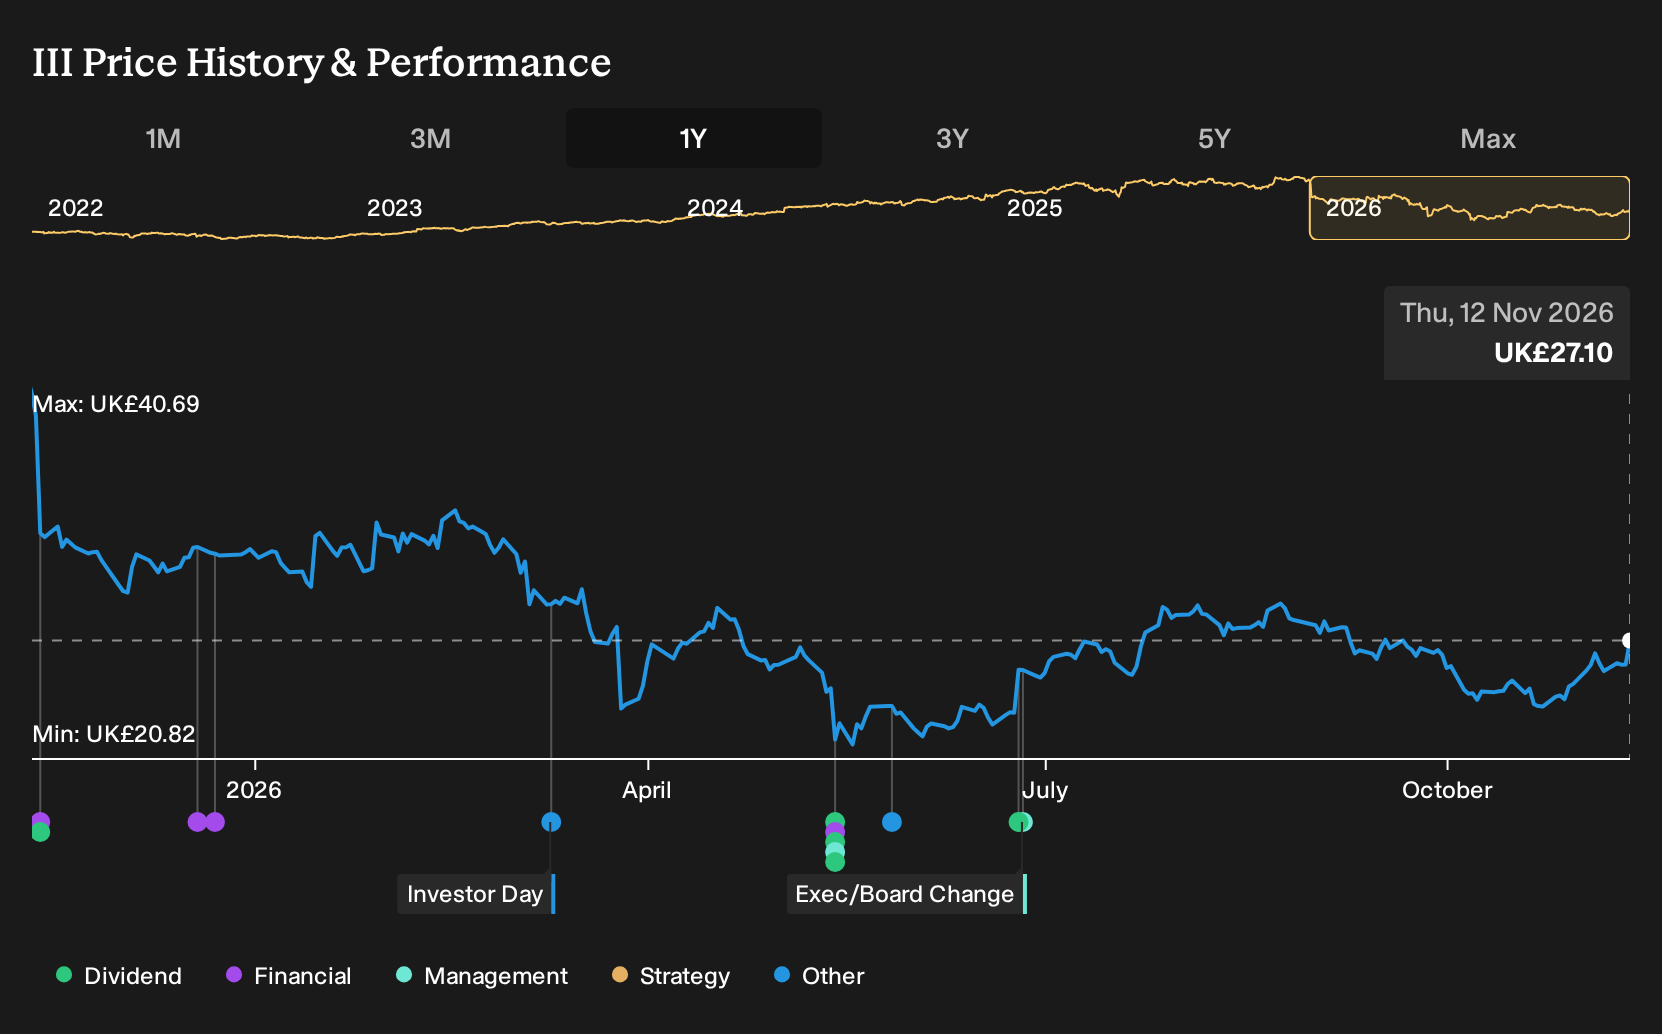
- 3i Group reported half year net income of £1,619 million for the six months to 30 September 2026, down from £3,287 million a year earlier, while also proposing a first FY2027 dividend of 42.25p per share in line with its stated policy.
- The proposed £426 million first FY2027 dividend, set against lower earnings, highlights management’s focus on predictable shareholder distributions supported by portfolio EBITDA and cash generation instead of short term profit swings.
- This article will examine how 3i Group's investment narrative is shaped by this higher first FY2027 dividend despite weaker half year earnings.
Scan how 3i Group’s dividend-led approach compares with other income ideas by reviewing our hand picked 5 dividend fortresses alongside this update on earnings and payouts.
3i Group Investment Narrative Recap
To own 3i Group, you need to be comfortable with an investment model that converts volatile fair value gains into relatively steady dividends over time. The analyst consensus Narrative on Simply Wall St focuses on expanding private equity and infrastructure portfolios as the main driver, while the latest half year shows how accounting profit can swing even when the dividend path does not.
The key short term catalyst still lies in portfolio EBITDA and cash generation, especially from assets like Action and infrastructure holdings. The biggest near term risk remains external, in the form of currency movements, political uncertainty in Europe and sector specific pressure in areas such as automotive and North American white collar recruitment.
The most relevant fresh datapoint for that thesis is the first FY2027 dividend of 42.25p per share, equal to half of last year’s total payout, alongside half year net income of £1,619 million. The gap between earnings volatility and dividend progression highlights that management is running a through cycle income framework rather than tying distributions tightly to a single period’s profit.
For investors considering this approach, the operational question is whether portfolio companies can keep funding this policy through cash flows and realizations if returns moderate. Currency translation losses, higher leverage at Action and any weaker conditions in Europe or end markets like recruitment could strain that balance, while successful investment and realization activity would support the existing dividend led story on 3i Group.
3i Group's narrative projects £8.6b revenue and £6.2b earnings by 2029. This implies 9.2% yearly revenue growth and an earnings decrease of £0.1b from £6.3b today.
Uncover why 3i Group's fair value indicates a 42% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are seeing one clear tension. The consensus narrative leans on Action as a powerful earnings engine, while the most cautious analysts worry that slower like for like growth there could restrict 3i Group’s future dividend headroom. Those lower forecasts still assumed revenue of about £7.3b and earnings near £6.7b by 2029. This dividend move may prompt some to revisit those numbers.
Explore 3 other 3i Group fair value estimates, including one that suggests it could be worth just £33.74!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your 3i Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for 3i Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 3i Group's overall financial health at a glance.
Looking for more investment ideas beyond 3i Group?
Once you have a view on 3i Group, it can help to set it beside other opportunities that match different risk and income profiles. The Simply Wall St Screener lets you compare companies on the same metrics that matter here, from balance sheet strength to income potential.
- If capital preservation sits high on your list, scan a focused set of resilient companies with relatively low risk profiles through the 5 resilient stocks with low risk scores.
- For investors who care most about quality at a sensible price, line up potential opportunities by reviewing the 15 high quality undervalued stocks and see which businesses currently look attractively priced.
- Income focused readers who like 3i Group’s distribution story can broaden their watchlist by checking out a curated list of solid balance sheet and fundamentals (9 results) that can support dividends through tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com