
Earnings Beat Could Change The Case For Mercury Systems Stock (MRCY)
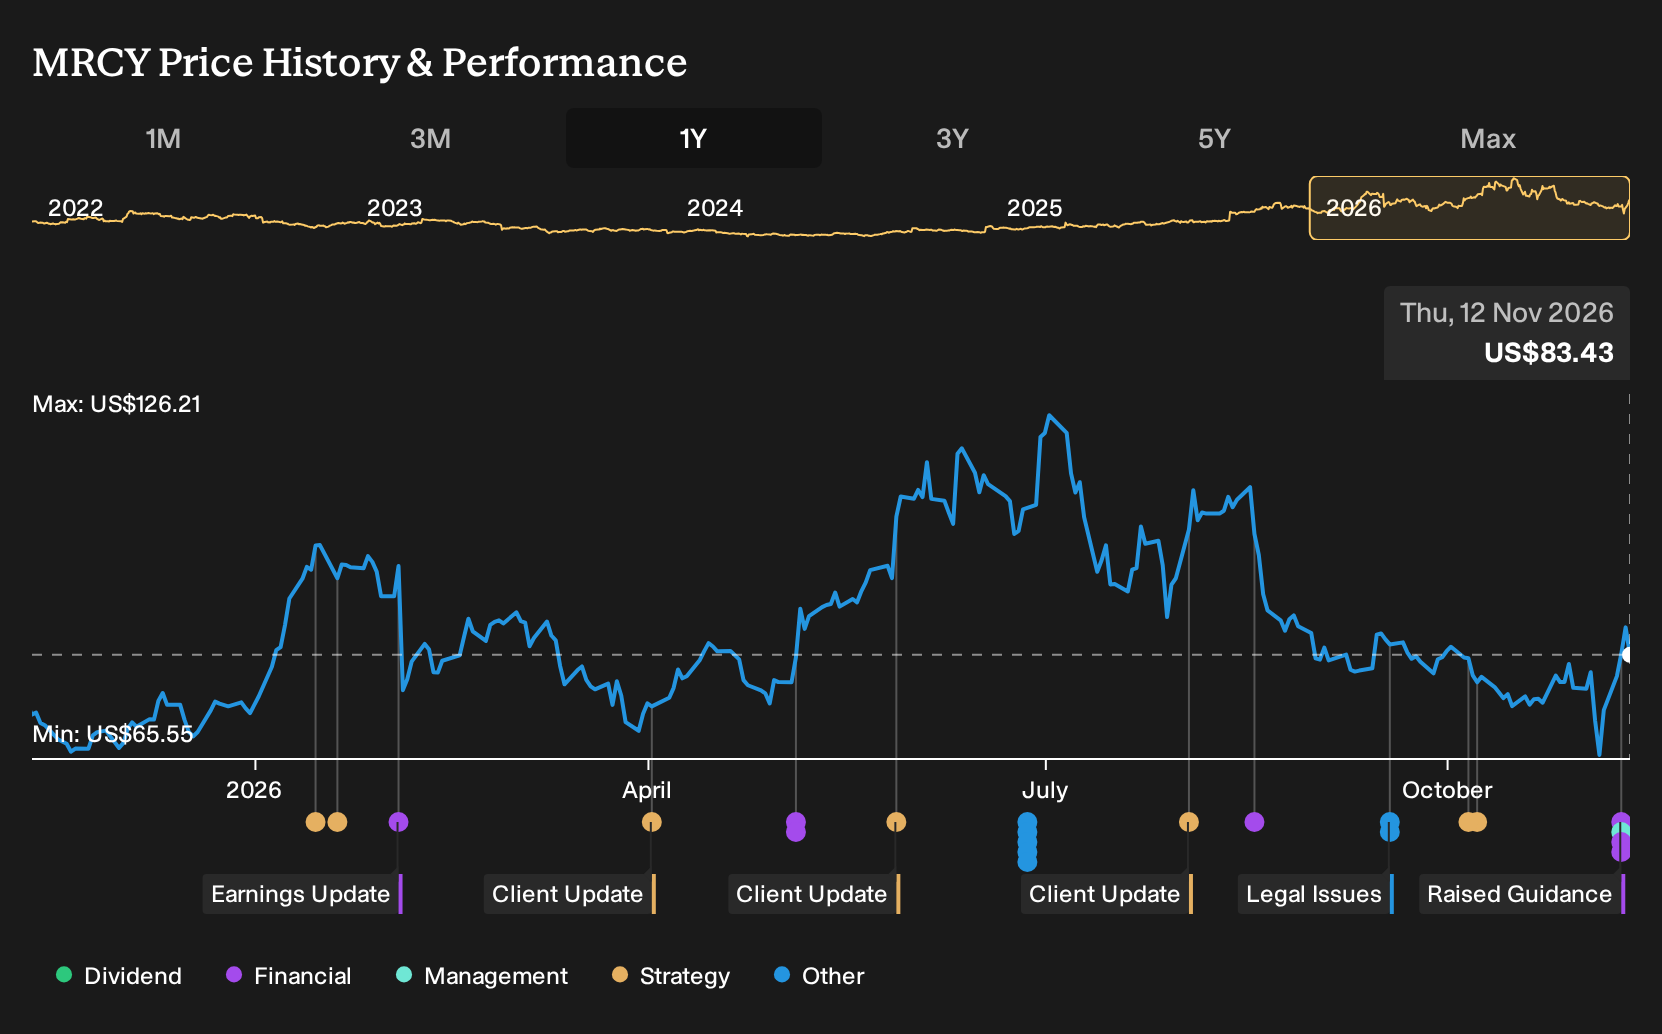
- Mercury Systems reported fiscal Q1 2027 results with revenue of US$253.15 million and adjusted EPS of US$0.52, beating analyst expectations. Management raised full year guidance, with revenue approaching US$1.1 billion and adjusted EBITDA of about US$210 million.
- Record Q1 bookings of roughly US$370 million and a backlog above US$2 billion suggest demand visibility that directly supports Mercury Systems' raised margin and earnings targets.
- The focus now turns to how Mercury Systems' record backlog and upgraded 2027 guidance could reshape the longer term investment narrative.
Mercury Systems Investment Narrative Recap
To own Mercury Systems, you need to believe the record backlog above US$2b and record bookings can keep feeding higher margin production while the business works through its GAAP loss profile and modest free cash flow conversion. The near term swing factor is execution on these new awards, since management expects revenue to increase through the rest of fiscal 2027.
The biggest near term risk is that double digit growth ambitions and margin targets do not translate into stronger cash generation, given free cash flow had already fallen in FY26. If higher inventory, facility spending or AI investments keep cash conversion subdued, the analyst consensus Narrative on Simply Wall St around compounding earnings power could be challenged.
The raised full year guidance on November 10, with Mercury Systems now targeting double digit revenue growth and total sales approaching US$1.1b in 2027, is the most relevant update. This sits directly on top of the record US$253.15 million Q1 revenue, US$370 million of bookings and the larger backlog, so it tightens the focus on delivery rather than order intake.
For you, that guidance raises the stakes on execution and risk. Management is effectively tying the Q1 beat and stronger contract visibility to a bigger earnings ambition in 2027, while the firm is still coming off recent GAAP losses and softer free cash flow. Any stumble on production ramps, program mix or cost control would quickly test that outlook.
Mercury Systems' narrative projects US$1.3b revenue and US$115.7 million earnings by 2029. This assumes 10.1% yearly revenue growth and an earnings improvement of roughly US$145 million from current earnings of a US$29.7 million loss.
Uncover why Mercury Systems' fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Mercury Systems through the upside from the expanded Phoenix facility and AI enabled factory tools. Before this Q1 beat and raised guidance, they were already pencilling in revenue of about US$1.4b and earnings of roughly US$82 million by 2029. That is a much punchier scenario than the baseline. It shows how far opinions can spread, so treat this quarter’s news as a prompt to compare several narratives rather than settle on a single view.
Explore 4 other Mercury Systems fair value estimates, including one that suggests as much as 48% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Mercury Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mercury Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercury Systems' overall financial health at a glance.
Looking for more investment ideas beyond Mercury Systems?
If the Mercury Systems story has sharpened your thinking about contract visibility, balance sheets and execution risk, you can apply that same lens to a wider watchlist. The Simply Wall St Screener lets you quickly filter for fundamentals that fit your own playbook rather than relying only on consensus views.
- If you care about downside protection first, start with companies that score well on resilience and capital strength by running a 30 resilient stocks with low risk scores that matches your risk tolerance.
- If dependable income matters more than headline growth, narrow in on payouts that appear more robust by scanning a curated set of 6 dividend fortresses with yields that are meaningful for your objectives.
- If you want future Mercury Systems style stories before they are widely discussed, focus on underfollowed businesses with solid numbers using a focused list of 20 high quality undiscovered gems that already show quality under the hood.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com