
BP (LSE:BP.) Could Be 14% Undervalued As Dividend And Q3 Results Land
BP (LSE:BP.) just combined a fresh interim dividend declaration with updated production guidance and detailed third quarter 2026 results. This gives investors a dense snapshot of cash returns, output expectations and recent financial performance.
BP’s share price has slipped around 7.1% over the past month but is still up roughly 8.4% over 90 days and has a year to date share price return of about 29.5%. The 5 year total shareholder return of roughly 115.9% points to strong long term compounding for investors who have stayed invested through past cycles.
Scan beyond BP and compare this update with other large energy players by running the hand picked 5 resilient stocks with low risk scores that focus on resilience and steadier risk profiles.
After a near 30% gain this year and a recent pullback, BP now sits at an awkward crossroads. Are investors already paid for the story, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 14% Undervalued
BP closed at £5.67 against a narrative fair value of £6.61, which implies the shares trade at a material discount. The analyst consensus Narrative on Simply Wall St ties that gap directly to how effectively BP executes its project pipeline, cost program and portfolio reshaping.
The ramp-up of major upstream projects and the build-out of BP’s exploration successes, including the around 8 billion barrel Bumerangue discovery in Brazil and 12 discoveries that supported a 90% organic reserve replacement ratio in 2025, keep a multi-year volume and earnings growth story in play as these resources are progressively developed and sold into revenue.
See why 231 investors see BP as 14% undervalued.
Result: Fair Value of £6.61 (UNDERVALUED)
Still, the narrative around BP can be upended if further write downs in gas and low carbon projects occur, or if operating costs prove stubbornly sticky.
Find out about the key risks to this BP narrative.
Another View: What BP’s P/E Ratio Is Telling You
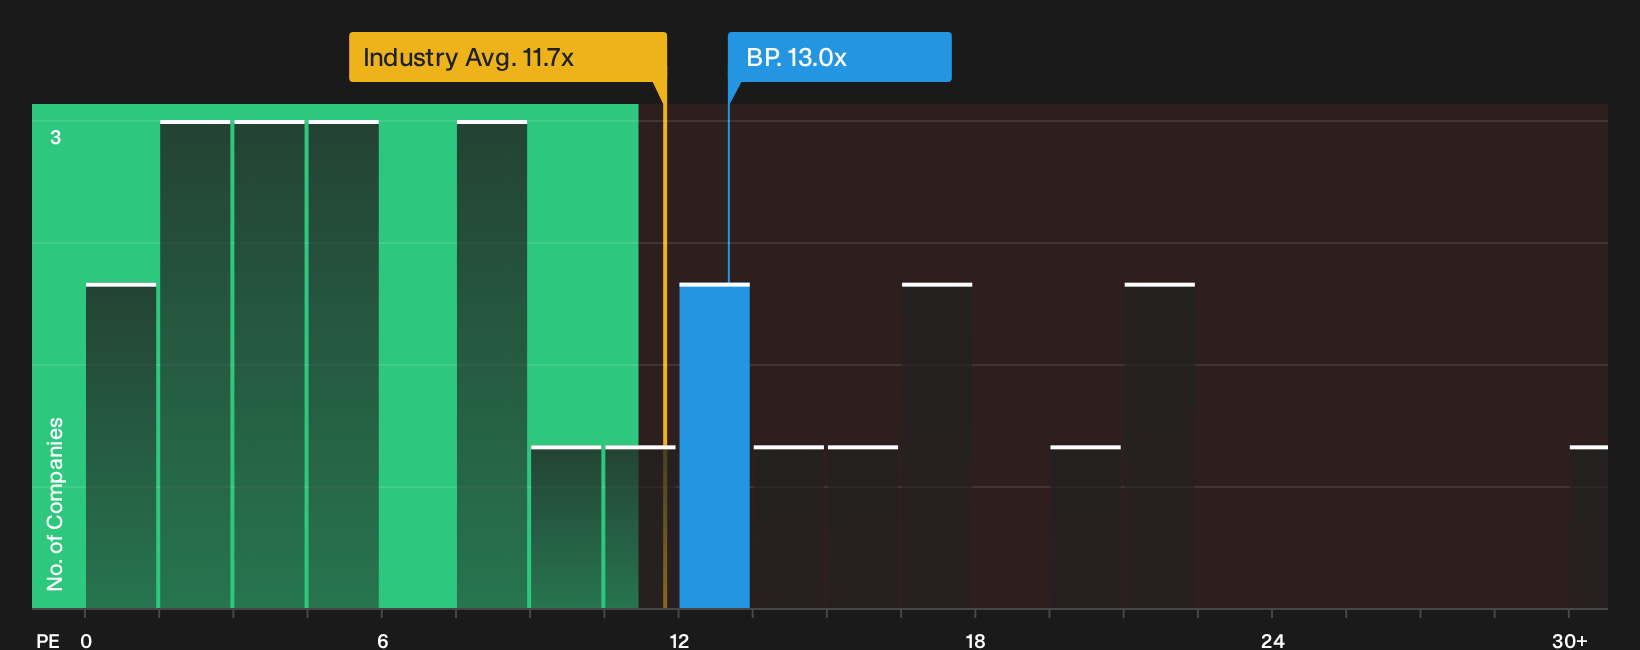
The earlier story paints BP as undervalued against a £10.42 future cash flow estimate. The P/E picture is less generous. At 12.9x earnings, the stock trades well above peers at 8.6x and the wider European oil and gas group at 11.7x, even though the fair ratio sits higher at 22.2x. That mix of a premium to today’s comparables but a gap to the fair ratio raises a simple question. Is the real risk that the share price drifts down toward current peers or edges up toward that fair ratio over time?
For a closer look at how those valuation gaps line up with BP’s fundamentals, See what the numbers say about this price — find out in our valuation breakdown..
Here is how BP’s current earnings multiple stacks up against the sector on one simple chart, which can help you judge whether the premium feels justified or stretched in your own framework.
Next Steps
Mixed messages in the market narrative can be useful. Use that tension as a prompt to check the data yourself quickly and decide where you stand based on BP’s risks and potential upsides. Start by weighing the 2 key rewards and 3 important warning signs.
Looking for more BP sized investment ideas?
If BP has you thinking harder about where to put fresh capital next, use a targeted screener to surface other opportunities that better match your risk and income goals.
- Target potential mispriced opportunities early by running the 5 high quality undiscovered gems before they appear on everyone else’s radar.
- Build a watchlist of cash generative businesses by scanning the list of solid balance sheet and fundamentals (9 results) that combine balance sheet strength with solid fundamentals.
- Lock in potential income ideas by checking the 5 dividend fortresses that focus on higher yielding companies with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com