
Earnings Beat Might Change TISI Shares Narrative
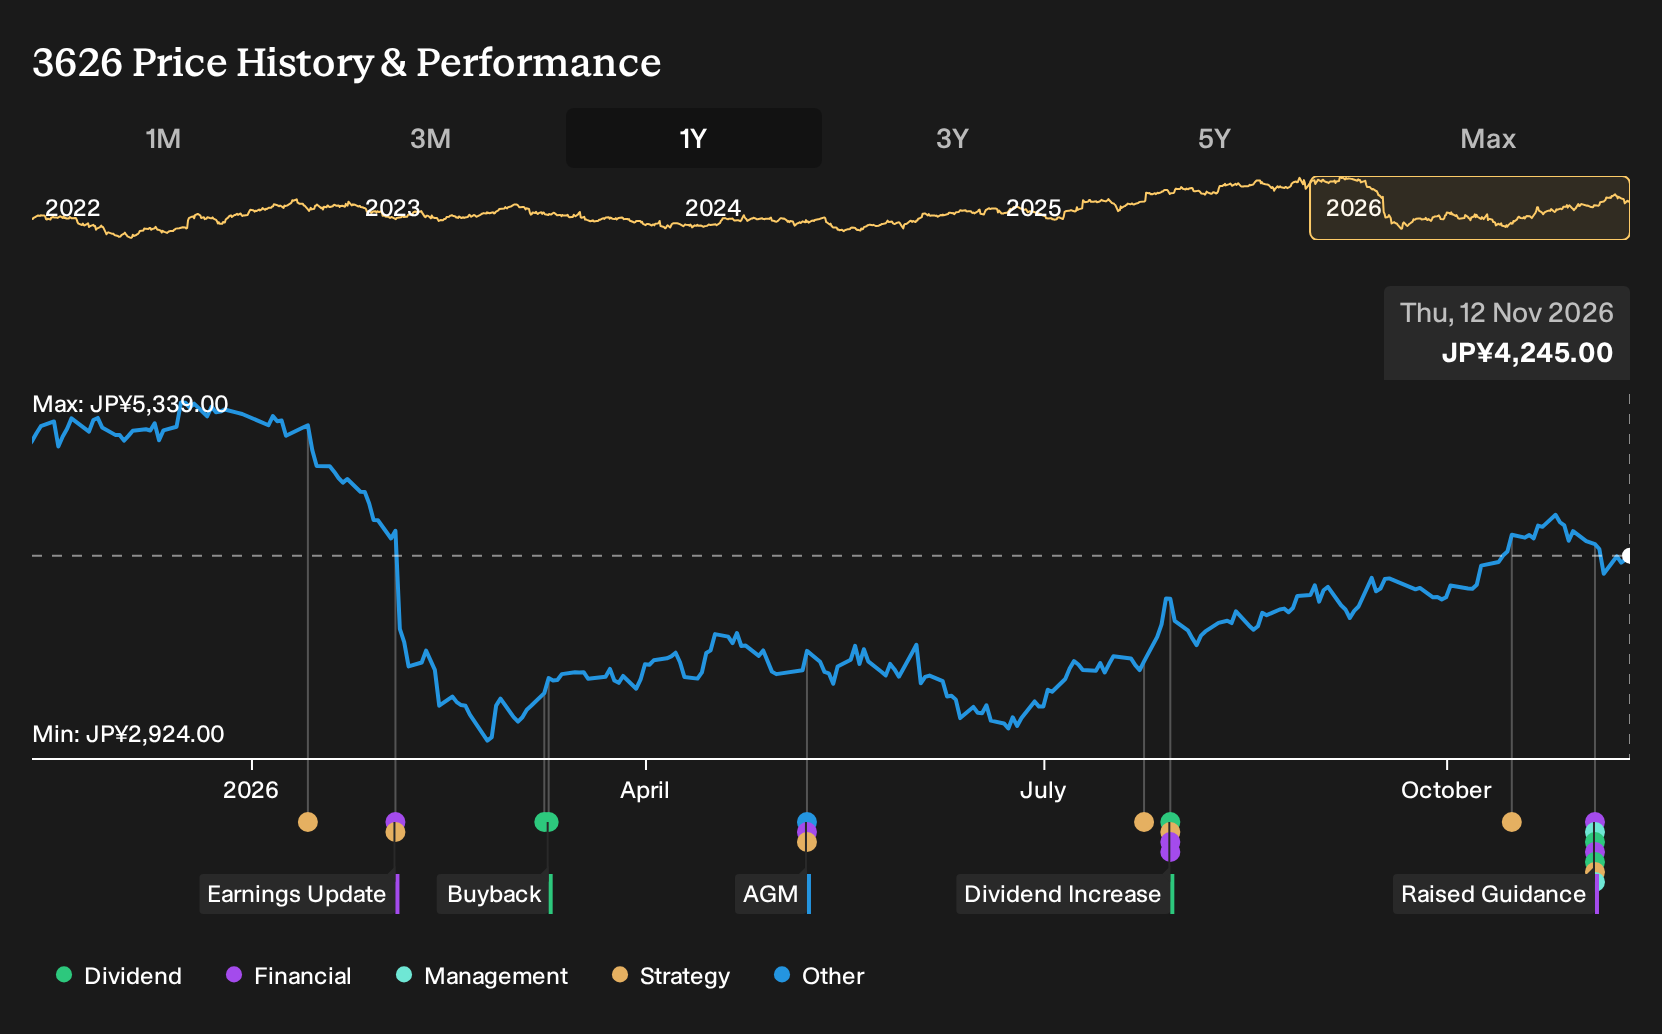
- TISI Inc. reported half year sales of JPY 307,153 million and net income of JPY 26,937 million, raised full year earnings guidance, and lifted both interim and year end dividend forecasts, including a JPY 45 interim dividend and a planned JPY 47 year end payout for fiscal 2027.
- This combination of stronger first half performance, higher full year targets, and a clear policy to gradually raise dividends indicates that TISI is prioritising both operating execution and direct cash returns to shareholders.
- The focus now is on how TISI's investment narrative evolves as higher full year guidance shapes expectations for earnings quality and capital returns.
Scan how TISI's upgraded earnings guidance and richer dividends compare with peers by running the hand picked 18 high quality undervalued stocks now.
What Is TISI's Investment Narrative?
TISI’s story appeals most if you believe in steady IT services demand, disciplined execution and predictable cash returns rather than a hyper growth profile. Revenue and net income for the half year reached ¥307,153 million and ¥26,937 million, and management lifted full year sales and profit guidance, which points to confidence in the existing project pipeline and pricing. Dividend payouts of ¥45 at interim and a forecast ¥47 at year end fit a capital light model that can support both reinvestment and rising distributions when operations run smoothly.
In the short term, the raised forecast and higher dividends are likely to keep attention on how consistently TISI converts its Japan focused order book into margin rich earnings while managing talent costs. The planned CEO transition to Kiyotaka Nakamura adds a governance angle to the thesis, since execution on the Medium Term Management Plan and the higher 50% total return ratio target will sit with a new leader. Share performance has lagged over 1 year even with TSE:3626 trading below some cash flow based estimates, so the key risk now is less about guidance tweaks and more about how durable this earnings and dividend profile looks if demand slows or pricing pressure appears.
That said, sitting behind the cleaner guidance and richer dividend story is one structural weak spot that could still catch investors off guard if ...
There's only one way to know the right time to buy, sell or hold TISI. Head to Simply Wall St's company report for the latest analysis of TISI's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TISI research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for TISI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate TISI's overall financial health at a glance.
Looking for more investment ideas beyond TISI?
If TISI has sharpened your focus on earnings quality and shareholder returns, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who care about getting strong fundamentals at a reasonable entry point, review a curated 18 high quality undervalued stocks that blends balance sheet strength with cash flow support.
- If capital preservation and stability sit high on your checklist, filter for businesses with resilient profiles using our 20 resilient stocks with low risk scores tailored to lower risk scores.
- When you want to uncover less crowded ideas with robust financial traits, search through a focused 74 high quality undiscovered gems that many investors may not yet be watching closely.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com