
FIS Stock What Changed After Its 2026 Guidance Cut
- Fidelity National Information Services reported third quarter 2026 revenue of US$3.454b and net income of US$356m. The company then cut full year 2026 revenue and adjusted EPS guidance below prior expectations while announcing an SEC-style shareholder investigation by Levi & Korsinsky.
- The interim CFO role moved to long time finance executive Alexandra Brooks after James Kehoe stepped down. Investors now have to weigh a guidance reset and leadership transition against reported year to date net income of US$2.954b from continuing operations.
- We will look at how Fidelity National Information Services' investment narrative is challenged by the lowered 2026 revenue and earnings outlook.
What Is Fidelity National Information Services' Investment Narrative?
To stay in Fidelity National Information Services, you need to believe in the resilience of its transaction and software plumbing for banks, brokers and payment providers. The third quarter report shows that the business can produce US$3.454b of quarterly revenue and US$356m of profit, yet the cut to 2026 revenue and adjusted EPS guidance tells you management sees a tougher execution path. Lowered expectations, together with forecasts that earnings may decline over the next few years, put more weight on cost control, pricing power and keeping capital spending disciplined.
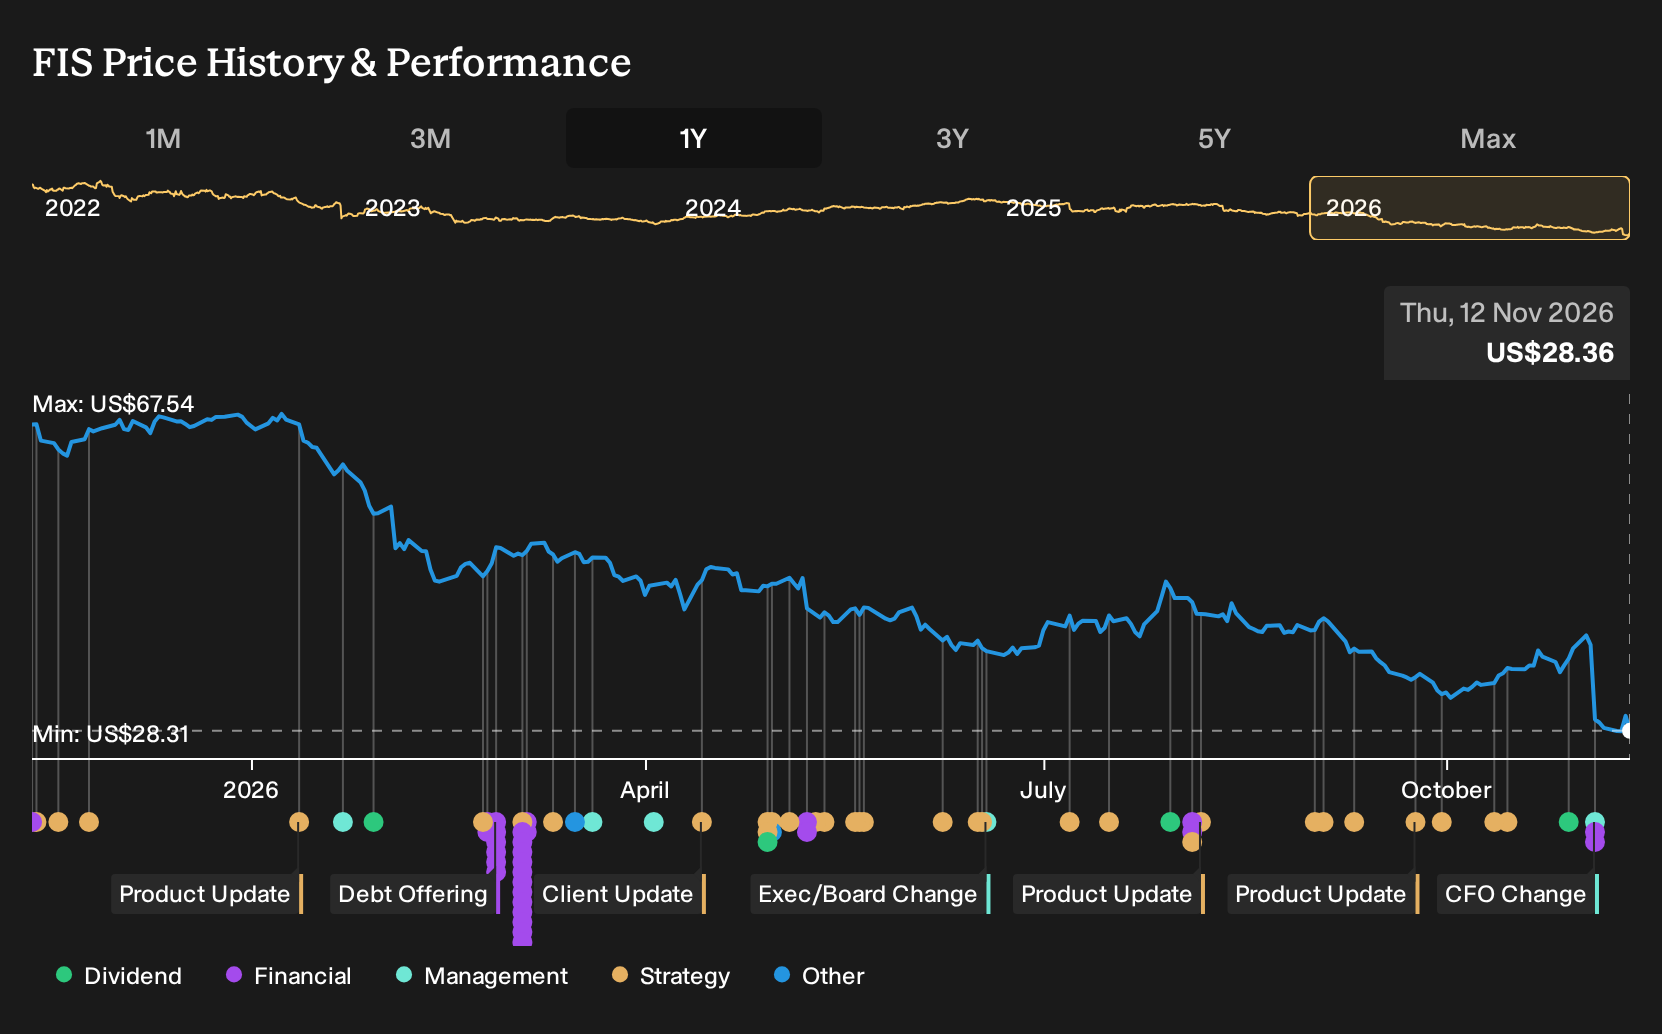
The interim CFO move matters here. Alexandra Brooks steps in with deep finance and accounting experience, and with debt not well covered by operating cash flow, her early calls on leverage, refinancing and cash allocation will sit right at the center of the near term thesis. At the same time, the stock has fallen sharply over 1 year while screens flag FIS as trading on a low P/E and below some cash flow based estimates. The updated outlook plus the shareholder investigation now become the key tests for whether that apparent value reflects risk or opportunity.
Even so, there is a structural pressure point in Fidelity National Information Services' story that could still catch holders off guard if ...
There's only one way to know the right time to buy, sell or hold Fidelity National Information Services. Head to Simply Wall St's company report for the latest analysis of Fidelity National Information Services's Fair Value.
Exploring Other Perspectives
Some analysts were leaning hard into a different catalyst for Fidelity National Information Services before this reset. They focused on recurring revenue, expecting about US$15.7b of sales and US$2.3b of earnings by 2029, as well as a richer P/E. You should treat this CFO change and guidance cut as a fresh reason to revisit those more optimistic assumptions.
Explore 4 other Fidelity National Information Services fair value estimates, including one that suggests as much as 156% potential increase from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own instincts.
- A great starting point for your Fidelity National Information Services research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Fidelity National Information Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Fidelity National Information Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Fidelity National Information Services?
If this update has you reassessing Fidelity National Information Services and you want a broader watchlist, the Simply Wall St Screener can surface other companies that better match your risk tolerance, income needs, or value focus.
- If capital protection and steadier business profiles matter most to you, consider using the screener that highlights 29 resilient stocks with low risk scores with historically resilient characteristics.
- If income is the priority and you want payouts that do more of the heavy lifting, filter for opportunities among 6 dividend fortresses that currently offer higher yields.
- If you are hunting for opportunities that are less picked over by the crowd, sort through 20 high quality undiscovered gems that pair stronger fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com