
AtriCure (ATRC) Raised Guidance After A Profit Return, Is The Stock Cheap?
AtriCure (ATRC) is back in the spotlight after reporting third quarter results that showed higher revenue and a shift to positive earnings, alongside fresh full year 2026 guidance on both sales and profit.
Despite the earnings beat and fresh guidance, AtriCure’s share price has cooled in the very short term. The 1-day share price return is 2.73% lower and the 7-day share price return is 8.68% lower, even as the 90-day share price return of 26.32% and year-to-date share price return of 42.50% point to momentum that has been building over recent months.
Seize this earnings momentum by lining up AtriCure alongside 20 high quality undiscovered gems that analysts may not be watching as closely yet.AtriCure now trades at a double digit discount to the average analyst target, while one intrinsic value signal implies a steep premium. Where does a fair valuation actually land between those two marks?
Most Popular Narrative: 2.8% Undervalued
AtriCure’s last close at $55.96 sits slightly below the narrative fair value of $57.56, so the gap is modest but not trivial according to the analyst consensus Narrative on Simply Wall St, which ties that value to specific growth, margin and risk assumptions.
The main thing that has to go right is that AtriCure converts large trials, new quality metrics, and high-growth cryo pain products into broader, durable procedure adoption quickly enough to offset pressure in minimally invasive ablation and slower international growth.
The current valuation suggests that the share price already reflects continued double-digit revenue growth, further margin expansion toward higher medtech levels, and successful execution of the long-term Vision 2030. This leaves limited room for disappointment and supports a bearish view that AtriCure may be overvalued.
What is behind 6 investors see AtriCure as 3% undervalued.
Result: Fair Value of $57.56 (UNDERVALUED)
Still, this AtriCure story can change quickly if international growth remains stuck in mid single digits or if pressure on minimally invasive ablation deepens further.
Find out about the key risks to this AtriCure narrative.
Another View: AtriCure Through Sales Multiples
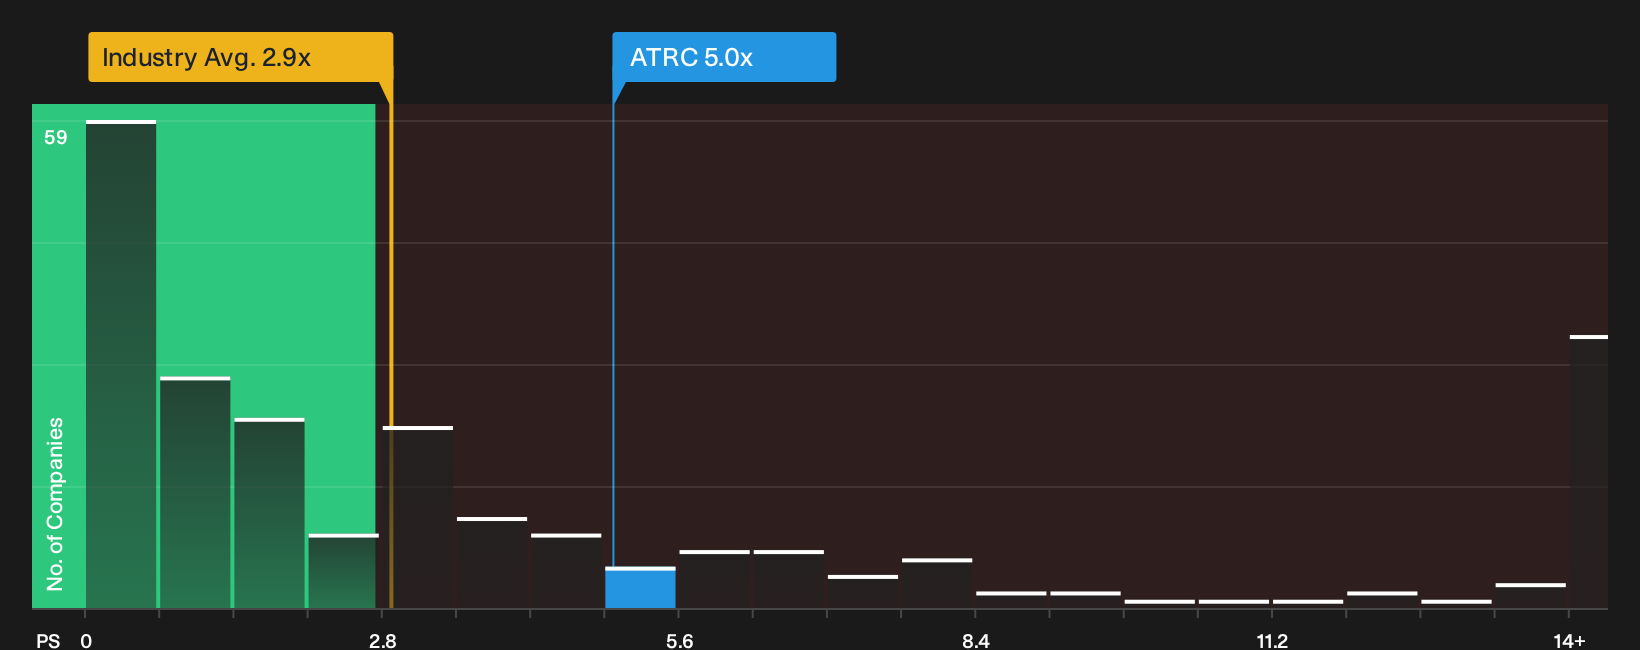
AtriCure may look modestly mispriced on narrative fair value, yet its current P/S ratio of 4.8x is higher than both the US Medical Equipment industry average of 2.9x and its own fair ratio of 4.4x. That richer multiple suggests there is less margin for error if expectations wobble.
In other words, the share price tracks closer to peer optimism than to the fair ratio that the market could move toward over time. If sentiment cools or growth assumptions are rethought, how comfortable are you with paying above both the sector benchmark and that fair ratio benchmark?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on AtriCure’s valuation and expectations can feel messy, so move quickly, look through the full dataset, and weigh both the upside and the hazards set out in 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond AtriCure?
If AtriCure has sharpened your focus, do not stop here. The screener can surface other opportunities that fit your style before the crowd catches on.
- Target reliable income streams by reviewing companies that qualify as 6 dividend fortresses and see which payouts line up with your goals.
- Hunt for quality at a discount with the 31 high quality undervalued stocks and compare how their fundamentals stack up against what you see in AtriCure.
- Prioritise downside protection by scanning the 29 resilient stocks with low risk scores so you can balance higher octane ideas with sturdier holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com