
Cigna (CI) Stock Looks Reasonable Following Raised Earnings Outlook
Cigna Group has delivered a solid multi‑year gain while continuing to lean heavily on its earnings power. The latest trading level puts a fresh spotlight on what investors are actually paying for those profits. With the stock around US$295.81, the question is how well that price lines up with what the business is earning today and is expected to earn in the years ahead.
- Over the past 5 years the share price has risen 48.4%, which puts real pressure on the question of whether the current valuation is still anchored in Cigna Group's earnings profile.
- Recent news of higher earnings expectations and a US$3b modernization program can reshape how investors think about the timing and durability of future profit streams that sit behind any earnings based valuation.
- Your read on Cigna Group is one view; the desks covering it have another. See what analysts think Cigna Group's shares could be worth.
The issue now is whether Cigna Group's current share price is adequately supported by its earnings when viewed through this lens.
If you are weighing Cigna Group against other earnings focused opportunities, it can help to compare it with companies surfaced by 31 high quality undervalued stocks.
Does Cigna Group Look Undervalued on Earnings?
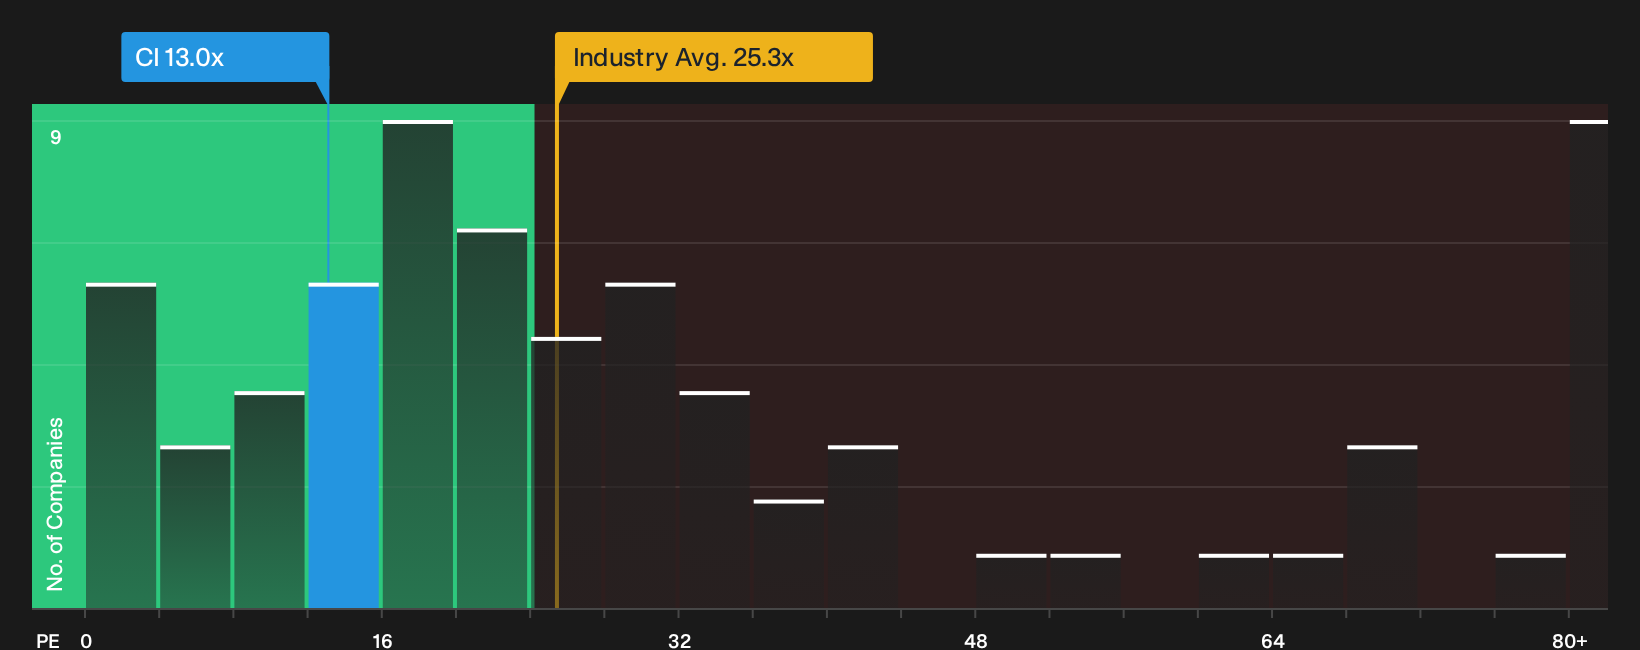
P/E fits Cigna Group because earnings are the main yardstick investors are watching after the latest outlook upgrade. On this measure, the stock trades on a P/E of 13.0x, which is well below the Healthcare industry average of 25.3x and a long way under the 28.4x peer group level. That sets up a valuation that prices each dollar of current profit at a significantly lower tag than many comparable insurers and health services operators.
Because the latest guidance lift for 2026 and the early 2027 earnings target are already public, the key question is why the market is still applying such a low headline multiple. The model based fair P/E that blends Cigna Group’s sector, scale, margins and risk profile points to a higher ratio than the one on screen today. On this framework, the stock screens as undervalued. Despite the recent Q3 beat and the US$3b modernization plan sharpening the earnings story, the market multiple still lags what many investors might expect for this level of profit delivery. Explore the numbers behind Cigna Group's P/E valuation.
The Cigna Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate on Cigna Group leaves off and explain what kind of future around growth, margins and earnings would need to hold for today's price to look meaningfully high or low. They turn a single ratio or fair value line into a set of explicit assumptions so you can watch how Cigna Group's actual progress either supports that scenario or pulls away from it on the Community page.
One of the top narratives on Cigna Group: 13% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Cigna Group is capitalizing on the growing demand for specialty pharmacy and care services, with recent 22% pretax earnings growth in Specialty & Care Services and a larger contribution…"
Discover why this Narrative puts Cigna Group at 13% undervalued.
Cigna Group’s share price is only half the story for long term investors
Price and current earnings frame where Cigna Group is today. However, professional projections for revenues and profits a few years from now offer a very different reference point for your decision. Explore where analysts expect Cigna Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com