
How Raised 2027 Guidance Will Impact CECO Environmental Stock Investors
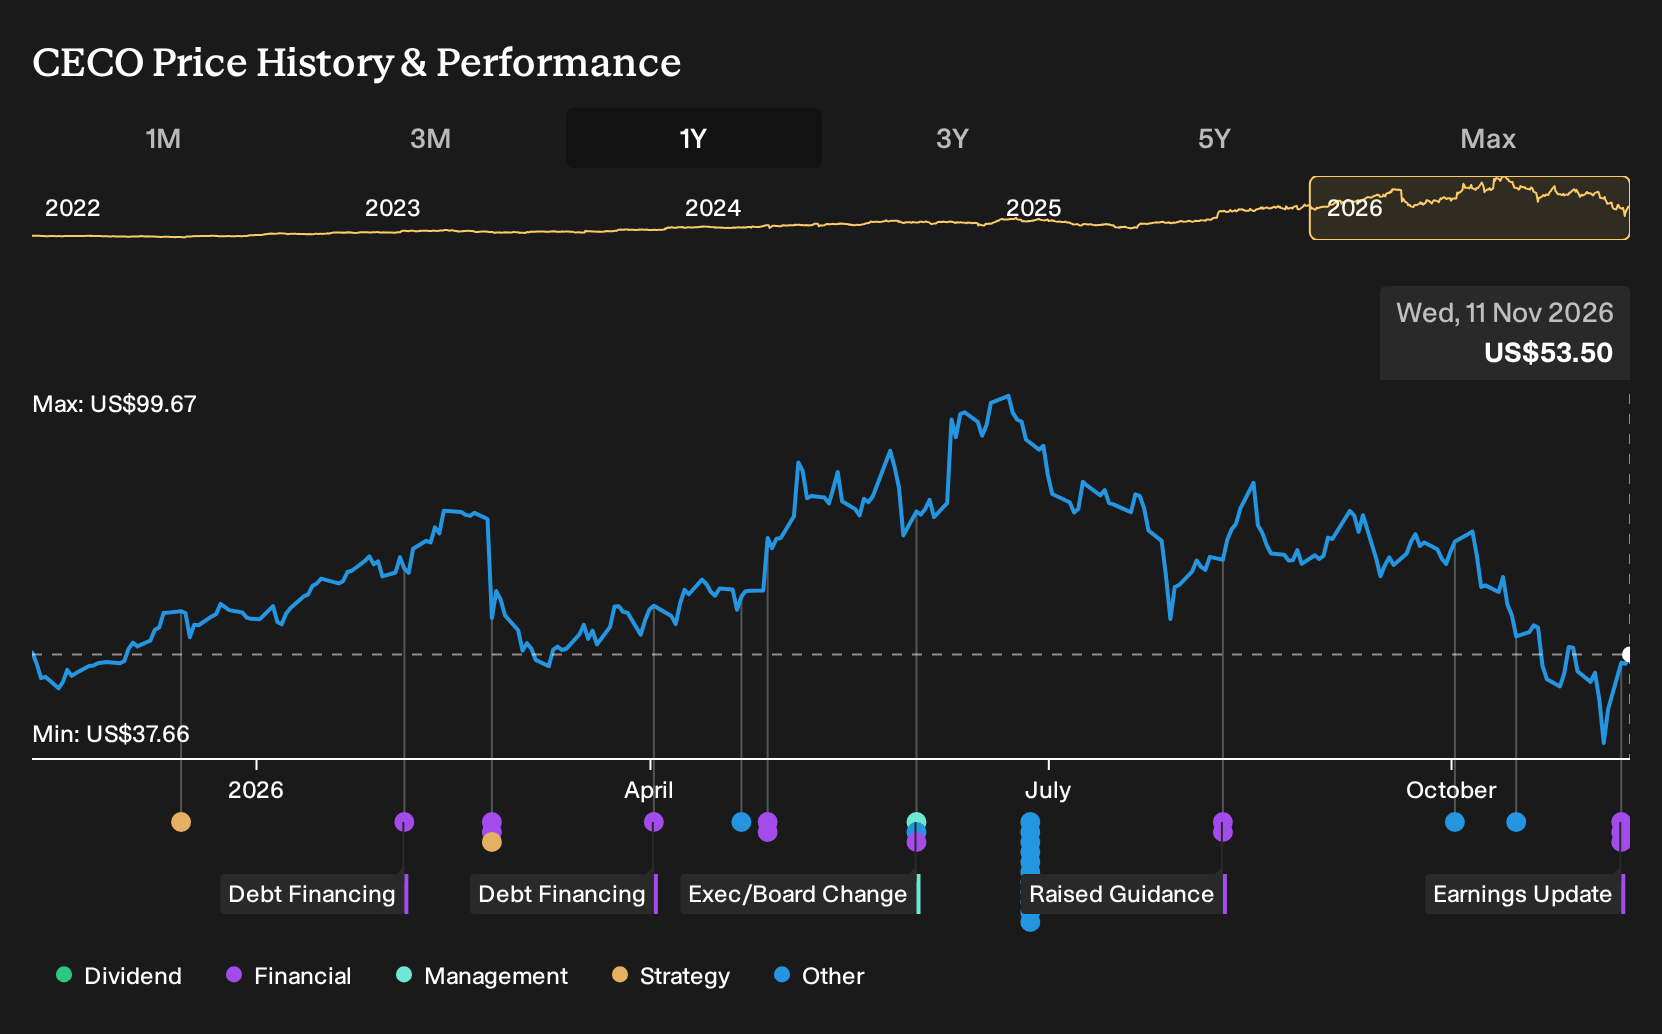
- CECO Environmental reported third quarter 2026 sales of US$404.43 million and a net loss of US$2.02 million, while keeping full year 2026 revenue guidance between US$1.3b and US$1.375b.
- The company now projects 2027 revenue of US$2.1b to US$2.3b, with the midpoint representing more than 60% growth over its 2026 outlook despite recent losses.
- Next, the focus will be on how CECO Environmental's investment narrative is reshaped by this sharply higher 2027 revenue outlook from management.
Scan how CECO Environmental's guidance reset compares with other industrials pricing in strong revenue targets through our hand-picked 43 power grid technology and infrastructure stocks today.
CECO Environmental Investment Narrative Recap
To own CECO Environmental, you have to believe the large backlog and project pipeline described in the analyst consensus Narrative on Simply Wall St can translate into cleaner execution than recent results suggest. Strong Q3 2026 sales of US$404.43 million point to volume, yet the net loss of US$2.02 million keeps profitability in focus.
The clearest near term catalyst is whether management can convert that backlog into revenue while improving margins after reporting a US$37.18 million loss over the first nine months of 2026. The biggest risk is that project timing, leverage concerns and prior shareholder dilution combine to pressure cash generation if execution slips.
The 2027 revenue guidance of US$2.1b to US$2.3b is the announcement that really matters here. It sits on top of record orders, a US$1.82b backlog and a US$8.5b pipeline flagged in the analyst consensus Narrative on Simply Wall St, so it directly tests whether CECO Environmental can deliver on that workload.
For you, the key question is whether current losses reflect temporary integration and project mix issues or a more stubborn profitability problem as the Thermon acquisition is absorbed and large gas and power projects roll through. If backlog conversion, synergies and debt management progress cleanly, that guidance becomes a practical execution hurdle rather than just an aspiration.
CECO Environmental's narrative projects US$2.7b revenue and US$355.5 million earnings by 2029. This assumes 34.3% yearly revenue growth and an earnings increase of about US$389.6 million from a loss of US$34.1 million today.
Uncover why CECO Environmental's fair value indicates a 123% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view places much more emphasis on CECO Environmental's debt load than on its backlog. The most cautious analysts were working with 40.6% annual revenue growth and about US$326.9 million in 2029 earnings before this guidance, yet still arrived at a lower fair value. That gap shows how sharply opinions diverge and invites you to compare both narratives against the new numbers.
Explore 3 other CECO Environmental fair value estimates, including one that suggests it could be worth just $119.57!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your CECO Environmental research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CECO Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CECO Environmental's overall financial health at a glance.
Looking for more CECO Environmental sized investment ideas?
Once you have formed a view on CECO Environmental, it often helps to scan a wider field of potential opportunities so you can compare risk, quality and pricing side by side using the Simply Wall St Screener.
- If capital preservation and steadier profiles matter most to you, start with a curated group of 29 resilient stocks with low risk scores that may suit a more cautious approach.
- If balance sheet strength is your first filter, focus on companies from our list of solid balance sheet and fundamentals (23 results) and see which ones fit your own quality checklist.
- If you like the idea of backing under followed stories, broaden your watchlist with a 20 high quality undiscovered gems that could warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com