
Yamato Kogyo (TSE:5444) Lifts Guidance And Dividends, Is It Still 21% Below Fair Value?
Yamato Kogyo (TSE:5444) has just raised its full year earnings and dividend projections after reporting higher interim sales and net income, tying the outlook to yen weakness and strong contributions from its U.S. affiliate.
Yamato Kogyo’s revised outlook comes after a mixed share price run, with the stock giving a 1-year total shareholder return of 16.77% but a 90-day share price return that declined 16.62%. This suggests recent momentum has cooled even as long-term holders have been rewarded.
Spot 18 high quality undervalued stocks that, like Yamato Kogyo after its upgraded guidance and dividend outlook, pair earnings power with balance sheets capable of withstanding a tougher domestic business cycle.The guidance upgrade and richer dividend promise sit against a share price that has cooled in recent months. Does Yamato Kogyo’s current valuation still leave enough upside to justify taking on new risk?
Preferred Price-to-Earnings of 9.3x: Is it justified?
On current numbers, Yamato Kogyo trades on a P/E of 9.3x, and screens as good value against both its own estimated fair P/E of 12.8x and peers around 11.4x. The last close at ¥11,035 comes with analysts collectively expecting a higher share price, and the SWS DCF model indicating the stock trades at a 21.4% discount to an estimated future cash flow value of ¥14,032.28.
The P/E ratio compares the ¥11,035 share price to earnings per share and effectively tells you how much you pay today for each unit of current profit. For a steel producer with cyclical earnings and a mix of domestic and Southeast Asian exposure, that multiple is a quick way to see how the market is weighing present profitability against the outlook for future results.
Here, the picture leans toward the market pricing Yamato Kogyo cautiously. The stock changes hands at 9.3x earnings, while the estimated fair P/E of 12.8x points to a level valuation could gravitate toward if current profitability and balance sheet strength prove resilient. Relative to both the JP Metals and Mining average of 9.4x and the 11.4x peer group, the current multiple looks restrained rather than stretched.
Explore the SWS fair ratio for Yamato Kogyo.
Result: Price-to-Earnings of 9.3x (UNDERVALUED)
Still, the earnings story for Yamato Kogyo can unravel quickly if yen strength squeezes overseas profits or if construction demand in key Asian markets cools more sharply.
Find out about the key risks to this Yamato Kogyo narrative.
Another view on Yamato Kogyo’s value
The SWS DCF model adds a different lens. It values Yamato Kogyo’s future cash flows at ¥14,032.28 per share, compared with the current price of ¥11,035, which implies the stock trades at roughly a 21.4% discount. Does that gap signal mispricing, or does it simply reflect earnings risk already on the table?
Look into how the SWS DCF model arrives at its fair value.
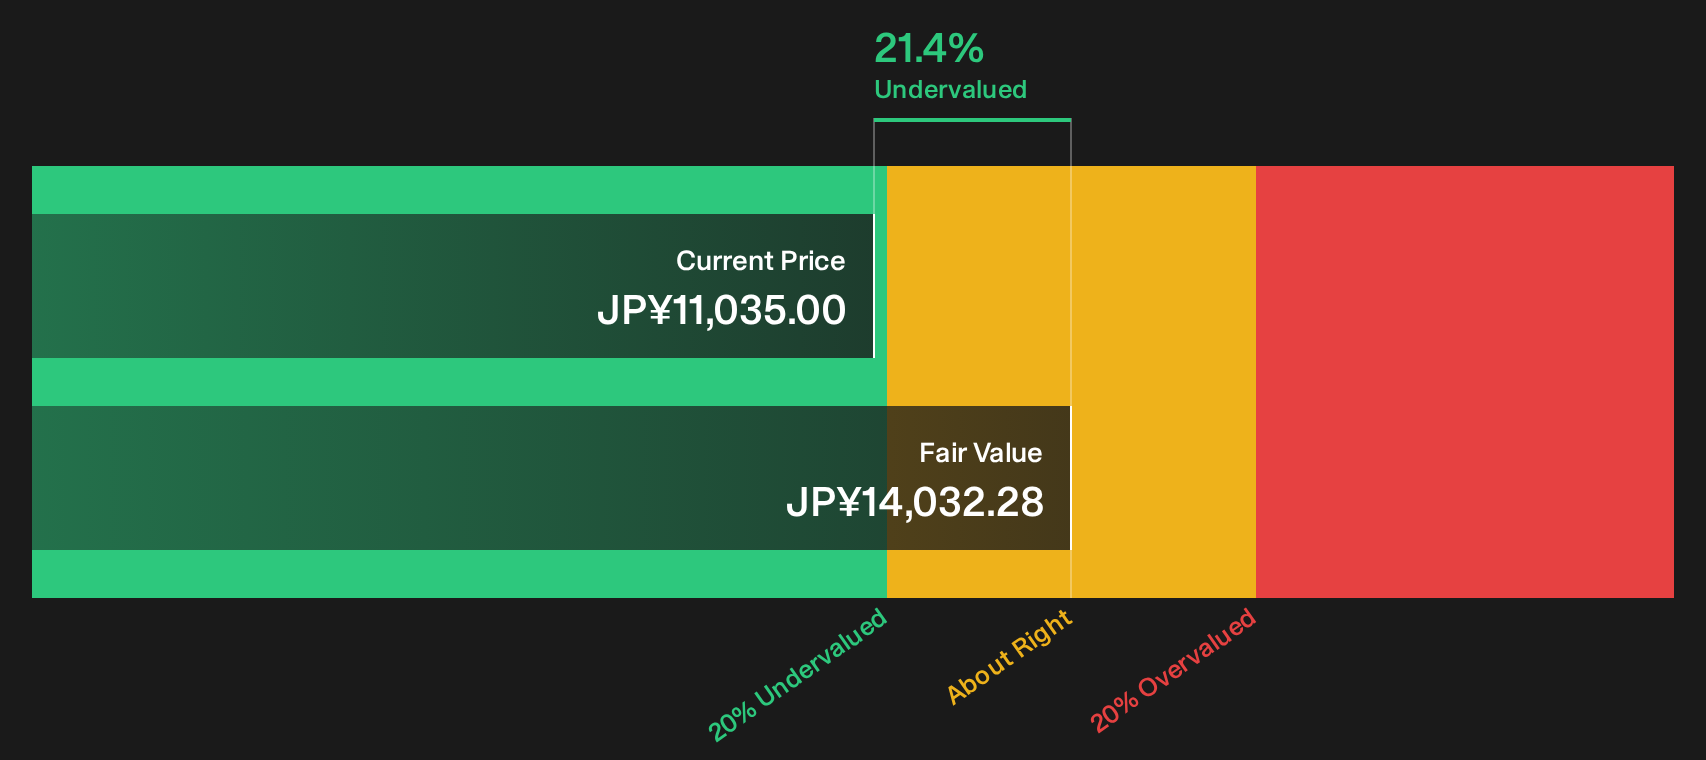
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yamato Kogyo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Yamato Kogyo is clearly mixed, with both risk flags and upside drivers in play, so move quickly and review the data for yourself before opinions harden. To see the full balance of concerns versus potential upsides, start with 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Yamato Kogyo?
If Yamato Kogyo has sharpened your focus on value and resilience, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target sturdier portfolios by scanning a 20 resilient stocks with low risk scores that tilts toward businesses with lower risk scores and more resilient profiles.
- Hunt for stronger balance sheets by running the list of solid balance sheet and fundamentals (25 results) to surface companies with healthier fundamentals backing their earnings power.
- Spot potential future leaders early through a 74 high quality undiscovered gems filled with high quality businesses that are still off most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com