
How Strong Earnings At Perdoceo Education (PRDO) Has Changed Its Investment Story
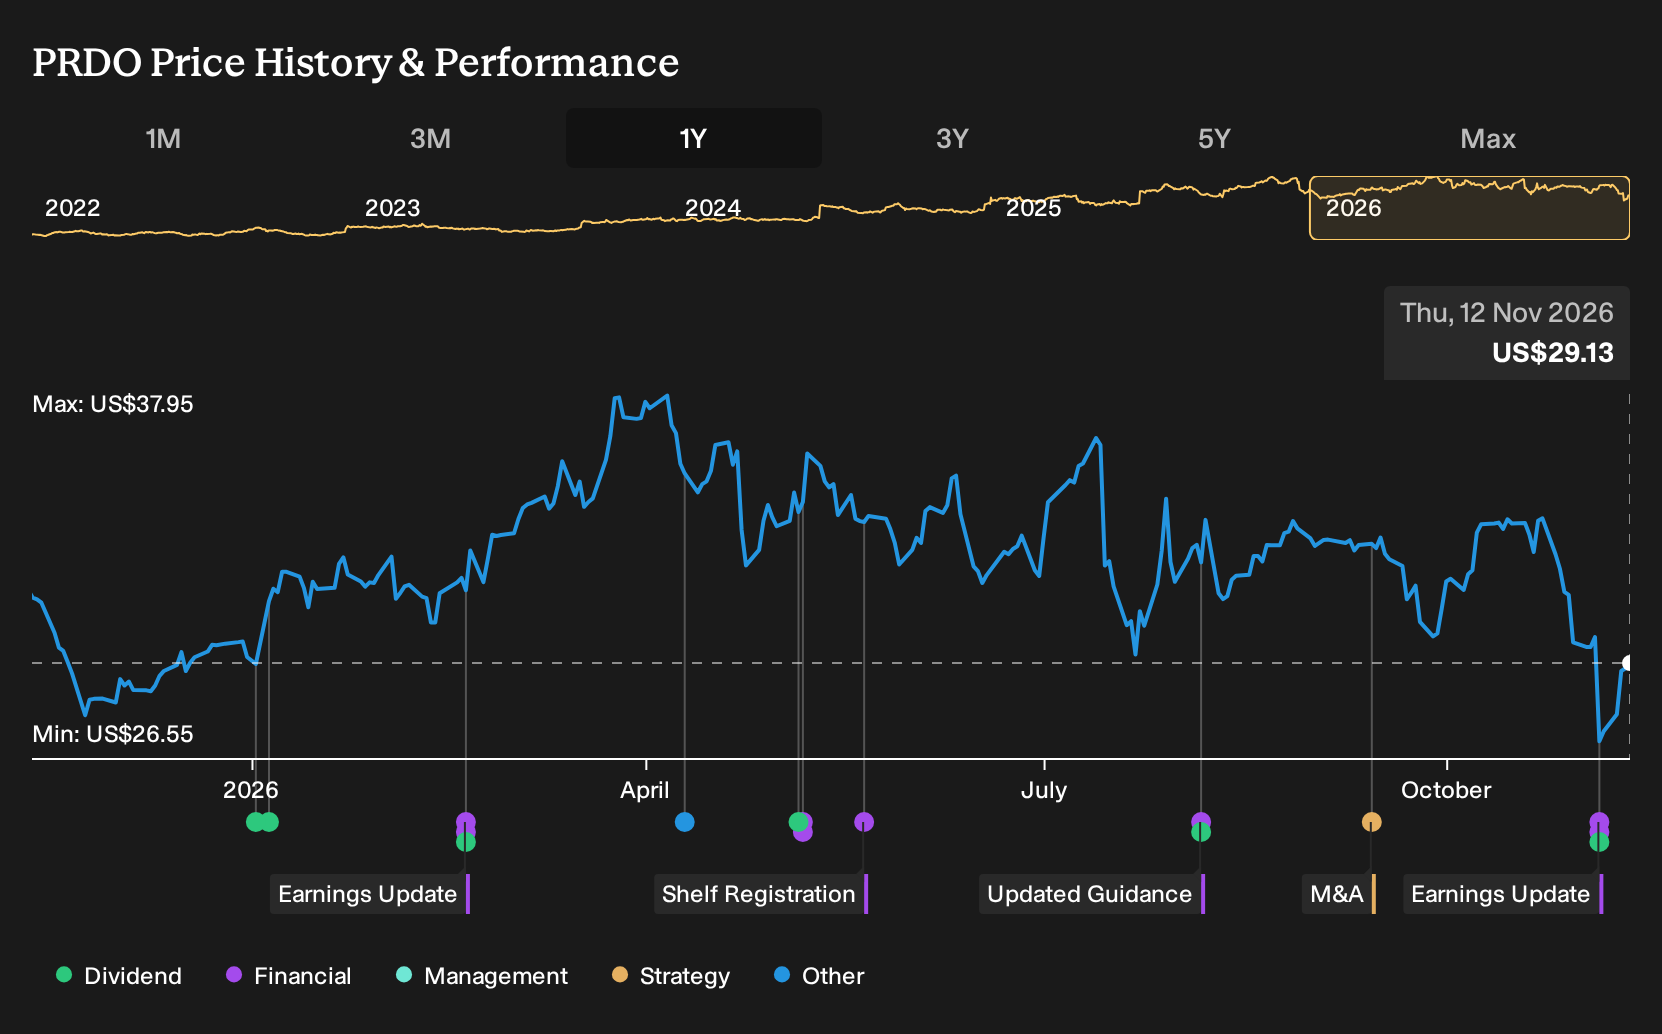
- Perdoceo Education reported third quarter 2026 revenue of US$215.86 million and net income of US$44.39 million, issued earnings guidance for the fourth quarter and full year, affirmed a US$0.17 quarterly dividend, and completed a share repurchase tranche, with all events now in the past.
- The combination of higher earnings per share, fresh guidance and active capital return through dividends and buybacks gives investors more visibility into how Perdoceo Education balances growth investments with returning surplus cash.
- We will now explore how Perdoceo Education's updated earnings guidance could influence the existing free cash flow driven investment narrative.
Scan how Perdoceo Education’s mix of earnings guidance, dividends and buybacks compares with other cash generative businesses in our hand picked list of solid balance sheet and fundamentals (23 results)
Perdoceo Education Investment Narrative Recap
To stay invested in Perdoceo Education, you mostly need to believe its cash generative model in online and blended higher education remains resilient and that management keeps converting earnings into free cash flow. According to J_Tyrader, an investor in the Simply Wall St Community, the story is about a strong margin profile and a solid balance sheet supporting that cash engine. The latest quarterly results and full year guidance frame the near term catalyst as continued delivery against earnings expectations. The main operational risk is pressure on enrollment or pricing that could strain margins and slow that cash conversion.
The fresh outlook for 2026 earnings per diluted share of US$2.93 to US$2.97 gives you a clearer reference point for the coming quarters, although it does not radically change the thesis built around free cash flow and capital discipline. For now the update looks more like confirmation than reset. Execution on program quality, student outcomes and regulatory compliance still matters most. Any stumble there could weigh on both growth and the valuation narrative J_Tyrader laid out.
The most relevant update for that thesis is Perdoceo Education’s full year earnings guidance of US$2.93 to US$2.97 per diluted share with operating income of US$221.0 million to US$224.0 million. Those figures, paired with the reported nine month net income of US$146.31 million, help you judge whether the earnings power described by J_Tyrader is holding up in practice. They also give a concrete yardstick for your own scenario work.
This guidance interacts directly with the catalysts around free cash flow and perceived undervaluation that J_Tyrader highlighted. If the firm keeps translating this level of profitability into cash and maintains its dividend and buyback activity, investors focused on cash yield and disciplined capital use may stay engaged. The risk side is that any shortfall against these guided ranges could challenge confidence in the valuation gap and shift attention back to slower expected revenue growth versus the wider US market.
On J_Tyrader’s numbers, Perdoceo Education reaches a fair value of US$91.64, because discounting ten years of 17.7% free cash flow growth that slows to 2.5% in the terminal period at a 9.8% rate produces that outcome, with more than half of the estimate tied to long range cash flows.
Uncover why Perdoceo Education's fair value indicates a 215% potential upside to its current price before that kind of discount is no longer available.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community range from US$25 to about US$183.66 for Perdoceo Education, so opinions already span a wide gap. Those appraisals predate the latest earnings, guidance, dividend affirmation and completed buyback, which could influence how different investors view future execution risk and payout sustainability.
Explore 3 other Perdoceo Education fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Perdoceo Education research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Perdoceo Education. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Perdoceo Education's overall financial health at a glance.
Looking For More Investment Ideas Beyond Perdoceo Education?
If Perdoceo Education has sharpened your focus on cash generation and disciplined capital use, it can help to compare that profile against a wider watchlist. The Simply Wall St Screener lets you quickly filter for different angles, whether you care most about balance sheet strength, income potential or under the radar opportunities.
- For investors who like the comfort of strong finances, scan a list of solid balance sheet and fundamentals (23 results) that pairs resilient balance sheets with solid fundamentals.
- If you are hunting for value where quality and price still look out of sync, filter the market through a 32 high quality undervalued stocks that meet strict cash flow and balance sheet criteria.
- For those who want income to do more of the heavy lifting, focus on payout strength and consistency with a 6 dividend fortresses built for yield orientated portfolios.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com