
CrowdStrike Holdings (CRWD) Could Be 8% Undervalued As AI Security Push Builds
CrowdStrike Holdings (CRWD) just rolled out a packed slate of AI-focused security tools and partnerships, headlined by a sovereign Falcon cloud deployment in Saudi Arabia that keeps sensitive data in country while tapping global threat intelligence.
CrowdStrike Holdings has ridden strong AI security headlines and big partner announcements into sharp gains, with the share price up 102.72% year to date and a 3-year total shareholder return of 350.13%. However, the 30-day share price return is down 12.00%, which suggests long term momentum remains strong while shorter term sentiment has cooled slightly.
Scan how CrowdStrike Holdings fits into the broader AI security surge and compare it with 53 AI infrastructure stocks that could be next in line for attention.
Bulls point to CrowdStrike Holdings’ AI security reach and long runway, while bears see rich expectations after a 3-year return above 350%. The valuation work next helps show which story the current price leans toward.
Most Popular Narrative: 8% Undervalued
The analyst consensus Narrative on Simply Wall St pegs CrowdStrike Holdings’ fair value at about $249.68 per share against a last close of $229.87. This points to a modest gap that the valuation work attempts to explain through long term AI security assumptions.
The current valuation reflects a share price that, according to this narrative, already assumes CrowdStrike achieves multi billion dollar ARR contributions from newer businesses such as AI security, next generation SIEM, identity and cloud security, together with high free cash flow margins. This narrative characterizes the shares as overvalued and bearish.
See why 494 investors see CrowdStrike Holdings as 8% undervalued.
Result: Fair Value of $249.68 (UNDERVALUED)
Still, if CrowdStrike falls short of the high AI driven revenue expectations or non GAAP adjustments mask weaker earnings quality, this 8% undervaluation narrative could fade quickly.
Find out about the key risks to this CrowdStrike Holdings narrative.
Another View: CrowdStrike Holdings Looks Expensive On Sales
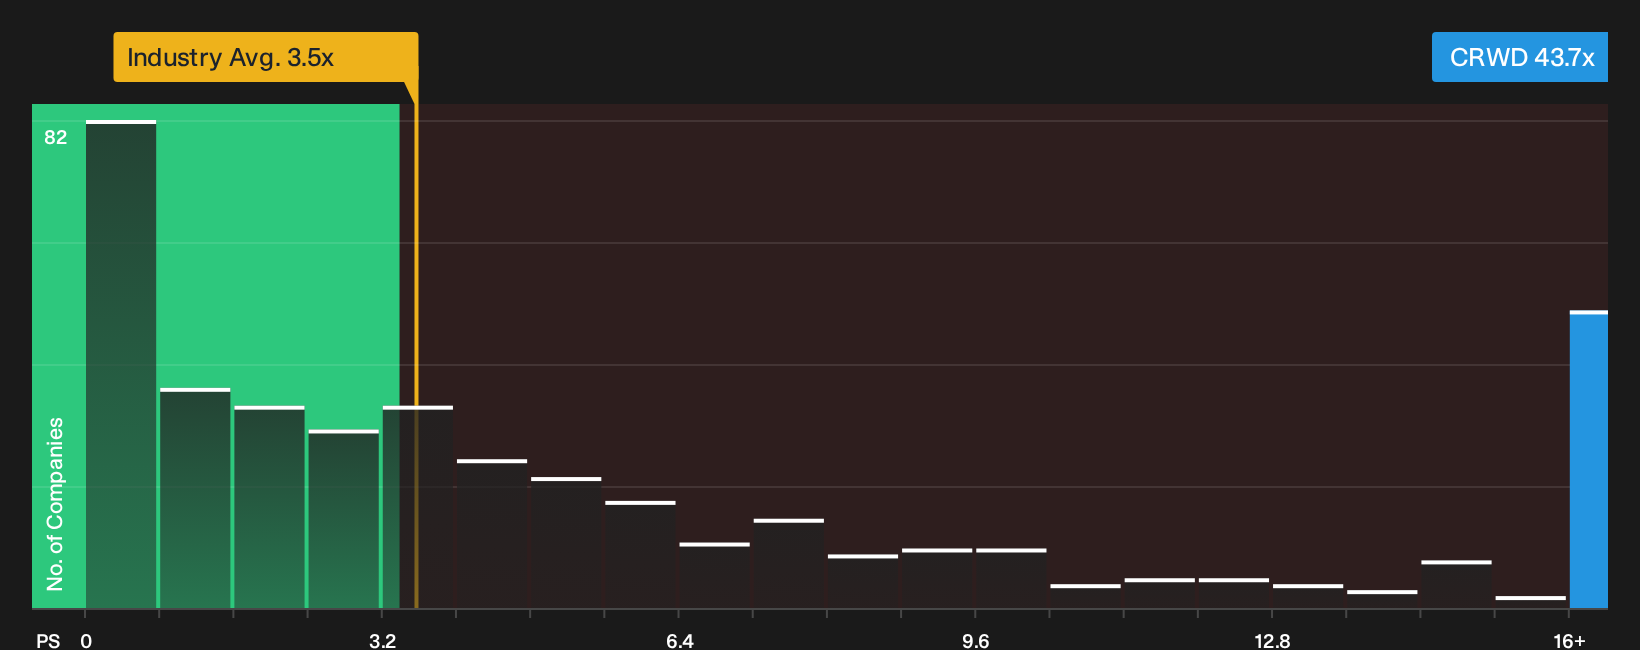
The fair value narrative leans on analyst targets and long term AI security forecasts. A simple P/S lens tells a sharper story. CrowdStrike trades at about 43.7x sales, versus 11.8x for peers and 3.5x for the broader US Software group, while the fair ratio sits at 17.7x. That gap implies a lot of optimism already in the price. The question is whether you think execution can keep matching that premium.
For a closer look at how these sales based metrics stack up against what the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals in the CrowdStrike Holdings story so far. Act while sentiment is still shifting and pressure test the full picture using 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CrowdStrike Holdings?
CrowdStrike can be a helpful reference point, but your edge comes from lining it up against other opportunities that match your goals and risk tolerance.
- Target potential mispriced opportunities by scanning a curated 32 high quality undervalued stocks that pairs strong fundamentals with more tempered expectations.
- Prioritise resilience and sleep better at night by using the 29 resilient stocks with low risk scores that filters for stocks with more defensible risk profiles.
- Spot earlier stage opportunities before they hit the spotlight by searching through a focused 20 high quality undiscovered gems built around quality and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com