
Is Agios Pharmaceuticals (AGIO) Undervalued Following Stronger Q3 Results And Its FDA Review Update?
Agios Pharmaceuticals (AGIO) just paired a third quarter earnings update with fresh regulatory news on mitapivat in sickle cell disease, giving investors new data on both current operations and its lead growth driver.
Recent headlines around the FDA review extension and the stronger third quarter figures have arrived against a mixed backdrop for Agios Pharmaceuticals, with the share price up 16.85% year to date, but the 1 year total shareholder return down 25.34%. A 42.81% total shareholder return over three years points to longer term momentum that has partly faded over the past year.
Spot similar rare disease and biotech stories that may be approaching potential inflection points by scanning our curated 20 high quality undiscovered gems alongside Agios Pharmaceuticals.After a double digit gain this year but a sharply negative 1 year return, Agios Pharmaceuticals now forces a timing call. Does the recent move justify patience for a cheaper entry, or does the current valuation already look workable?
Most Popular Narrative: 31% Undervalued
On the analyst consensus Narrative on Simply Wall St, Agios Pharmaceuticals screens as undervalued, with a fair value of $46.00 against the recent $31.76 close. This puts the focus squarely on how much of its rare disease story is already in the price.
The current valuation suggests the market is discounting this bullish view that Agios Pharmaceuticals is undervalued, with the share price not fully reflecting mitapivat growth, broader regulatory momentum and the contribution of pipeline assets like cevidoplenib and AG‑236.
See why 7 investors see Agios Pharmaceuticals as 31% undervalued.
Result: Fair Value of $46.00 (UNDERVALUED)
Still, the Agios Pharmaceuticals story depends heavily on mitapivat delivering across new indications, while ongoing net losses and flat planned 2026 spending leave little room for execution missteps.
Find out about the key risks to this Agios Pharmaceuticals narrative.
Another View: What Multiples Say About Agios Pharmaceuticals
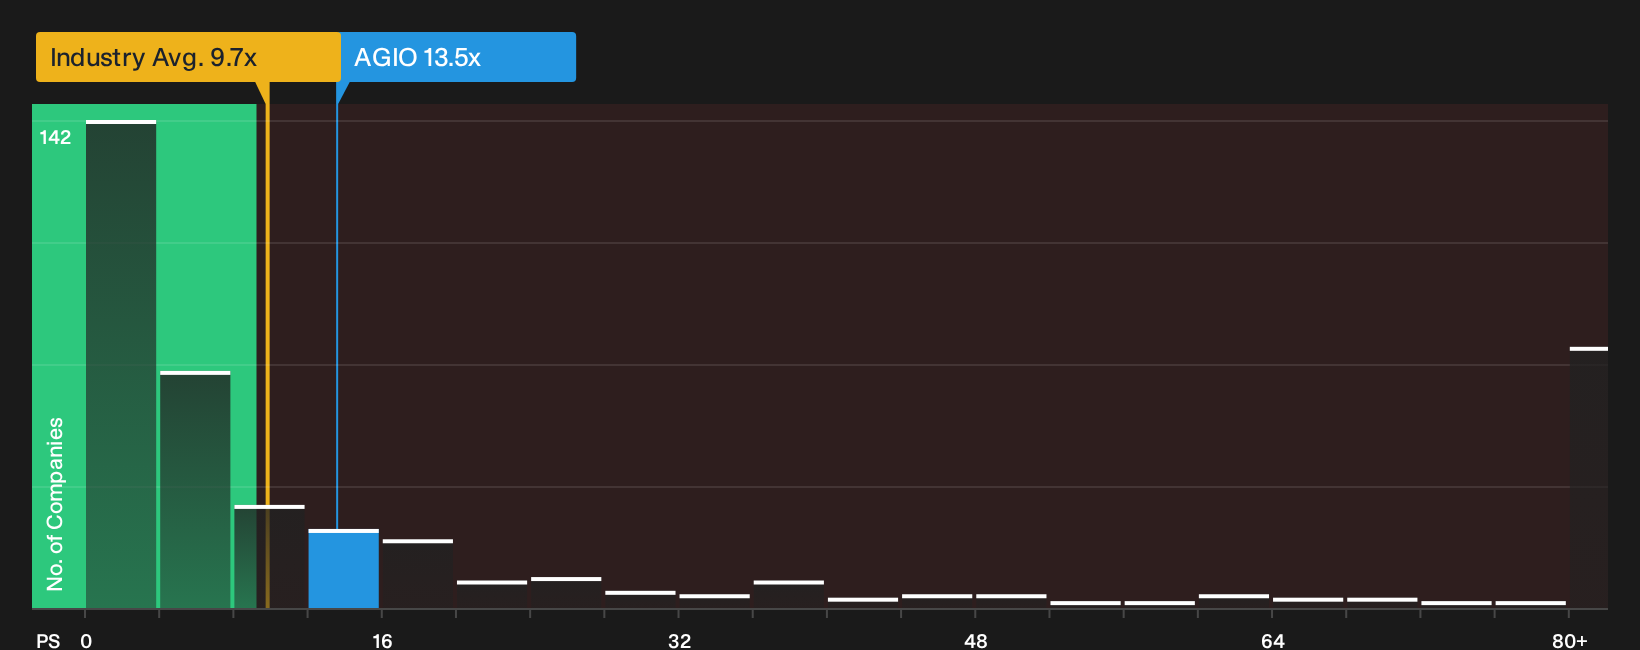
There is a very different signal once you look at Agios Pharmaceuticals through its P/S ratio. The stock trades at about 13.5x sales, compared with 10.3x for the US Biotechs industry and a fair ratio closer to 0.9x based on regression work. That gap suggests investors carry valuation risk if sentiment softens, so it may be useful to consider how much premium you are comfortable paying for this rare disease pipeline story.
For a numbers first check on this pricing gap, review See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of risks and upside in Agios Pharmaceuticals feels finely balanced, consider acting promptly and weighing the evidence yourself. Start by reviewing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Agios Pharmaceuticals?
If Agios Pharmaceuticals has sharpened your thinking, do not stop here. Broader opportunity often shows up where fresh screening work points you toward stronger fundamentals.
- Target resilient compounding potential by scanning companies that appear mispriced on quality and fundamentals through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with robust payout profiles using the 6 dividend fortresses.
- Prioritise capital protection by filtering for companies with healthier balance sheets and sturdier financial footing via the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com