
ICU Medical (ICUI), What Is Behind The Latest Attention?
ICU Medical (ICUI) drew investor attention after third quarter 2026 results showed a move from a prior net loss to US$26.85 million in profit, along with reaffirmed full year earnings guidance toward the higher end of its range.
The reaffirmed outlook appears to sit behind a solid year-to-date share price return of 27.99% at a latest share price of US$177.30. However, the 90 day share price return has slipped 3.10%, and the 5 year total shareholder return of 28.21% in decline contrasts with a 3 year total shareholder return of 107.17%, which suggests that earlier momentum has cooled recently.
Scan ICU Medical’s earnings-driven move against other potential healthcare breakouts by zeroing in on our hand picked list of 35 healthcare AI stocks for your next idea.
ICU Medical’s swing back to profit and a strong year-to-date run leave investors weighing two paths: lean in after this rebound or wait for a cheaper entry if enthusiasm cools.
Most Popular Narrative: 9% Undervalued
ICU Medical’s analyst consensus Narrative on Simply Wall St points to a fair value of $194 per share compared with the last close at $177.30. This frames the recent rebound against what analysts see as still-underpriced cash flow potential using a 7.98% discount rate.
Manufacturing network consolidation, integration synergies and reduced restructuring and remediation cash spend, alongside a mix shift toward higher margin products and an exit gross margin target of 43% by the end of 2027, indicate further efficiency gains that can support EBITDA margin and free cash flow.
See why 2 investors see ICU Medical as 9% undervalued.
Result: Fair Value of $194 (UNDERVALUED)
Still, ICU Medical’s story can break if tariff costs stay elevated or if the Vital Care unit, with its weaker growth and margin profile, keeps dragging on group returns.
Find out about the key risks to this ICU Medical narrative.
Another View: ICU Medical Looks Pricey On Earnings
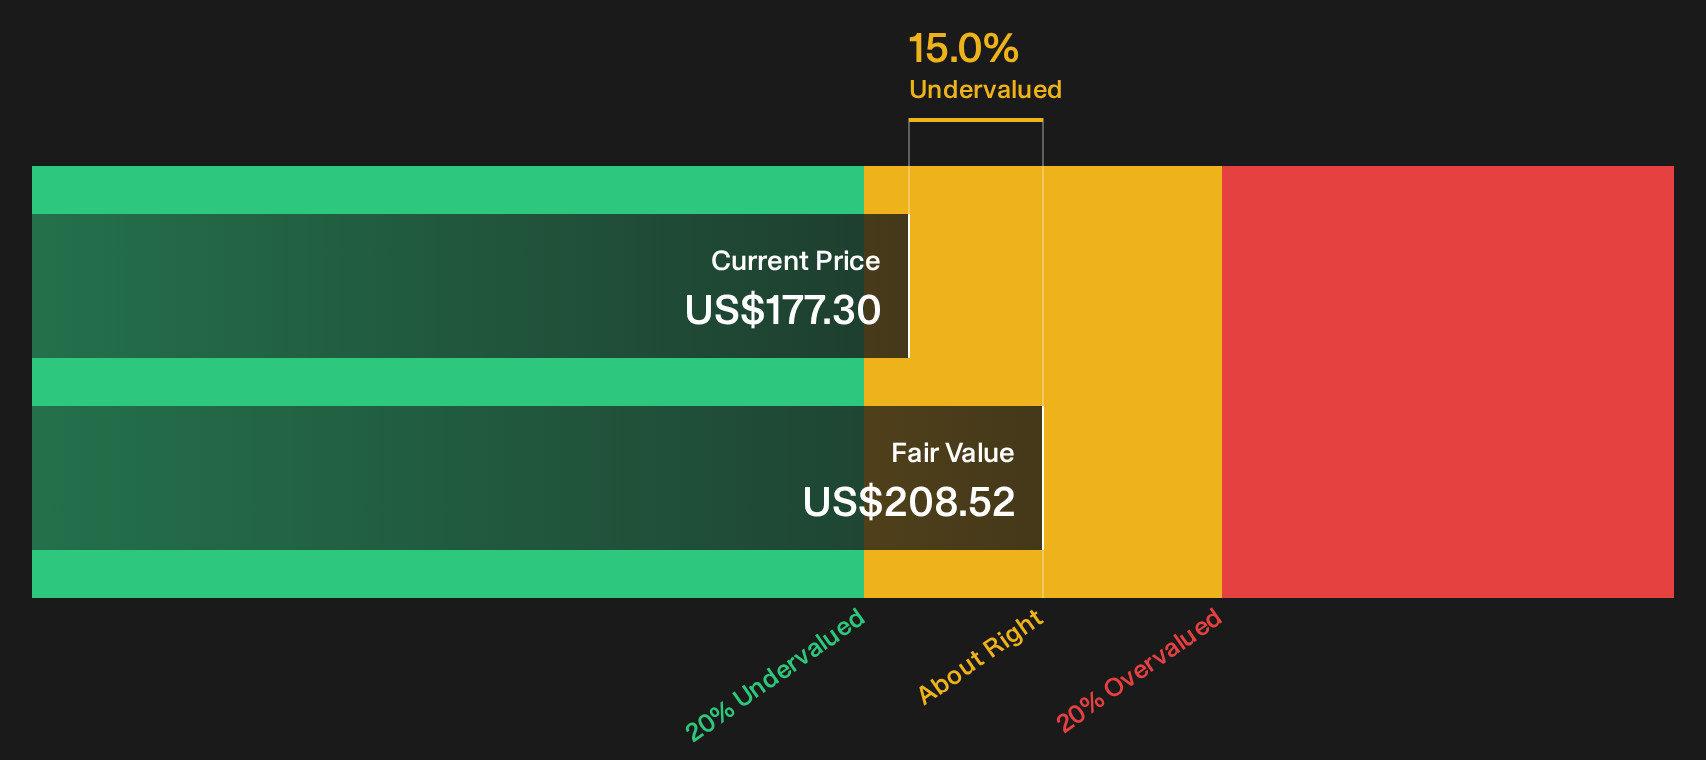
ICU Medical may screen as undervalued on our DCF work, yet the current P/E of 73.5x is more than double the US Medical Equipment sector on 26x and also well above a fair ratio of 30.9x. That gap points to meaningful valuation risk if sentiment or growth expectations soften.
For investors weighing these mixed signals, it can help to see exactly how the cash flow math stacks up in the SWS DCF model before deciding which lens to lean on most. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed feelings about ICU Medical after this rebound and valuation debate. Take a fresh look at the numbers, carefully weigh both caution and potential upside for yourself, then review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ICU Medical?
If ICU Medical has sharpened your focus, do not stop here. Use the Simply Wall St screener to quickly surface fresh candidates before the market moves first.
- Target potential mispricing by scanning a curated set of 32 high quality undervalued stocks that combine quality fundamentals with attractive valuations.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle earnings swings and funding pressure.
- Get ahead of the crowd by reviewing a 20 high quality undiscovered gems that few investors may be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com