
Does Raised 2026 Guidance Change The Bull Case For CBL & Associates Properties Stock (CBL)?
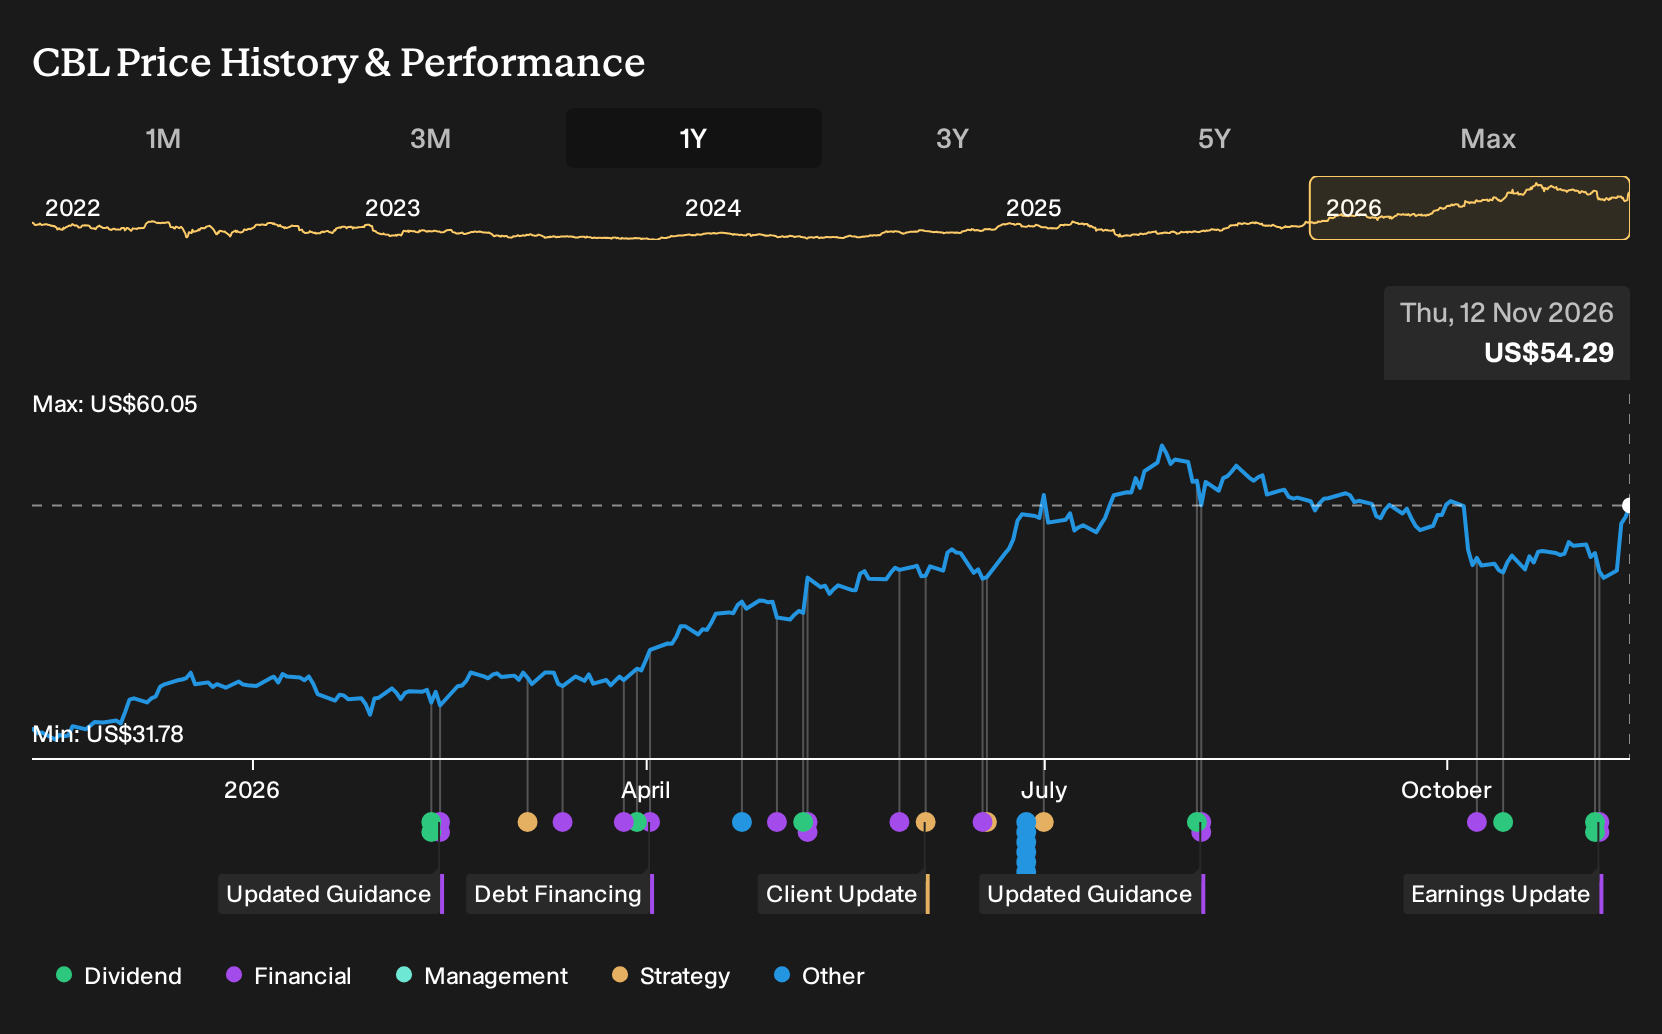
- CBL & Associates Properties reported third quarter 2026 revenue of US$148.7 million and net income of US$11.79 million, then lifted full year earnings guidance and authorized up to US$25 million in share repurchases through the end of 2027.
- Management paired higher 2026 profit expectations with a multi year buyback, which signals confidence in CBL & Associates Properties' cash generation and its balance between reinvestment in malls and direct cash returns to shareholders.
- As CBL & Associates Properties refines its investment narrative around cash generation, the higher 2026 earnings outlook becomes a central test of that narrative.
Scan beyond CBL & Associates Properties and evaluate other potential rebound and income candidates using our curated list of 6 dividend fortresses
What Is CBL & Associates Properties' Investment Narrative?
To own CBL & Associates Properties, you need to be comfortable with a fairly simple idea. This is a capital intensive real estate platform that lives or dies on leasing execution, occupancy, and how efficiently it refinances debt. The latest quarter showed revenue of US$148.7 million and nine month net income of US$104.72 million, with management confident enough to raise 2026 net income guidance to a range of US$112.1 million to US$115.2 million. That outlook, along with higher adjusted FFO guidance and a US$25 million buyback through 2027, shifts the story toward cash generation and disciplined capital allocation.
The flip side is that this remains a levered retail REIT where interest costs matter and earnings forecasts still point to pressure over the next few years. Operational improvements such as rising occupancy and increased leasing activity help, particularly when net profit margins have moved from 22.3% to 25.2%. The share repurchase authorization can support per share metrics in the near term, but debt service and the quality of earnings, including large one off items, remain central considerations.
Even so, there is a specific pressure point in the CBL & Associates Properties story that could turn if...
There's only one way to know the right time to buy, sell or hold CBL & Associates Properties. Head to Simply Wall St's company report for the latest analysis of CBL & Associates Properties's Fair Value.
Exploring Other Perspectives
Fair value estimates for CBL & Associates Properties from the Simply Wall St Community span roughly US$45.82 to US$66 across 2 individual assessments, which shows how far apart retail investors can be. Those views were formed before the 2026 guidance raise and US$25 million buyback, so you may want to revisit several contrasting opinions.
Explore another CBL & Associates Properties fair value estimate, including one that suggests as much as 22% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your CBL & Associates Properties research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for CBL & Associates Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CBL & Associates Properties' overall financial health at a glance.
Looking for more investment ideas beyond CBL & Associates Properties?
If you want to broaden your watchlist beyond CBL & Associates Properties, the Simply Wall St Screener can help you line up fresh candidates that match your own risk tolerance and income goals.
- For investors who want potential value combined with quality fundamentals, scan through our curated set of 32 high quality undervalued stocks that may warrant a closer look.
- If capital preservation ranks high on your checklist, focus on businesses highlighted in our 29 resilient stocks with low risk scores to see which ones score well on resilience.
- Income focused readers can zero in on steady cash return prospects by reviewing the 6 dividend fortresses that screen for higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com