
Is Vipshop Holdings (NYSE:VIPS) Undervalued Based On Its Earnings?
Vipshop Holdings has delivered a 5 year return that looks very different to its more recent share price slide, which puts fresh focus on whether the current US$12.94 level is properly supported by its earnings power. With the stock down over the past year, investors are asking if the earnings story still lines up with where the market is pricing Vipshop today.
- Over 5 years the stock is up 42.4%, which makes the question of what investors are now paying for each dollar of earnings especially important.
- The business model is heavily tied to turning merchandise efficiently into cash, so profitability and how consistently earnings convert into free cash flow can shape what a fair earnings multiple looks like.
- There is a second opinion on Vipshop Holdings worth weighing. See what analysts think Vipshop Holdings's shares could be worth.
The stock's next move may depend on whether Vipshop's current earnings justify the valuation investors are putting on the business today.
If you want more context around Vipshop Holdings' recent share price slide and earnings focus, compare it with other companies using the 32 high quality undervalued stocks.
Does Vipshop Holdings Look Undervalued on Earnings?
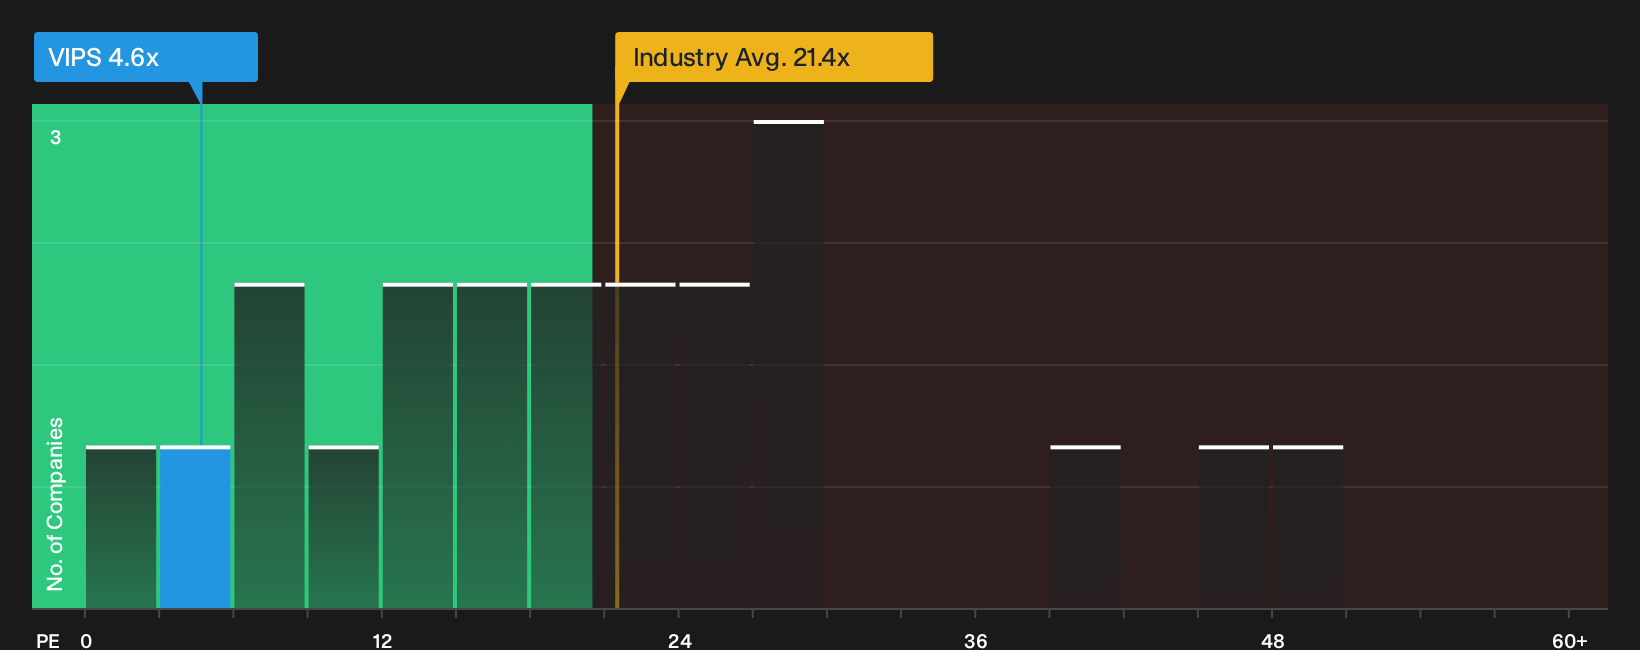
The P/E ratio suits Vipshop Holdings because earnings are a key lens for a retailer that already converts merchandise into cash at scale. At roughly 4.6x earnings, Vipshop trades well below the Multiline Retail industry average of about 20.6x and sits at a discount to the broader peer group around 15.8x. That is a wide gap for a business that already generates positive free cash flow rather than one still proving its model.
The Fair Ratio, which gauges what a more tailored P/E might look like given Vipshop's margins, growth profile, size and risk, comes in higher than where the stock currently trades. That points to a valuation that screens undervalued on this earnings yardstick, although any investor still needs to weigh factors like competitive pressure in Chinese e-commerce, cyclicality in discretionary spending and the reliability of future cash flows before leaning too hard on a single metric. Explore the numbers behind Vipshop Holdings's P/E valuation.
The Vipshop Holdings Narrative: What Would Justify Today's Price?
Vipshop Holdings' Simply Wall St Narratives pick up where the P/E discussion leaves off by explaining which paths for future growth, profitability and earnings would need to occur for the share price to look meaningfully higher or lower than it does today. These narratives are available on the stock's Community page so you can see how different views compare. Rather than relying on a single ratio or model output, each narrative sets out its assumptions so you can compare them with actual results as they are reported.
Bulls and bears looking at Vipshop Holdings are reading the same playbook on weak demand and SVIP concentration, but they part ways on how much support buybacks and outlets really provide.
Bull case: 19% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which blends multiple analysts' forecasts into a single storyline.
"Continued growth in Vipshop Holdings SVIP member base, which already accounts for more than half of online spending, can lift average order values and repeat purchase rates…"
Discover why this Narrative puts Vipshop Holdings at 19% undervalued.
Bear case: 8% overvalued
This angle is based on the bearish analyst Narrative on Simply Wall St, which leans on the most cautious forecasts and price targets.
"Although value-conscious shopping supports Vipshop Holdings off price positioning, analysts cutting price targets after the Q2 2026 revenue miss and outlet deconsolidation point to the risk that ongoing weak consumption keeps total net revenues under pressure…"
Explore why this Narrative puts Vipshop Holdings at 8% overvalued.
Before acting on Vipshop Holdings' valuation, there is one more angle to check
Price and earnings only tell part of the story for Vipshop Holdings. Recent research has also flagged specific risk checks that could change how you view the whole picture. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com